
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
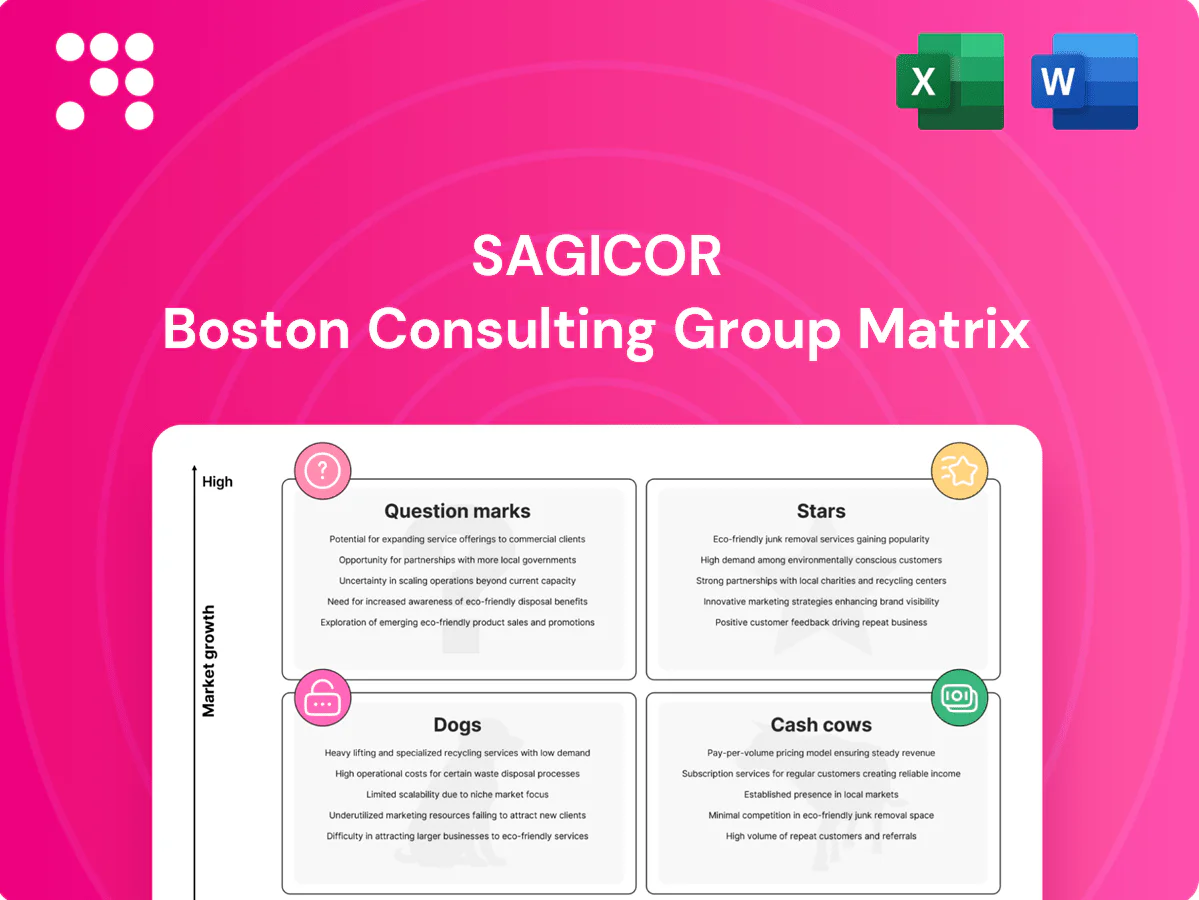
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Want a clear, no-nonsense view of Sagicor’s product portfolio? Grab the full BCG Matrix to see which offerings are Stars, Cash Cows, Dogs, or Question Marks—and get quadrant-by-quadrant analysis you can act on. The complete report includes strategic recommendations, visual maps, and editable Word and Excel files so you can present and plan immediately. Purchase now and skip the guesswork—turn data into decisions.
Sagicor is a Caribbean life-insurance leader with high market share while the region’s protection gap remains large, with life insurance penetration generally under 3% of GDP in 2024. The group leads on brand and distribution but continues to burn cash on advisor networks, underwriting tech and promotion to defend share. Keep investing to protect growth—this franchise can scale into materially higher margins as lapse and persistency improve.
US annuities sit as a Star for Sagicor as the 65+ cohort heads toward 73 million by 2030 and 10-year Treasury yields near 4.2% in 2024 lift demand and product competitiveness. Acquisition costs and elevated reserves absorb cash today, but scale is compounding—sales growth can outpace costs as lifetime margins mature. Hold share, deepen broker partnerships, streamline onboarding, and maintain investment in distribution—today’s spend funds tomorrow’s cash cow.
Employers across the Caribbean and LatAm are upgrading benefits as labor markets formalize: informal employment stood at about 46% in the region (ILOSTAT, 2022), driving demand for employer-sponsored health cover. Claims management and scaled wellness programs need upfront CapEx but deliver higher retention, often boosting tenure and reducing turnover costs. Sagicor should own the midsize employer tier, standardize plans, stay visible in-market and price with discipline to capture ongoing growth.
Pensions administration in formalizing markets is a star for Sagicor: regulatory nudges and tax incentives are lifting participation, contributing to the global pension asset pool now estimated near 60 trillion USD (2023–24), while admin platforms and compliance teams carry high fixed costs that amortize as plans scale and fees grow. Win plan sponsors now and cross-sell life/health later; keep pushing digital onboarding and employer education to accelerate take-up.
Digital bancassurance cross-sell is a Star: bank + insurance data creates high-conversion moments in fast-growing online channels; push seamless quotes in banking flows and automate underwriting to capture lifetime value. It is capital- and tech-hungry to stitch journeys, but unit economics sharpen with volume—2024 trends show online channels handling roughly one-third of retail leads, boosting conversion and retention.
Sagicor’s Stars: Caribbean life (high share; life penetration <3% of GDP in 2024) and US annuities (65+ → 73m by 2030; 10y Treasury ~4.2% in 2024) plus pensions admin and digital bancassurance—each needs upfront capex/reserves but scale drives margin expansion, cross-sell and retention gains.
| Metric | Value |
|---|---|
| Life penetration (Caribbean, 2024) | <3% GDP |
| 65+ cohort (2030) | ~73m |
| 10y Treasury (2024) | ~4.2% |
| Online leads (2024) | ~33% |
| Pension assets (2023–24) | ~$60tr |
 Detailed Word Document
Concise BCG analysis of Sagicor's product portfolio, mapping Stars, Cash Cows, Question Marks and Dogs with strategic recommendations.

 Customizable Excel Spreadsheet
One-page BCG snapshot placing Sagicor units by growth and share, easing portfolio decisions for busy execs.
Legacy individual life blocks in mature islands hold high market share with slow premium growth and steady recurring premiums; lapse and mortality patterns are stable, yielding predictable margins. Operational efficiency gains come from service automation and claims straight-through processing to reduce expense ratios. Surplus released from lower capital strain can be redirected to fund newer product lines and digital distribution initiatives.
Stable AUM from pensions and insurers delivers predictable fee income with modest capex; institutional mandates typically earn fee margins around 40–50 basis points (industry 2024 averages) and benefit from strong operating leverage. Growth is muted but margin expansion is possible by keeping fees competitive and performance consistent. Reinvest excess cash to seed new strategies at 1–3% of AUM rather than chasing short-term flows.
Retail banking in core Caribbean markets is a cash cow for Sagicor: customer deposits are sticky (retention rates above 80%) and net interest income delivers roughly 60% of banking revenue in steady cycles. Limited expansion needed; efficiency gains matter more—optimize branches, push self‑serve channels and tighten credit operations to reduce costs. Harvest cash flows while avoiding risky stretch into high‑volatility markets.
General insurance renewals with long‑tenure clients (commercial property and select SME lines) deliver stable premiums and achieved renewal rates near 88% in 2024; claims remain manageable through disciplined underwriting and reinsurance, preserving a market‑competitive loss ratio. Focus on loss‑ratio hygiene and expense control lets cash flows fund growth areas without starving service.
Core cash cows—legacy individual life, asset management, retail banking, general insurance renewals and group life riders—deliver predictable, high-margin cash flows in 2024: stable retention (88–90%+), fee margins 40–50 bps, NII ~60% of bank revenue, low capex and reinvestment 1–3% AUM; prioritize expense control, automation and redeploy surplus into growth initiatives.
| Segment | 2024 metric | Margin/notes |
|---|---|---|
| Individual life | Stable premiums | Predictable margins |
| Asset Mgmt | 40–50 bps | Reinvest 1–3% AUM |
| Retail bank | NII ~60% | Deposits sticky >80% |
| Gen ins | Renewal 88% | Disc. underwriting |
| Group life | >90% retention | Low admin |
The file you're previewing is the exact Sagicor BCG Matrix report you'll receive after purchase—no watermarks, no placeholders, just the finished, fully formatted document. It’s crafted by strategy experts for clarity and immediate use in planning or presentations. Once purchased you’ll get the downloadable, editable file to your inbox with zero surprises. Ready to present, print, or plug into your deck right away.
Overbranched micro-locations show low growth and market share with high fixed costs, and the math doesn’t work: branches with <50 daily transactions often fail to break even. Turnarounds eat cash and time; 2024 digital adoption (≈72%) makes client migration viable. Consolidate or exit underperforming sites, move clients to digital channels, and avoid letting sentiment-driven retention strategies tax the P&L.
Commodity motor lines show hyper-competitive pricing with little market power; combined ratios now exceed 100% as fraud and parts inflation erode margins. Break-even at best, cash trap at worst — exposure ties up capital that delivered negative underwriting returns in recent periods. Strategy: shrink exposure, reprice aggressively, or partner out; redeploy capital to higher-return segments.
For Sagicor's BCG Dogs, 2024 industry estimates show legacy IT can consume up to 70% of IT maintenance budgets, holding back speed, keeping Opex high and contributing no growth. Big‑bang rewrites frequently miss ROI as many large transformations blow timelines and costs. Triage: decommission, migrate, or vendor‑host to release cash tied in upkeep.
Small‑ticket retail lending in saturated pockets shows low market share and rising credit costs that have largely erased spreads; in 2024 Caribbean cost of funds rose to roughly 7–9% making unsecured yields marginal. Marketing spend yields negligible volume lift. Tighten origination criteria or wind down marginal books and redirect capital to secured or relationship‑driven credit with higher recovery rates.
Non-core, low-yield real estate sits as a Dogs quadrant item: capital parked with minimal income and no strategic pull, while upkeep nibbles margins. With 2024 benchmark yields (US policy ~5.25%), redeploy into higher-return finance assets where possible; divest or pursue sale-leaseback to free capital.
Dogs: low-share, low-growth units draining capital—underperforming branches (<50 tx/day), commodity motor lines (combined ratio ~105%), legacy IT (≈70% of maintenance spend), small retail books (CoF 7–9%); consolidate, divest, or migrate clients to digital (2024 digital adoption ≈72%).
| Item | 2024 Metric |
|---|---|
| Branches | <50 tx/day |
| Digital | 72% adoption |
| Motor | CR ~105% |
| IT | 70% maint. |
| CoF | 7–9% |
US Hispanic protection is a growing market—Hispanics comprise roughly 19% of the US population (~64 million in 2024), but Sagicor’s share remains small. Distribution, culturally tuned products and bilingual service are the clear unlocks to raise penetration. Invest to rapidly test geographies and partners; monitor CAC closely. If customer acquisition cost normalizes this can flip to a Star; if not, cut.
Adoption of telehealth and wellness add-ons has risen sharply since 2019, with virtual visit volumes remaining multiple times higher than pre‑COVID levels and the global telehealth market projected to exceed $180B by mid‑decade, yet unit economics for insurers remain mixed. Such services can cut claims and lift retention, but may also add cost if utilization is low. Pilot with clear ROI gates, shared‑savings contracts and breakpoints (seek ≥2–3pp loss‑ratio improvement) and scale only where utilization yields measurable loss‑ratio wins.
Mobile microinsurance in LatAm/Caribbean sits in a high-growth addressable market—over 400 million mobile subscribers and expanding fintech rails—while Sagicor’s share remains nascent. Premiums per policy are tiny and churn high, but embedded telco/fintech distribution materially lowers acquisition cost. Double down on one or two anchor partners and kill pilots that don’t meet unit economics by predefined milestone dates.
ESG-tilted pension and asset products are question marks: client interest rose in 2024 with early positive flows, fees can be durable if outperformance persists, and priority should be seeding flagship funds while securing cornerstone mandates; if traction stalls, fold strategies into core offerings to preserve economics.
World Bank data show remittances to low- and middle-income countries reached $626 billion in 2023 with an average transfer cost ~6.3%, while Sagicor’s share in cross-border remittance flows is negligible today. Compliance regimes and FX spread dynamics determine unit economics. Pilot corridors should leverage existing customers and insurers; scale only if CAC payback and strict risk limits are demonstrable.
US Hispanic protection: 64M (19% of US pop, 2024) — low share; prioritize bilingual distribution and test CAC; flip to Star if payback <24 months. Telehealth: market >$180B (mid‑decade) — pilot with ≥2–3pp loss‑ratio improvement gates. Mobile LatAm: ~400M subscribers — pick 1–2 anchor partners; kill pilots missing unit‑economics. Remittances: $626B (2023) — corridor pilots only if CAC payback + risk caps.
| Theme | Metric | Scale gate |
|---|---|---|
| US Hispanic | 64M (19%, 2024) | Payback <24m |
| Telehealth | >$180B (mid‑decade) | ≥2–3pp LR gain |
| Mobile LatAm | ~400M subs | Anchor partners |
| Remittances | $626B (2023) | CAC payback + caps |


