
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Saltchuk's diversified maritime and logistics platform shows resilient cash flows, strong regional reach, and operational depth, but faces regulatory, fuel-cost, and consolidation risks. Our full SWOT unpacks strategic levers, financial context, and competitor positioning. Purchase the complete, editable report to plan, pitch, or invest with confidence.
Operating across maritime, aviation, fuel distribution and logistics spreads revenue risk and stabilizes cash flow for Saltchuk, which generates over $2 billion in annual revenue across its family of companies. Cross-modal capabilities enable bundled solutions and stickier customer relationships, increasing lifetime value. Diversification offsets cyclicality in any single segment and enhances bargaining power with suppliers and strategic partners.
Shipping, fuel and logistics are mission-critical and resilient: U.S. petroleum consumption averaged about 19 million barrels per day in 2023 (EIA), while global seaborne trade totaled 11.3 billion tonnes in 2023 (UNCTAD). Essential-service positioning drives steady demand from industrials, utilities and communities. That underpins long-term contracts and predictable asset utilization. It strengthens confidence in capital allocation and fleet investments.
Saltchuk’s integrated North American footprint—spanning Alaska, Hawaii, the continental U.S., Canada and the Caribbean—enables true end-to-end flows within a single family of companies, simplifying handoffs and billing. Proximity to customers reduces transit times and routing complexity, while regional depth drives superior service reliability. Those contiguous networks create strong network effects and measurable operational synergies.
Private, family ownership gives Saltchuk patient capital and multi-decade investment horizons, enabling disciplined strategy through volatile markets without quarterly earnings pressure. That stance accelerates fleet renewal and infrastructure upgrades while allowing long-term contracts and capital allocation aligned with operational resilience. It also fosters deeper, stable relationships with regulators and local communities.
Complex maritime and energy operations demand rigorous safety and regulatory standards; seaborne trade reached 11.2 billion tonnes in 2023 (UNCTAD 2024), increasing operational exposure. A strong safety culture lowers incidents, costs and downtime while consistent compliance builds trust with customers and authorities. This track record supports eligibility for high-spec, long-term energy and maritime contracts.
Saltchuk’s diversified maritime, aviation, fuel distribution and logistics portfolio generates over $2 billion revenue, stabilizing cash flow and enabling bundled, high-retention solutions. Essential-service exposure (US oil demand ~19 mb/d in 2023; global seaborne trade 11.3 bn tonnes in 2023) supports long-term contracts and high utilization. Private, family ownership supplies patient capital for fleet renewal and regional network expansion across Alaska, Hawaii, US, Canada and the Caribbean.
| Metric | 2023/2024 Value |
|---|---|
| Revenue (family of companies) | > $2.0 bn |
| US petroleum demand (2023) | ~19 mb/d (EIA) |
| Seaborne trade (2023) | 11.3 bn tonnes (UNCTAD) |
 Detailed Word Document
Provides a concise strategic overview of Saltchuk’s internal capabilities and external market factors, outlining strengths, weaknesses, opportunities, and threats to its diversified maritime, logistics, and transportation businesses.

 Customizable Excel Spreadsheet
Provides a clear, editable SWOT matrix tailored to Saltchuk, enabling rapid alignment across divisions and quick updates to reflect shifting logistics, regulatory changes, and market priorities.
Ships, aircraft, terminals and fuel infrastructure require heavy upfront and ongoing maintenance capex, driving a high capital intensity for Saltchuk.
High fixed costs increase operating leverage, magnifying margin pressure in demand downturns and seasonal slowdowns.
Long payback horizons are sensitive to utilization rates and limit flexibility compared with asset-light competitors that can scale faster.
Volumes and margins at Saltchuk fluctuate with industrial activity and trade flows, exposing earnings to cyclical downturns; Brent crude averaged about 83 USD/barrel in 2024 (EIA), driving fuel-cost swings. Fuel price volatility directly raises operating costs and can dampen customer demand, while lags in pass-through mechanisms compress margins. Hedging reduces spot exposure but cannot eliminate basis and timing risks, leaving residual margin volatility.
Managing Saltchuk's portfolio of 30+ operating companies and roughly 6,000 employees across multiple jurisdictions raises regulatory, asset and labor-model complexity, increasing compliance costs and oversight burden. Integration frictions can dilute cross-company synergies and slow decision-making, while fragmented data and systems hinder enterprise-wide visibility. Governance must carefully balance local autonomy with centralized control to mitigate these risks.
As a privately held company (Saltchuk remained private in 2024), lower financial transparency can increase financing costs and extend diligence timelines for large projects. Benchmarking against public peers is harder without market valuations and regular disclosures. Talent attraction suffers without liquid equity incentives, complicating senior hires and retention.
Saltchuk's concentration in North America limits exposure to faster-growing Asia-Europe and emerging trade lanes, constraining revenue diversification. Regional shocks—seen during COVID-19 supply-chain disruptions and Alaska route interruptions—can disproportionately impact results; the company employs about 6,000 people and has reported annual revenues above 3 billion in recent years. Customer-base overlap within its regional networks raises concentration risk, and meaningful international diversification would require new regulatory, operational and partner competencies.
High capital intensity and heavy maintenance capex for ships, aircraft and terminals raise fixed costs and margin sensitivity to demand swings. Portfolio complexity—30+ operating companies and ~6,000 employees—elevates compliance and integration friction while limiting transparency as a private firm. Regional concentration (North America) and revenue cyclicality (reported >3.0B annual revenue) constrain diversification.
| Metric | Value |
|---|---|
| Employees | ~6,000 |
| Annual revenue | >3.0B |
| Operating companies | 30+ |
| Brent 2024 avg | ~83 USD/barrel (EIA) |
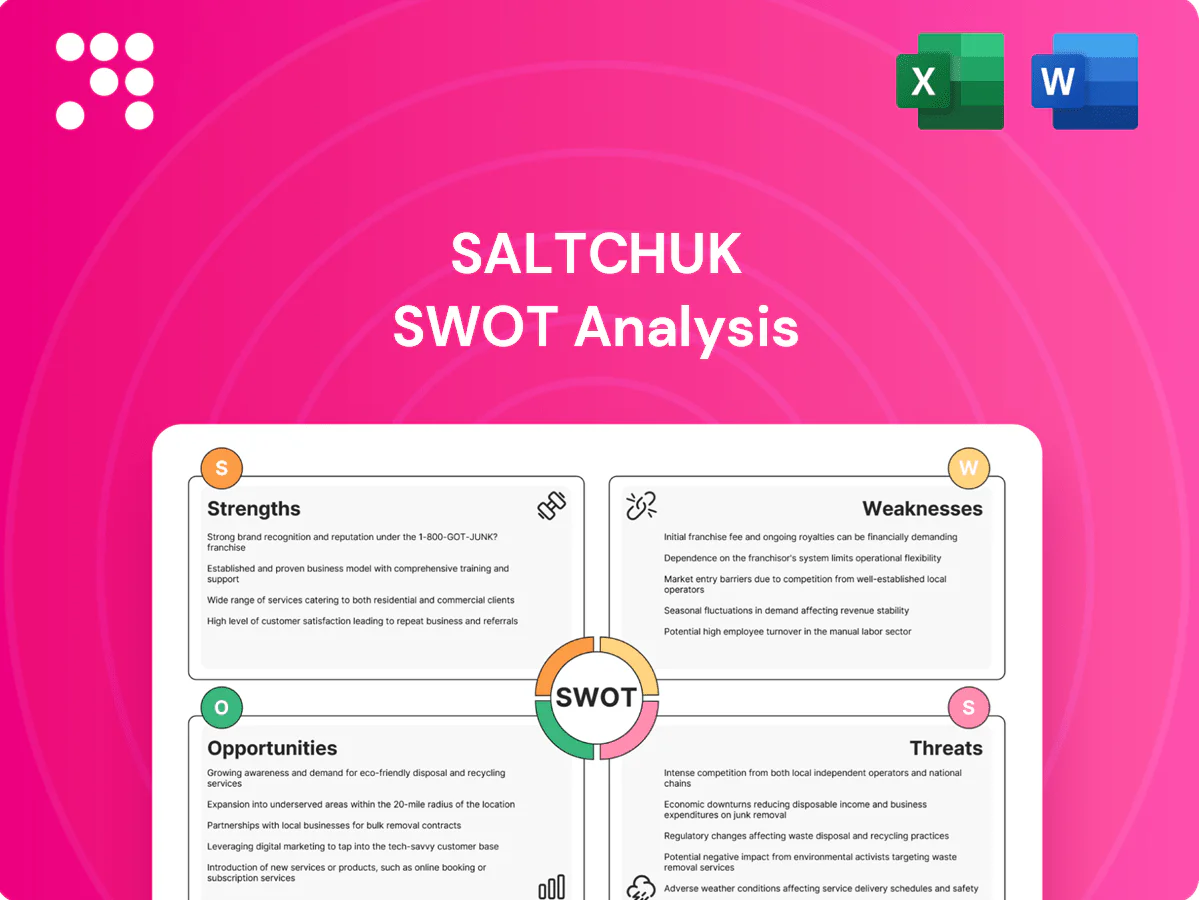
This is the actual SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report; once purchased you’ll get the complete, editable version. You’re viewing a live preview of the real file, and the entire detailed document becomes available immediately after checkout.
Expanding into renewable diesel, SAF logistics, LNG bunkering and related infrastructure can open new profit pools as US Inflation Reduction Act credits for SAF reach up to $1.25 per gallon and the IMO seeks ~50% GHG reduction by 2050, driving demand for lower-carbon fuels. Customers increasingly pay premiums for reliable, lower-carbon supply chains, enabling Saltchuk to lock long-term offtakes and secure incentives. Early-mover assets also future-proof fleets amid tightening emissions rules.
Reshoring and nearshoring lifted North American trade, with US‑Mexico goods trade topping roughly $700 billion in 2023 and Mexico becoming the US's largest trading partner that year, driving higher regional freight demand. Customers increasingly seek redundant multimodal routes to cut disruption risk, creating demand for bundled maritime–air–road offerings. Saltchuk can capture share by selling integrated solutions and investing in purpose-built regional hubs to secure sticky volumes.
Investing in visibility platforms, IoT (over 30 billion endpoints projected by 2025) and predictive analytics (predictive maintenance can cut downtime 30–50%) boosts asset utilization and enables dynamic pricing and route optimization to lift margins. Data-driven service differentiation raises retention and the same telemetry streamlines compliance and safety monitoring.
Strategic M&A and partnerships can accelerate roll-ups across fragmented marine, aviation cargo and fuel distribution niches where Saltchuk’s network of over 50 subsidiaries provides strong scaffolding; acquiring adjacent capabilities deepens integrated end-to-end offerings and supports cross-selling.
Joint ventures can open new corridors and specialized assets while scale enhances procurement bargaining power and capital efficiency, lowering unit costs and improving asset utilization.
Rising e-commerce — global retail e-commerce reached about 5.7 trillion USD in 2024 — drives demand for expedited and regional parcel lift and last-mile support, with time-definite services commanding premiums often reported near 15–25% above standard freight rates. Cross-dock and cold-chain buildouts open healthcare and perishables verticals, while integrated networks cut order-to-delivery cycles.
SAF logistics capture $1.25/gal IRA credit as multimodal demand and IoT boost margins
Renewable diesel/SAF logistics capture IRA credits up to $1.25/gal and align with IMO ~50% GHG cut by 2050; early assets secure incentives. Regional trade (US‑Mexico ~$700B in 2023) and e‑commerce ($5.7T in 2024) boost multimodal demand. IoT (~30B endpoints by 2025) and analytics raise utilization and margins.
| Metric | Value |
|---|---|
| SAF credit | $1.25/gal |
| US‑Mexico trade 2023 | $700B |
| E‑commerce 2024 | $5.7T |
| IoT 2025 | ~30B endpoints |
Recessions cut freight volumes and discretionary shipping — global goods trade volume growth slowed to about 1–2% in 2024 (IMF/WTO guidance), pressuring Saltchuk’s volumes; industrial slowdowns dent heavy cargo and fuel demand, with the Baltic Dry Index averaging ~1,200 in 2024 signaling weak dry-bulk demand; oversupply fuels rate pressure (container/liner rates down ~10–20% vs 2022) and recovery timing remains uneven across modes.
Stricter emissions, safety and ESG rules are raising compliance costs across shipping and logistics; EU carbon prices spiked to roughly €80–100/ton in 2024, directly increasing operating expense. Fleet retrofits and fuel-switching can strain capex, with conversions or new-fuel installations typically running $3–10 million per vessel. Noncompliance risks fines, multimillion-dollar penalties, reputational damage and lost contracts, while sudden policy shifts can abruptly alter project economics and return assumptions.
Pilots, mariners and skilled technicians remain scarce—BIMCO/ICS forecast a seafarer shortfall of about 147,500 by 2025—forcing premium hiring and training costs. Wage inflation (US average hourly earnings rose ~4.3% year‑over‑year in 2024 per BLS) compresses margins and hikes contract pricing. Strikes or stoppages have recently disrupted key lanes, amplifying revenue volatility. Training and retention programs are capital‑ and time‑intensive to scale.
Hurricanes, wildfires and floods increasingly disrupt ports, routes and terminals; NOAA recorded 28 US billion‑dollar weather disasters costing $71B in 2023. Asset damage and insurance costs rose sharply, with commercial property rates up ~25% in 2023–24 per market reports, while schedule reliability dropped toward ~35% in 2022–23 and Panama Canal drought cut transits ~5% in 2023, creating chronic corridor constraints.
Large global carriers such as Maersk and MSC and asset-light 3PLs intensify price competition, especially on transpacific and Asia-Europe lanes where episodic overcapacity triggers rate wars and margin compression. Customer procurement increasingly favors multi-bid tenders and shorter-term contracts, forcing Saltchuk to prove differentiation against commoditization to defend rates and share.
Recession-driven volume weakness (global goods +1–2% in 2024; BDI ~1,200; container rates -10–20% vs 2022) compresses revenue; regulatory and ESG costs (EU carbon €80–100/ton in 2024; retrofit capex $3–10M/vessel) raise OPEX and capex; crew shortfall (~147,500 by 2025) and wage inflation (~4.3% 2024) hike labor costs; climate losses (28 US disasters, $71B in 2023) push insurance +~25%.
| Metric | Value |
|---|---|
| Global goods growth (2024) | ~1–2% |
| Baltic Dry Index (2024) | ~1,200 |
| Container rates vs 2022 | -10–20% |
| EU carbon (2024) | €80–100/ton |
| Seafarer shortfall (2025) | ~147,500 |
| US climate losses (2023) | 28 events, $71B |
| Insurance/property rates (2023–24) | +~25% |


