
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Cover political, economic, social, technology, legal and environmental change.
Separate market signals from their business impact.
Create a structured view of opportunities and exposure.
Unlock strategic clarity with our targeted PESTLE Analysis of Santec—revealing how political shifts, economic trends, social dynamics, technology advances, legal changes, and environmental pressures will shape its trajectory. Ideal for investors, consultants, and strategists, this concise briefing highlights key risks and opportunities. Purchase the full analysis to access the complete, editable report and actionable insights instantly.
US EAR and ITAR-adjacent rules, mirrored by EU and Japan coordination, restrict shipments of advanced tunable lasers and OCT subsystems and increasingly target transfers to China and Russia.
Tightening controls require export licenses and can delay deliveries, raise compliance costs, and force rerouting of orders away from restricted jurisdictions.
Proactive product classification, licensing and end‑use screening preserves key accounts and mitigates denial risk, making dual‑use risk assessment a core sales‑enablement step.
Optical components depend on precision parts, rare materials and specialty semiconductors concentrated in hubs (Taiwan supplies ~92% of advanced logic capacity) so geopolitical tensions and chokepoints (Suez handles ~12% of seaborne trade) can disrupt deliveries and force higher inventory buffers. Nearshoring and multisourcing lower risk but add procurement complexity and capex; US CHIPS Act ($52bn) and EU chips initiatives (~€43bn) offer relocation incentives.
Public investments such as the US Infrastructure Investment and Jobs Act allocating roughly 65 billion dollars for broadband and EU Digital Decade targets (gigabit-ready households and 5G in all populated areas by 2030) drive demand for test gear and tunable lasers; the timing and scale of state-backed rollouts materially affect order visibility. Market protectionism in China and some markets favoring domestic vendors shifts competitive dynamics, while active participation in ITU, 3GPP and IEEE forums helps Santec align product roadmaps with funded standards.
OCT adoption hinges on screening programs and reimbursement codes in ophthalmology and cardiology; changes in CPT/DRG/NR codes quickly alter hospital purchasing cycles. Public health drivers—diabetes (537 million adults in 2021) and an aging population (65+ 9.3% in 2020)—support rising OCT volumes, while payer and society engagement shapes evidence thresholds for coverage.
Japan and EU R&D grants (Horizon Europe budget €95.5bn through 2027; Japan has pledged ~¥1 trillion+ for semiconductor support by 2025) can co-fund Santec product development in photonics, sensing and equipment, raising ROI and reducing burn. Alignment with national priorities such as secure communications and biomedical imaging increases grant win rates and market access. Consortium roles let Santec shape standards and timing of awards smooths internal R&D cashflow.
Export controls (US EAR/ITAR, EU/Japan alignments) tighten deliveries to China/Russia, raising compliance costs and license delays; Taiwan holds ~92% advanced logic capacity and Suez handles ~12% seaborne trade, creating chokepoint risk. Public funding (US CHIPS $52bn, Horizon Europe €95.5bn to 2027, Japan ~¥1tn) boosts nearshoring and R&D; reimbursement and CPT/DRG changes rapidly shift OCT demand timing.
| Factor | Key Data (2024/25) |
|---|---|
| Export controls | EAR/ITAR, targeted at China/Russia |
| Chip capacity | Taiwan ~92% advanced logic |
| Trade chokepoints | Suez ~12% seaborne trade |
| Public funding | US CHIPS $52bn; Horizon €95.5bn; Japan ~¥1tn |
| Health drivers | Diabetes 537M (2021); aging 65+ 9.3% (2020) |
 Detailed Word Document
Explores how macro-environmental factors uniquely affect Santec across Political, Economic, Social, Technological, Environmental and Legal dimensions; each section is data-backed, region- and industry-specific, forward-looking, and formatted for executives, investors and strategists to spot risks, opportunities and inform scenario planning.

 Customizable Excel Spreadsheet
A concise, visually segmented Santec PESTLE summary that clarifies external risks and market drivers at a glance, ideal for meeting briefs or pitch decks. Editable notes and shareable formatting let teams quickly align on strategy and adapt insights to their region or business line.
Operator capex waves drive spikes in optical test and component orders, with buildout phases creating concentrated demand; subsequent inventory corrections can produce sharp downturns lasting quarters. Santec’s move into biomedical and industrial sensing cushions revenue swings by diversifying end markets. Long-term fiber densification remains a structural tailwind, with global fiber premises passed exceeding 400 million by end-2024, underpinning secular growth.
Global sales denominated in USD/EUR/CNY translate into earnings volatility for Santec as USD/JPY averaged around 155 and EUR/JPY about 167 in H1 2025, while CNY/JPY traded near 22, so yen strength compresses margins and yen weakness boosts exports but raises import costs. Hedging programs and natural offsets across offshore revenues mitigate swings, and pricing clauses on multi‑year, long‑lead projects protect project margins.
With the US policy rate near 5.25–5.50% in mid‑2025, higher rates are squeezing customer capex and hospital equipment budgets, lengthening Santec sales cycles as purchasers defer non‑critical upgrades. Targeted financing and leasing solutions have proven to unlock OCT and lab purchases by spreading cost and lowering upfront burden. A move back to lower rates typically accelerates backlog conversion, while rising internal WACC raises hurdle rates and reduces DCF valuations for new product investments.
Consolidation among optical component vendors and test OEMs has raised supplier bargaining power, concentrating procurement—global photonics M&A value rose notably into 2023–24. Niche leadership in tunable lasers and OCT lets Santec sustain premium pricing and ASPs above commodity optics. Bundled solutions expand wallet share, raise switching costs, and M&A accelerates entry into adjacent photonics niches.
Operator capex waves create sharp optical demand spikes and inventory-driven downturns; Santec’s biomedical/industrial diversification cushions revenue volatility. Global fiber premises passed exceeded 400 million end-2024, underpinning secular growth. FX: USD/JPY ~155, EUR/JPY ~167, CNY/JPY ~22 in H1 2025, and US policy rate ~5.25–5.50% mid‑2025 lengthen customer capex cycles. Supplier consolidation raises input pricing risk; long-term contracts and VMI mitigate exposure.
| Metric | Value |
|---|---|
| Fiber premises passed | 400M (end‑2024) |
| USD/JPY (H1 2025) | ~155 |
| US policy rate (mid‑2025) | 5.25–5.50% |
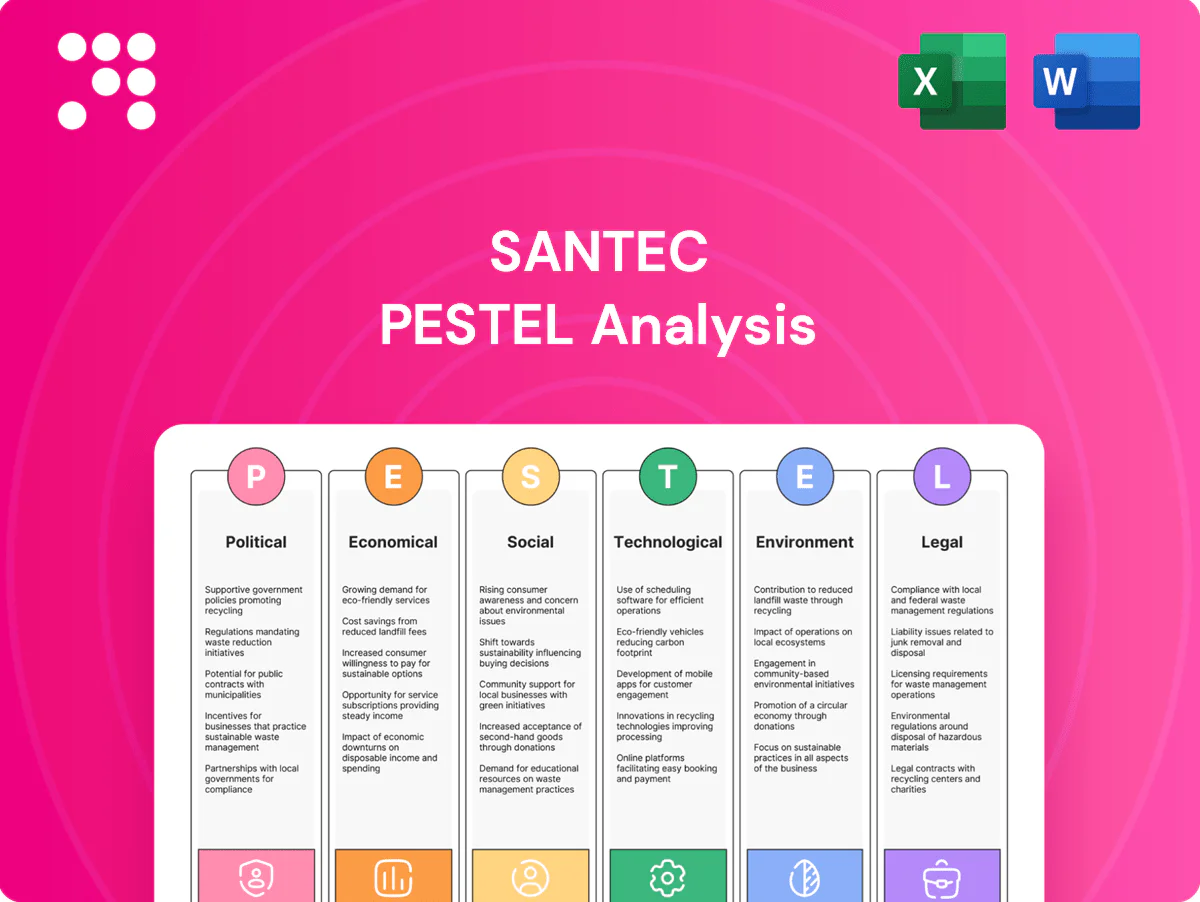
The Santec PESTLE Analysis preview shown here is the exact document you’ll receive after purchase, fully formatted and ready to use. This is a real screenshot of the product—delivered exactly as shown, no placeholders or teasers. The layout, content, and structure visible here are precisely what you’ll download immediately after payment.
UN data show about 761 million people aged 65+ in 2021 and rising, driving higher prevalence of AMD, glaucoma (≈80 million cases in 2020) and diabetic retinopathy (≈103 million in 2020), boosting OCT demand and a global OCT market ~USD 1.6–1.8B in 2023. Expanded screening programs — UK diabetic eye screening serves >2.7M annually — increase clinic diagnostic capacity. Portable, user-friendly OCTs accelerate community adoption. Training, workforce and workflow integration remain key implementation barriers per WHO workforce gap reports.
Streaming, cloud and AI workloads — with video accounting for about 66% of global downstream traffic per Cisco reports — drive higher latency and throughput demands that lift network performance expectations. Operators are migrating to 400G/800G optics, creating a need for precise test and measurement that aligns with Santec offerings. Faster rollouts and quarterly service windows increase deployment opportunities while marketing tied to end-user experience strengthens Santec's value narrative.
Skilled photonics, firmware, and AI engineers remain scarce, forcing higher hiring premiums as software developer jobs alone are projected to grow ~22% (BLS) over the decade, intensifying competition for adjacent specialties.
Employer branding, formal academia partnerships, and targeted upskilling programs are critical to close gaps and lower recruitment costs.
Flexible work policies and inclusive culture measurably improve retention, while co-location near photonics clusters expands the talent funnel through local pipelines.
A 2024 survey of 420 ophthalmologists found 72% prioritize speed and accuracy and 65% require EMR interoperability; clear OCT imaging improved patient adherence by 18% in a 2023 multicenter study. Data security and privacy concern 61% of clinicians and shape acceptance of connected OCT, while user-centric design cut training time and error rates by about 40% in recent device rollouts.
AI-assisted imaging raises concerns about bias, explainability, and clinician oversight; transparent algorithms and validated datasets (FDA has cleared over 500 AI/ML devices by 2024) build confidence. Positioning tools as decision-support, not replacements, and robust post-market monitoring address real-world performance and safety.
Aging populations (761M aged 65+ in 2021) and rising eye disease prevalence (AMD/glaucoma/DR ≈80–103M) increase OCT demand; 72% clinicians prioritize speed/accuracy and 65% require EMR interoperability. Workforce gaps and 22% projected software job growth raise hiring costs; training and partnerships reduce time-to-adopt and errors.
| Metric | Value |
|---|---|
| 65+ population (2021) | 761M |
| Glaucoma (2020) | ≈80M |
| DR (2020) | ≈103M |
| Clinician speed/accuracy | 72% |
Wider tuning ranges (commercial swept sources now reach up to ~150 nm) and faster sweep speeds (A-scan rates >200 kHz to >2 MHz in OCT) with lower noise and sub-MHz linewidths enable superior test and OCT performance. Integration reduces size, power and improves thermal stability for field instruments. Differentiation depends on coherence (linewidth) and reliability (MTBF) metrics. Roadmaps must support 800 Gbps and 1.6 Tbps test requirements.
Silicon photonics adoption is driving demand for Santec-grade precise characterization tools and compatible components as the SiPh market targets roughly 20% CAGR from 2024–2030, increasing validation needs. Co-packaged optics forces new test methodologies and thermal/electrical qualification workflows. Strategic partnerships with foundries and OSATs accelerate feature alignment and tapeouts. Interoperability with PIC design flows is a key product differentiator.
On-device and cloud AI improve OCT image quality, segmentation and triage, combining low-latency edge inference (often <100 ms) for clinic workflow with cloud models for heavy analytics; regulatory-grade datasets and continuous-learning pipelines underpin safety and performance, supported by over 100 FDA-cleared AI/ML medical devices as of 2024 (first retinal autonomous device IDx-DR cleared 2018); APIs enable EMR and PACS integrations via FHIR/DICOM connectors.
Precision assembly, active alignment and in-line metrology improve yield and consistency—industry reports show automated optical assembly can cut process variation by about 25% and trim scrap; automation also mitigates skilled labor shortages and operator variability, with global robot installations rising ~8–10% in 2023–24. SPC and full traceability underpin ISO/AS certifications and CAPA, while capex in flexible cells shortens NPI ramp times by up to ~30% according to recent manufacturing case studies.
Networked instruments and OCT systems face growing ransomware and data-exfiltration risks; healthcare breaches cost an average of $11.97M in 2023 (IBM). Secure boot, strong encryption, and SBOMs are increasingly table stakes. Firmware OTA pipelines require rigorous signing and rollback controls. Compliance with healthcare security frameworks materially builds customer trust and market access.
Wider tuning (swept sources ~150 nm) and OCT A-scan >200 kHz–2+ MHz with sub-MHz linewidths shape specs and 800G–1.6Tbps test roadmaps. Silicon photonics (~20% CAGR 2024–2030) and co-packaged optics expand validation needs. Automation (robot installs +8–10% 2023–24) and security (healthcare breach cost $11.97M 2023) are mandatory.
| Metric | Value |
|---|---|
| Swept range | ~150 nm |
| OCT A-scan | >200 kHz–2+ MHz |
| SiPh CAGR | ~20% (2024–2030) |
| Robot growth | +8–10% (2023–24) |
| Healthcare breach cost | $11.97M (2023) |
Product classifications under EAR/ITAR and end-use checks are mandatory for Santec, with EAR covering dual-use and ITAR covering defense articles; recent US Commerce semiconductor controls (2022–23) tightened licensing for advanced chips. Denied-party screening and distributor oversight are essential after sanctions can instantly close markets; robust compliance preserves revenue and reputation amid escalating enforcement and expanded controls.
OCT systems must satisfy design controls, clinical evidence and ISO 13485:2016 QMS; EU MDR has been applicable since 26 May 2021. Regulatory review timelines (PMDA, FDA, CE) vary by region and can extend from months to years, directly affecting launch cadence. Post-market surveillance and vigilance reporting (PSURs, incident reports) create ongoing costs, so harmonizing technical files across jurisdictions reduces duplication and compliance spend.
Santec's strong patents on tunable lasers, sweep engines and imaging algorithms create a durable moat, supporting product differentiation in a global photonics market valued at roughly $650B in 2024. Regular freedom-to-operate analyses have reduced litigation exposure in crowded photonics domains, while defensive publications and cross-licensing deals preserve commercialization flexibility. Vigilant enforcement of IP rights deters copycats and protects revenue streams.
GDPR and HIPAA govern OCT-derived patient data and connected software; GDPR fines can reach 4% of global turnover or €20m, while HIPAA civil penalty caps can hit $1.5m per violation category annually. Privacy-by-design, explicit consent and robust de-identification are mandatory; DPA/BAA contracts formalize provider obligations and over 50 countries now impose some data residency/localization rules.
Standards such as IEC 60825 (laser safety) and the EMC Directive 2014/30/EU directly shape Santec’s design and shielding choices; RoHS limits 10 substance groups while REACH covers over 22,000 registered chemicals, forcing careful materials selection. Extensive documentation and third-party testing routinely extend time-to-market, and non-compliance risks costly recalls and regulatory fines.
EAR/ITAR classification, US 2022–23 semiconductor controls, EU MDR (since 26 May 2021) and privacy laws (GDPR 4%/€20m, HIPAA $1.5m) drive Santec compliance; strong patents and FTAs protect market position in a global photonics market ~ $650B (2024). Standards IEC 60825, RoHS (10 substances) and REACH (>22,000) shape design and TTM.
| Metric | Value |
|---|---|
| Photonics market | $650B (2024) |
| GDPR fine | 4% turnover/€20m |
| HIPAA cap | $1.5M/category |
| RoHS substances | 10 |
| REACH entries | >22,000 |
Lower-power lasers and test systems can cut operating costs and emissions, with efficiency improvements often trimming electricity use by 10–30%. Customers with ESG targets — sustainable assets totaled $35.3 trillion in 2022 — increasingly favor energy-smart gear. Thermal-management design can reduce facility cooling loads (cooling often represents ~30–40% of data-center energy). Built-in energy-data reporting serves as a clear sales differentiator.
Compliance with RoHS (original six restricted substances) and EU REACH (over 22,000 registered substances) and safe handling of solvents and photoresists is critical to Santec’s operations. Robust waste-minimization and proper disposal programs reduce hazardous waste volumes and liability. Material substitutions to meet regs can alter device performance and raise unit costs. Regular supplier audits verify upstream adherence to chemical and waste controls.
Optics manufacturing drives high cleanroom energy use—often up to 50–60% of site energy—and heavy ultrapure water (UPW) demand; recirculation and UPW reclaim systems can cut water use by as much as 70–90% and HVAC/LED and process-efficiency upgrades commonly lower energy 20–40%. Santec aligns with ISO 14001 frameworks for continuous improvement and publishes metrics (water, kWh, waste) to support customer sustainability audits.
Circularity reduces Santec's e-waste footprint: repairability, modular designs and take-back schemes cut disposal volumes while refurbished units open price-sensitive markets; global e-waste was about 59 million tonnes in 2021 (Global E-waste Monitor 2023) and is projected to reach ~74 million tonnes by 2030, increasing demand for reuse and refurbishment. Component harvesting cushions supply-chain shocks and clearer EPR rules across major markets ease market access and compliance costs.
Extreme weather increasingly disrupts suppliers and shipping lanes, driving Santec to hold buffer stocks, adopt dual-site production and use physical climate-risk maps in location strategy to protect continuity.
Low-carbon logistics and recyclable packaging target reductions in Scope 3, while emissions disclosures are being aligned with customer RFP requirements and procurement expectations.
Energy-efficiency cuts operating electricity 10–30% while cleanrooms consume ~50–60% of site energy; UPW reclaim can cut water 70–90%. Global e-waste was 59 Mt in 2021 and may hit ~74 Mt by 2030; ESG assets were $35.3T in 2022. Santec prioritizes Scope 3 cuts, circular design, dual-site resilience and supplier chemical compliance (RoHS/REACH).
| Metric | Value | Year/Source |
|---|---|---|
| Electricity savings | 10–30% | Industry estimates 2024 |
| Cleanroom energy | 50–60% | Manufacturing studies 2023 |
| UPW reclaim | 70–90% | Case studies 2022–24 |
| Global e-waste | 59 Mt (2021) | Global E‑waste Monitor 2023 |


