
Digital download
Access the files immediately after checkout.
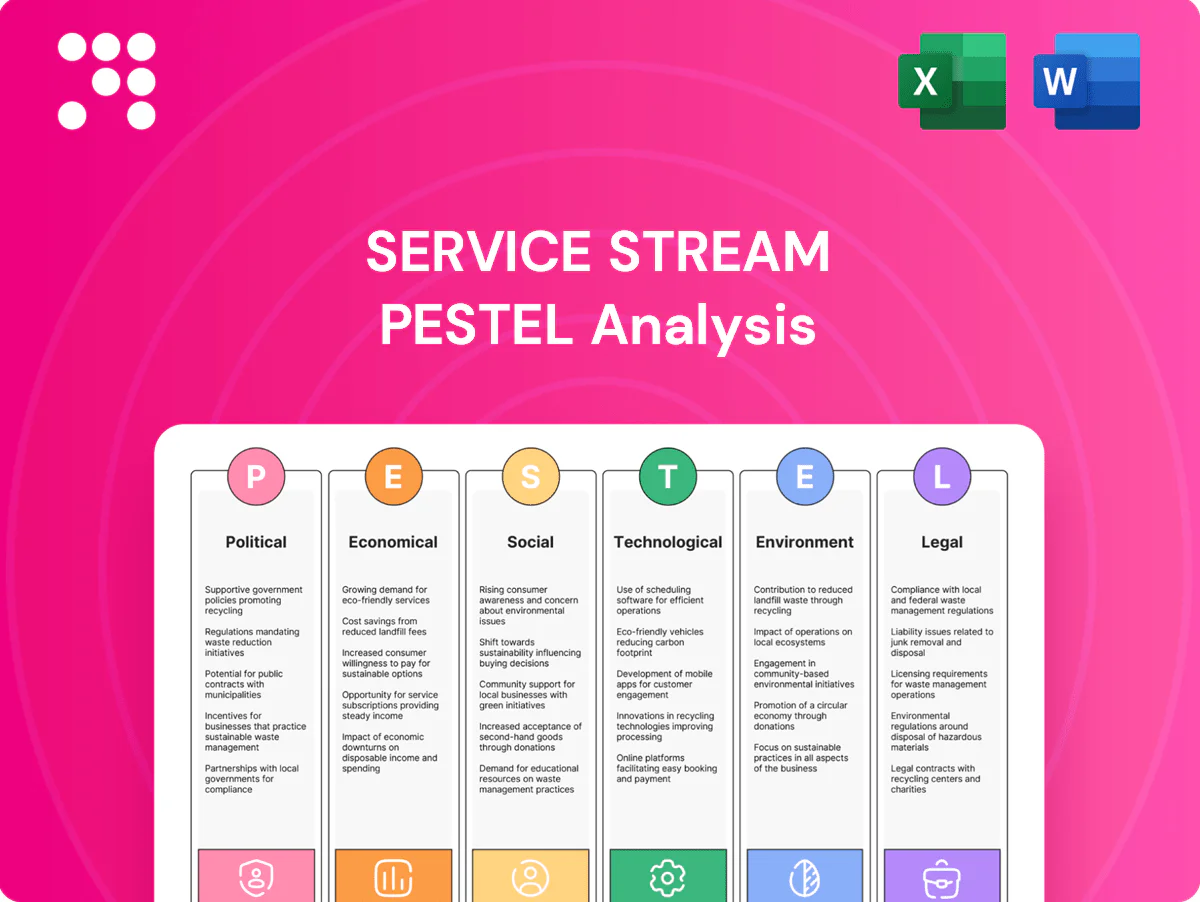
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Cover political, economic, social, technology, legal and environmental change.
Separate market signals from their business impact.
Create a structured view of opportunities and exposure.
Gain actionable insight with our PESTLE Analysis of Service Stream—three to five focused sentences explore how political, economic, social, technological, legal and environmental factors shape the company’s strategy and risk profile. Ideal for investors, consultants and executives, this concise briefing highlights threats and opportunities you can act on immediately. Purchase the full report for the complete, editable breakdown and data-driven recommendations.
Federal and state infrastructure agendas drive volumes across telecom, energy and water with a combined pipeline of over A$100 billion over the next decade; priority programs in regional connectivity, grid resilience and water security are increasing pipeline visibility. Policy continuity underpins long-cycle contracts (commonly 5–15 years), while post-election shifts can re-sequence spend, so Service Stream must align bids to evolving government priorities.
PPP frameworks determine risk allocation, payment profiles and long-term maintenance obligations—concessions commonly span 20–30 years, shifting lifecycle costs to private partners. Transparent procurement and value-for-money tests favor experienced operators in critical assets, with Australia’s infrastructure pipeline estimated at about A$600 billion to 2032 boosting PPP opportunities. Shifts in PPP policy can rapidly expand or curtail deal flow, so building consortium relationships improves award likelihood.
Heightened scrutiny of critical infrastructure drives stricter vendor approvals and data handling, with security reviews commonly adding up to 12 months to mobilization for network projects.
Foreign investment rules and security vetting can delay entry to multi-million-dollar contracts; compliant vendors gain access to sensitive network work scopes and strategic programmes.
Non-compliance risks exclusion from government and national security tenders, often representing a loss of revenue in the tens of millions for affected suppliers.
Government goals to bridge the digital divide—evidenced by the US BEAD program's $42.45 billion broadband investment and global 5G subscriptions topping 1 billion by 2024 (GSMA)—drive rural fiber and 5G rollouts, with subsidies and co-funding lowering commercial risk and enabling remote-work hubs. Execution in challenging geographies requires robust logistics and capex planning; strong on-time delivery and SLAs improve standing in future tenders.
Policies now require meaningful Indigenous participation on public works, with the Australian Government NIPP target of 3% Indigenous procurement driving contract clauses; many state contracts embed 2–5% supplier-spend and specific employment/training targets. Strong Indigenous engagement can differentiate bids and win premium scoring, while poor performance risks contract renewals and penalties.
Federal/state infrastructure pipelines (A$100bn near-term; A$600bn to 2032) and long-cycle contracts (5–15 yrs) drive demand while PPP concessions (20–30 yrs) shape lifecycle risk. Security vetting and foreign investment rules can add ~12 months to mobilization; BEAD $42.45bn and 5G >1bn subs (2024) boost rural/telecom work. Indigenous procurement targets (3% federal; 2–5% state) affect scoring and penalties.
| Metric | Value |
|---|---|
| Near-term pipeline | A$100bn |
| Pipeline to 2032 | A$600bn |
| BEAD | $42.45bn |
| 5G subs (2024) | >1bn |
| Indigenous target | 3% federal |
 Detailed Word Document
Explores how macro-environmental factors uniquely affect Service Stream across Political, Economic, Social, Technological, Environmental and Legal dimensions, with data-backed trends and region- and industry-specific subpoints to identify threats and opportunities.

 Customizable Excel Spreadsheet
A concise, visually segmented PESTLE summary tailored to Service Stream that highlights external risks and opportunities for quick team alignment, easy insertion into presentations, and on-the-spot use in planning or client reports.
Utility capex cycles drive demand for design, build and maintenance: global energy investment topped US$2.4tn in 2023 with clean-energy spending over US$1.3tn (IEA 2024), underpinning multi-year pipelines. Energy transition and rising water-resilience programs help offset telecom cyclicality, though slowdowns commonly defer discretionary upgrades. A balanced sector mix smooths revenue volatility.
Wage pressures (WPI ~4.1% YoY in early 2025), materials inflation (~6% for construction inputs) and higher fuel (avg ~AUD1.60/L in 2025) have pushed subcontractor costs roughly 5%, compressing Service Stream margins. Indexation clauses and pass-throughs in multi-year contracts are vital to protect margins; efficient procurement and standardisation blunt cost creep. Delays in contract recoveries (commonly 6–12 months) materially erode profitability.
Skilled trades and engineers remain in short supply nationwide, with Australia’s unemployment at 3.7% in June 2024 (ABS) tightening labor availability. Competition from large EPCs and miners has pushed sector wage growth to around 4.0% in 2024 (Wage Price Index), lifting wage expectations. Expanded apprenticeships and retention programs have reduced churn risk, but workforce scarcity can still constrain growth despite strong project pipelines.
Higher interest rates raise bid-bond and equipment finance costs, squeezing margins; long public-contract receivable cycles (commonly 60–120 days) intensify working-capital strain. Milestone structuring and prompt-payment clauses reduce days sales outstanding, and a strong balance sheet underpins bid-bond capacity and lower financing spreads.
Lead times for fiber (8–16 weeks), smart meters (12–24 weeks), switchgear (16–28 weeks) and civils materials (2–8 weeks) materially affect project schedules; average fiber lead-time rose to about 12 weeks in 2024. Diversified suppliers and local sourcing cut disruption risk, while inventory strategies balance availability versus carrying costs. Schedule slippage can trigger liquidated damages commonly 0.1–1.5%/week up to typical caps of 5–10%.
Utility capex (global energy investment US$2.4tn in 2023; clean energy US$1.3tn) underpins multi-year pipelines while wage (WPI ~4.1% early 2025), materials (~6%) and fuel (~AUD1.60/L) pressure margins. Receivables 60–120 days and higher rates raise financing and bonding costs; lead times (fiber 8–16w, meters 12–24w) risk schedule slippage. Contract indexation, milestone payments and supplier diversification are key mitigants.
| Metric | Value |
|---|---|
| Global energy spend 2023 | US$2.4tn |
| Clean energy 2023 | US$1.3tn |
| WPI (early 2025) | ~4.1% |
| Materials inflation | ~6% |
| Fuel (avg 2025) | AUD1.60/L |
| Receivables | 60–120 days |
| Lead time (fiber) | 8–16 weeks |
The Service Stream PESTLE Analysis preview shown here is the exact document you’ll receive after purchase—fully formatted, professionally structured, and ready to use. No placeholders or teasers; the layout, content, and structure are identical to the downloadable file you’ll get immediately upon checkout.
Communities and clients demand zero-harm operations, making visible safety leadership and strong WHS performance key commercial differentiators. Transparent reporting builds trust with utilities and governments and supports bid credibility. Any incident can damage reputation and tender prospects, especially given Australia’s model WHS maximum corporate penalty of up to AU$3 million for Category 1 breaches.
Street works, outages and site access disrupt residents and businesses, and for Service Stream (FY24 revenue A$1.1bn) these impacts affect project timelines and cost-to-serve. Proactive communication and rapid reinstatement measurably reduce complaints and rework, preserving margins. Social license influences council approvals and can add weeks to delivery schedules. Good stakeholder management accelerates delivery and lowers regulatory friction.
Clients increasingly weight diversity metrics—76% of candidates and buyers cite workforce diversity as important and McKinsey (2020) found ethnically diverse companies 36% more likely to outperform—so inclusive hiring/training broadens talent, boosts innovation and retention, while D&I underperformance can materially weaken bid competitiveness and contract awards.
Rapid digital adoption—average Australian mobile data use surpassing 15 GB/month (2024) and a 28% rise in remote work since 2019—sustains telecom upgrades and higher-capacity metering. Smart-home and EV uptake (smart-meter installs up ~20% YoY in 2024) drive increased network and field-service demand; customer expectations for 99.9% reliability tighten SLAs, forcing Service Stream to scale field response to meet these standards.
Community safety expectations, visible WHS leadership and AU$3m max corporate WHS penalty drive operations and tender credibility. Urbanisation and infill (Australia 86% urban, UN 68% by 2050) refocus network investment. Digital demand (15+ GB/mo, smart-meter +20% YoY, remote work +28% since 2019) raises SLA and field-capacity needs.
| Metric | Value |
|---|---|
| Service Stream FY24 revenue | A$1.1bn |
| WHS max penalty (Cat 1) | AU$3m |
| Avg mobile data (AU, 2024) | 15+ GB/mo |
| Remote work change since 2019 | +28% |
| Smart-meter installs YoY (2024) | +20% |
| Australia urbanisation (2023) | 86% |
| UN urban projection | 68% by 2050 |
Next-gen 5G (≈2.3 billion subscriptions in 2024) and accelerating fiber backhaul deployments are driving higher-volume design and rollout work for Service Stream, with fiber CAPEX growth ~8% CAGR through 2028. Edge site rollouts require dedicated power, cooling and secure connectivity, raising per-site OPEX by 15–25%. Multi-tenant and neutral-host models open new service niches, while integration expertise increases win rates by double-digit margins versus standalone bids.
Utilities are rolling out AMI, sensors and IoT grids—global smart meter deployments surpassed 1 billion units by 2024—creating recurring revenue from installation, commissioning and data integration. Interoperability and cybersecurity are critical as utilities face rising OT/IT breaches. Analytics-enabled predictive maintenance can cut downtime ~20–30%, enhancing long‑term service value and upsell opportunities.
Drones with LiDAR now cut survey and inspection times by up to 70% and halve on-site safety incidents, while digital twins have been shown to reduce design clashes and lifecycle costs by roughly 10–20%, improving planning and asset decisions. Field mobility and workflow tools boost crew productivity by 20–30% and shorten close-out times, and increasingly 80%+ of clients expect data-rich, geospatially referenced deliverables as standard.
Critical infrastructure requires robust cyber controls under NIS2 (transposition from 2024) and GDPR, with fines up to €20 million or 4% of global turnover; the average global breach cost was $4.45 million (IBM 2024) and mean time to identify and contain was 277 days, making secure-by-design vendor selection essential. Breaches can trigger contract termination and penalties. Continuous monitoring and compliance auditing, including 24/7 SOCs and regular audits, are essential.
Distributed energy, EV charging and storage are reshaping network topology, driving higher connection works and low-voltage upgrades that present clear growth avenues for Service Stream.
Protection, SCADA and microgrid integration skills are increasingly in demand as DERs proliferate; battery pack prices fell to about 132 USD/kWh in 2023, supporting faster storage rollout.
Standards and interoperability evolve rapidly, requiring ongoing upskilling and CAPEX for compliant connection and commissioning teams.
5G (≈2.3B subs 2024) plus fiber CAPEX ~8% CAGR to 2028 drives rollout demand and higher per-site OPEX (+15–25%). Smart meters >1B units (2024) and DER/EV growth spawn recurring installs and LV upgrades; battery cost ~132 USD/kWh (2023). Drones/LiDAR cut survey time ~70% and digital twins lower lifecycle costs ~10–20%. Cyber risk: avg breach $4.45M, 277 days (IBM 2024).
| Metric | Value |
|---|---|
| 5G subs (2024) | ≈2.3B |
| Fiber CAPEX CAGR | ~8% to 2028 |
| Smart meters (2024) | >1B |
| Battery price (2023) | ~132 USD/kWh |
| Avg breach cost | $4.45M (IBM 2024) |
Strict WHS obligations apply across all states and the chain-of-responsibility extends liability to subcontractors; non-compliance can trigger prosecutions, project stoppages and fines (corporate penalties under model WHS can reach AUD 3 million). Australia recorded 188 workplace fatalities in 2021 and work-related injury/disease costs are estimated at AUD 62.8 billion annually, so strong safety systems materially reduce legal and financial exposure.
Award compliance, enterprise bargaining (covering ~34% of employees) and site agreements drive labour costs and roster flexibility, amplified by the national minimum wage of $882.80/week (from 1 July 2024). Shifts in labour‑hire and gig rules can force model changes and margin pressure. Proactive dispute management preserves service continuity and avoids penalties (up to ~$66,600 per contravention). Robust HR governance enables scalable, compliant growth.
Handling meter and network data triggers Privacy Act and Notifiable Data Breaches obligations in Australia, requiring timely notification and recordkeeping. Breach notification and enforceable security standards carry material compliance risk; the IBM 2024 Cost of a Data Breach Report cites a global average breach cost of US$4.45m. Contractual data clauses with utilities and councils are tightening across tenders. Data minimization and encryption are proven mitigants, often cutting breach impact by up to 40%.
Enhanced obligations under the Security Legislation Amendment (Critical Infrastructure) Act 2021 impose positive security obligations, mandatory incident reporting and supplier vetting on systems of national significance, raising compliance burdens for Service Stream; non-compliance carries statutory penalties and risk of accreditation loss, so investing in governance sustains contract eligibility and resilience.
Works require permits, heritage checks and biodiversity assessments under the EPBC Act and state planning laws.
Approval windows in Australia can span months to over a year, and delays or restrictive conditions can materially increase cost and schedule.
Early engagement and standardized documentation accelerate approvals; non-conformance may trigger remediation orders and penalties under state environmental protection legislation.
WHS duties and chain‑of‑responsibility carry prosecutions, project stoppages and corporate penalties up to AUD 3m; Australia recorded 188 workplace fatalities in 2021 and work‑injury costs ~AUD 62.8bn. Award/EB rules cover ~34% of employees and minimum wage is AUD 882.80/week (from 1 Jul 2024), constraining rostering. Data breaches average US$4.45m (IBM 2024); Critical Infrastructure laws add mandatory reporting and supplier vetting; approvals often take months–>1 year.
| Legal area | Key metric | Impact |
|---|---|---|
| WHS | Penalty AUD 3m; 188 fatalities (2021) | Litigation, stoppages, fines |
| Labour | 34% EB; min wage AUD 882.80/wk | Cost, flexibility |
| Data/Crit Infra | Avg breach US$4.45m; SLA reporting | Contract eligibility, fines |
Floods, fires and heatwaves increasingly disrupt works and assets, with global insured losses from natural catastrophes near $100 billion in 2023, pressuring Service Stream projects. Designs now must embed resilience and redundancy, reflecting utilities’ preference for contingency planning and rapid restoration—driven by Bipartisan Infrastructure Law commitments (about $65 billion for US power resilience). Insurance premiums and outage downtime (industrial losses often $10,000–$100,000+ per hour) materially erode margins.
Government and client net-zero commitments cascade to contractors—Australia targets net-zero by 2050 and a 43% reduction on 2005 levels by 2030 under its NDC. Fleet electrification and low-carbon materials lower scope 1–3 impacts; transport accounted for about 24% of energy-related CO2 emissions in 2022 (IEA). Demonstrable decarbonization improves tender competitiveness, while poor performance risks exclusion from public and private frameworks.
Civil spoil, cable offcuts and meter disposals require compliant handling to meet licensing and EPA obligations; recycling and reuse programs can cut disposal costs and lower embodied carbon. Industry contracts increasingly include KPIs tracking diversion from landfill, commonly aiming for 70–90% diversion, and supply‑chain partnerships enable scaling reuse streams and achieving cost savings through aggregated material recovery.
Drought risk raises client expectations for higher on-site water efficiency and resilient supply planning; about 2 billion people lacked safely managed drinking water services in 2023, driving urgency. Leak detection and smart-water solutions address average non-revenue water losses of roughly 30–40%, creating recurring service and retrofit revenue. Rigorous site practices to limit runoff and contamination are required by regulators, and visible stewardship strengthens relationships with water authorities and contract winning.
Works near sensitive habitats and cultural sites face strict constraints; Natura 2000 sites cover about 18% of EU land and inland waters and UNESCO lists 1,199 World Heritage Sites (2024), so surveys and avoidance plans are essential to secure permits. Non-compliance can halt projects and trigger regulatory enforcement. Early routing and micro-trenching (10–50 mm blades) cut surface impact by up to 90%.
Climate-driven losses (≈$100B insured in 2023) and resilience funding (US BIL ~$65B) force resilient designs and raise insurance/outage costs; net-zero targets (Australia: NZ by 2050; NDC −43% vs 2005 by 2030) drive fleet/material changes affecting tenders; waste diversion targets (70–90%) and water losses (~30–40% NRW) create service opportunities; protected sites (Natura2000 18% EU, UNESCO 1,199 sites 2024) limit routing.
| Metric | Value |
|---|---|
| Insured nat-cat losses 2023 | $100B |
| US power resilience (BIL) | $65B |
| Transport CO2 share (2022) | 24% |
| Waste diversion targets | 70–90% |
| Non-revenue water loss | 30–40% |
| Natura2000 coverage | 18% EU |
| UNESCO sites (2024) | 1,199 |


