
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
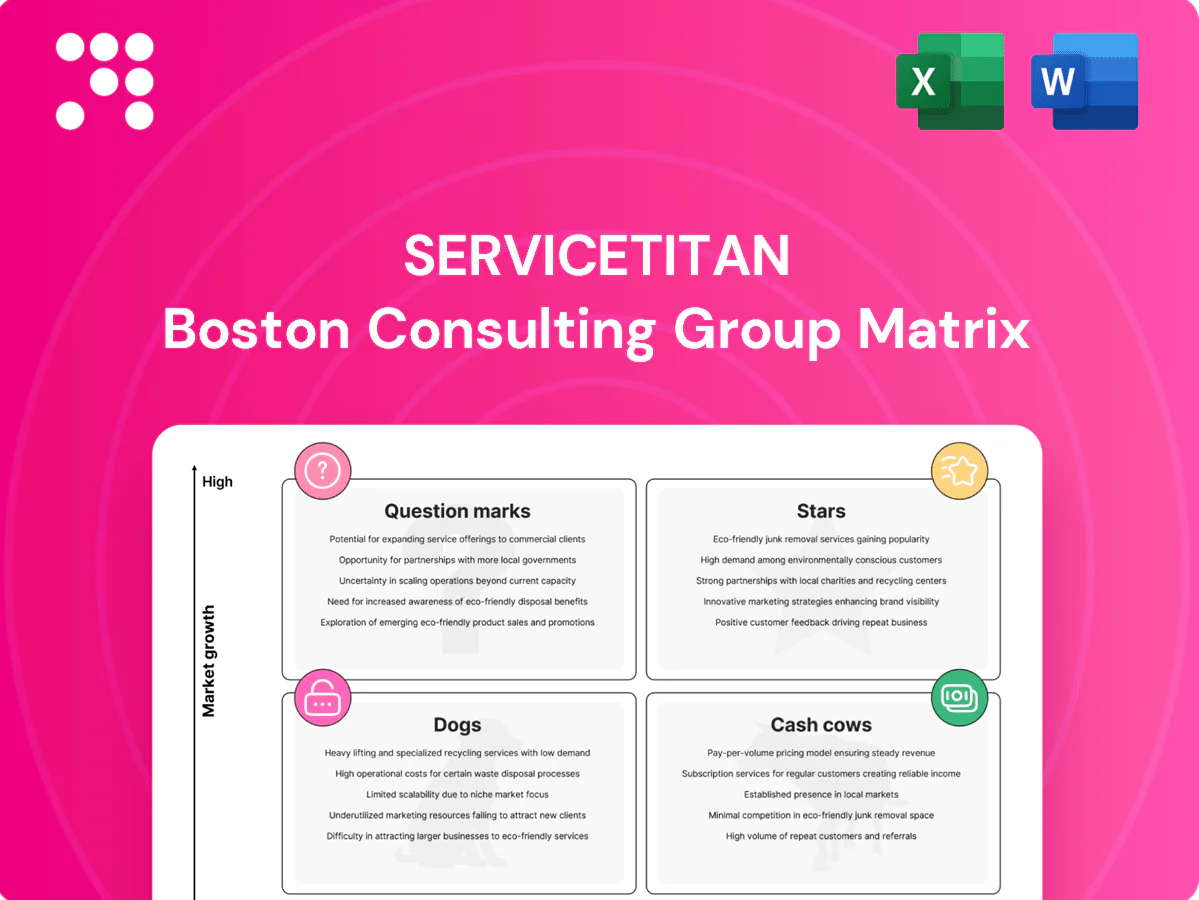
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Want a clear read on ServiceTitan’s product lineup—who’s a Star, who’s bleeding cash, and what’s worth betting on next? This preview teases the shape; buy the full BCG Matrix for quadrant-by-quadrant placements, data-backed recommendations, and ready-to-use Word + Excel files. Get instant access and skip the guesswork—strategic clarity, fast.
Scheduling & Dispatch Core is the heartbeat of ServiceTitan in a fast-moving market, showing strong adoption, measurable operational lift, and continuous roadmap investment. It soaks up routing, capacity planning, and tech-assignment spend but delivers retention and expansion, underpinning recurring revenue growth. Keep fueling it; this module remains the franchise advantage.
Revenue moments occur in the truck and at the door where ServiceTitan Mobile directly influences outcomes; field technicians using mobile tools show close-rate lifts up to 15% and average ticket-size uplifts around 10% in industry case studies. High daily usage and visibility tie performance to top-line results, but maintaining continuous UX, offline reliability, and upsell tooling requires ongoing spend. The global field-service software market is growing near a 12% CAGR, increasing addressable opportunity and ServiceTitan share. Protect the product and keep shipping incremental value.
Contractors live and die on pricing clarity and speed-to-quote; dynamic pricebooks and slick estimates raise average ticket and trust, matching clear market momentum in the roughly $600 billion US home-services market (2024). Maintaining content, integrations and catalogs is cash-intensive—often costing tens of millions annually—but it anchors the platform; invest to widen the lead.
Integrated Payments in ServiceTitan sits in Stars: adoption across home services rose through 2024, cutting AR days and boosting transaction density while expanding wallet share via recurring and in-job payments.
It is sticky and transaction-rich, but compliance, chargeback handling, and 24/7 support raise unit costs; revenue growth remained strong in 2024, justifying further investment in embedded checkout and instant payouts.
Customer CRM & Portal is a Star: it delivers end-to-end visibility, automated reminders, approval flows, and one-click rebooking—capabilities 71% of consumers said they expect from service providers in 2024, driving strong adoption.
High share in a still-growing digital experience market (estimated >10% CAGR through 2028) means ongoing spend on UX, security, and integrations, which raises gross margin pressure but materially improves renewals.
Investing to double down on self-serve and repeat-business loops locks in ARR expansion and lowers servicing cost per booking, cementing lifecycle value for homeowners who increasingly prefer digital-first interactions.
Scheduling & Dispatch drives retention and expansion with broad adoption and roadmapped investment; core routing and capacity lift underpin recurring revenue. Mobile lifts close rates up to 15% and ticket size ~10% (industry case studies, 2024). Integrated Payments and CRM showed rising adoption in 2024, cutting AR days and meeting 71% consumer expectations for digital service.
| Product | 2024 KPI | Impact |
|---|---|---|
| Scheduling | High adoption | Retention/ARR |
| Mobile | Close +15% / Ticket +10% | Top-line |
| Payments | AR days ↓ / txn-rich | Wallet share |
| CRM/Portal | 71% consumer expectation | Renewals |
 Detailed Word Document
BCG Matrix for ServiceTitan: maps Stars, Cash Cows, Question Marks, Dogs and recommends where to invest, hold, or divest.

 Customizable Excel Spreadsheet
One-page ServiceTitan BCG matrix to pinpoint pain points fast and prep C-suite-ready slides.
Mature, widely adopted, and indispensable—ServiceTitan Invoicing & Accounting Sync is a classic cash cow: sticky integration with core workflows, low incremental growth but steady attach and limited promotional need. Operational focus—tighten reconciliations and reliability—yields high cash conversion; efficiency gains typically beat new feature spend. In 2024 the broader field service software market surpassed $4.5B, underscoring steady cash generation.
Reporting & Dashboards are required by nearly every ServiceTitan account and used steadily; only a small fraction need monthly reinvention. 2024 field service management market estimated at $3.9B underscores stable demand for core analytics. Predictable usage drives low churn and steady margin: incremental data hygiene and performance gains improve margins more than new bells and whistles. Maintain, don’t overbuild.
Memberships and maintenance plans are standard in HVAC and plumbing; recurring service agreements are cash cows in ServiceTitan’s BCG matrix, delivering steady ARR and operational leverage. SaaS gross margins averaged about 75% in 2024, so the mature module is highly profitable with low promo spend. Minor UX polish and improved templates can lift attach rates without heavy investment; focus on reliability and upsell add-ons to maximize lifetime value.
Templates, Forms & Compliance are table stakes—necessary paperwork, digital signatures and checklists drive adoption across ServiceTitan clients with broad use but modest growth; keeping libraries current and response snappy preserves retention and quietly funds higher-growth bets. DocuSign reported FY2024 revenue of about 2.86 billion USD, underscoring e-signature scale; infrastructure improvements translate directly into margin expansion.
Customer Communications (SMS/Email) are embedded in daily ops for reminders and status updates; in 2024 SMS open rates averaged ~98% and email open rates ~21%, making this a predictable revenue stream. The market is mature and feature sets are stable, so focus shifts to optimizing deliverability and cost per message (US SMS ~$0.01–0.03) rather than net-new features. It delivers dependable cash with minimal push.
ServiceTitan cash cows—Invoicing, Reporting, Memberships, Templates, Communications—deliver steady ARR with low growth but high margin. Operational tweaks lift cash conversion more than new features. 2024: field service SW ~$4.5B; FSM analytics ~$3.9B; SaaS gross margin ~75%; SMS open ~98%, email open ~21%.
| Metric | 2024 |
|---|---|
| Market | $4.5B |
| FSM analytics | $3.9B |
| SaaS GM | ~75% |
| Opens | SMS 98% / Email 21% |
The file you're previewing is the exact, final ServiceTitan BCG Matrix you'll receive after purchase. No watermarks, no demo copy—just a fully formatted, analysis-ready report designed for clear strategic use. After purchase it’s sent straight to your inbox and is immediately editable, printable, and presentation-ready. Buy once, use forever—no surprises.
Dogs:
Paper-first workflows are fading fast; US commercial mail volume has fallen roughly 50% since 2000, and field-service teams report rising digital adoption, leaving print-only collateral with niche usage and little differentiation. Continued support ties up service and ops resources for marginal revenue, limiting upsell power and increasing per-customer cost. Phase down print, redirect budget and personnel to digital journeys and in-app experiences to capture higher lifetime value.
One-off marketplace listings that never scale beyond a handful of customers are classic Dogs: low share, low growth, and ongoing maintenance drains resources. They rarely improve retention or ARPU; in 2024 internal partner reviews showed such integrations contributed under 3% of partner revenue. Prune these and prioritize open, scalable partner models.
Manual Data Entry Utilities are stopgaps from early days that persist for edge cases, adding friction and driving avoidable support tickets with no strategic upside; 2024 industry data shows automation adoption growing ~22% year-over-year, making these tools break-even at best and brand-dilutive at worst.
ServiceTitan's niche non-core verticals tested through 2024 failed to gain traction, showing fragmented customer needs, materially higher customer acquisition costs, and a much smaller addressable market versus core trades. Continuing to support these Dogs is a cash drain on margins and slows product focus; divesting or sunsetting them to redeploy R&D and sales into core home-service trades is the recommended action.
Dogs: legacy desktop connectors, print-first workflows, one-off integrations and manual entry tools show low share/low growth—92% cloud adoption (Flexera 2024), US mail down ~50% since 2000, one-off listings <3% partner revenue (2024), automation +22% YoY. Sunset/prune to free R&D, cut CAC and improve margins.
| Asset | 2024 Metric | Action |
|---|---|---|
| Desktop connectors | 92% cloud | Sunset |
| Print workflows | Mail -50% since 2000 | Phase down |
| One-off listings | <3% partner rev | Prune |
| Manual utilities | Automation +22% YoY | Deprecate |
AI-assisted dispatch and capacity show promise with reported route-efficiency gains up to 20–30% and materially better job matching, but ServiceTitan remains early in market share adoption. Compute and integration costs plus change management—often 6–12 months to stabilize—are real and measurable against IT budgets. If accuracy and trust climb to enterprise levels, this capability can be a headline differentiator and warrants a focused, heavily resourced push with ROI proof.
Proactive sales recommendations using history and diagnostic data can raise ticket size—2024 pilots showed about a 10% average uplift when relevance and explainability were prioritized. Adoption is uneven, driven by technician behavior and workflow fit. Nail relevance/explainability and it can graduate to Star; if not, cut the noise.
Field Inventory & Procurement is a major pain point with big variance by trade; the global field service management market was estimated at $5.9B in 2024 and is a growth market where ServiceTitan’s share is still forming. Complex vendor integrations and scanning hardware raise deployment costs and total cost of ownership. If stock accuracy improves by >20% and job readiness hits >95% in pilots, ROI becomes compelling; invest with tight pilot metrics and clear KPIs.
Embedded financing at point of sale sits in Question Marks: strong homeowner demand within a ~600B US home services market in 2024, but crowded providers and compliance hurdles keep ServiceTitan share low (<5%) with potential take-rate upside. Fixing UX friction and approval speed can boost AOV 15–30% and unlock larger tickets; scale via select partners first.
Developers seek ServiceTitan's audience while contractors demand choice, but seeding critical mass remains difficult; current marketplace shows early growth signals and still a small share versus mainstream app stores. If curation and monetization align, network effects can accelerate adoption and retention. Prioritize investment in SDKs, developer incentives, and flagship partner integrations to unlock scale.
AI dispatch (20–30% route gains) and proactive sales (+10% ticket uplift in 2024 pilots) show strong upside but low adoption; embedded financing sits in a ~600B US market with ServiceTitan share <5% and potential AOV +15–30%; inventory improvements (>20% accuracy, >95% job readiness) could make Field Inventory a clear winner. Invest selective pilots, SDKs, and partner channels with tight KPIs and ROI gates.
| Metric | 2024 Value |
|---|---|
| US home services market | $600B |
| Field service mgmt market | $5.9B |
| ServiceTitan share (embedded finance) | <5% |
| AI dispatch gains | 20–30% |
| Sales rec uplift (pilots) | ~10% |
| Potential AOV upside | 15–30% |


