
Digital download
Access the files immediately after checkout.
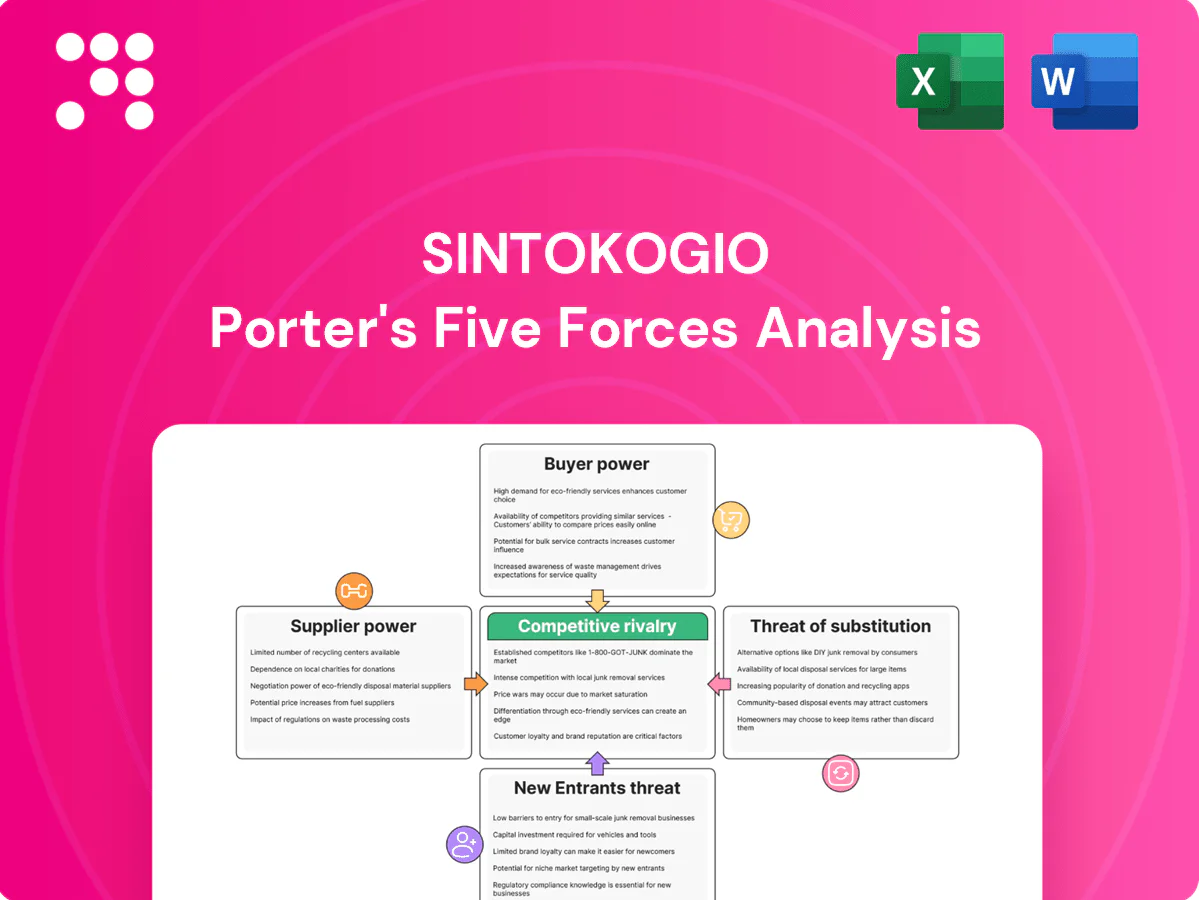
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Sintokogio faces moderate buyer power, concentrated suppliers for specialized components, and steady rivalry driven by precision engineering and cost pressures; barriers to entry are modest but technical know‑how raises the bar, while substitutes remain limited. This brief snapshot only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore Sintokogio’s competitive dynamics, market pressures, and strategic advantages in detail.
Controls, sensors, PLCs and high-spec motors are concentrated among a few global suppliers, with the top vendors accounting for roughly 60–70% of industrial automation revenue in 2024. This concentration raises switching costs and keeps lead times elevated (commonly 8–16 weeks in 2024), increasing project timing risk. Long-term framework agreements can dampen annual price swings (historically up to ~15%) but do not remove supply concentration. Design-for-multi-vendor architectures materially rebalance supplier power by lowering single-supplier dependency.
Heavy steel, castings and precision fabrications are core inputs for Sintokogio and face cyclical price swings; global crude steel production in 2024 exceeded 1.8 billion tonnes, reflecting tight supply-demand pockets. When capacity tightens, mills and foundries can exert pricing pressure and widen lead times. Qualifying alternate fabs typically takes over 12 months due to quality and safety validation. Hedging and multi-region sourcing materially reduce exposure to spot volatility.
Shot/grit media and filter bags/cartridges are recurring, quality-sensitive inputs that can drive 10–25% of maintenance OPEX; premium grades from a concentrated supplier base often command price premiums of 20–30%, boosting supplier margins. Volume bundling across Sintokogio’s installed base secures discounts and service terms, while private-label alternatives (testing cycles typically 6–12 months) provide leverage but require validation.
Long, global supply chains for Sintokogio raise freight and schedule risk, with critical-path assemblies vulnerable to port congestion or export controls that in 2024 still caused multi-week delays in major hubs. Supplier delivery performance directly affects project cash flow through extended payment cycles and higher WIP; many OEMs reported rising buffer inventory levels to offset volatility. Regionalization and local stocking reduced supplier leverage by shortening lead times and improving predictability.
Clear IP ownership clauses and standardized interfaces mitigate risk; adopting modular architectures has been shown in 2024 pilots to restore up to 25% of negotiation flexibility within 2–3 product cycles.
Supplier concentration (automation 60–70% of revenue in 2024) raises switching costs and keeps lead times at 8–16 weeks, increasing project timing risk. Crude steel >1.8bn t (2024) fuels cyclical input pricing; qualifying fabs >12 months. Regional sourcing, buffers and modular design (2024 pilots: ~25% regained negotiation flexibility) materially reduce supplier power.
| Metric | 2024 | Impact |
|---|---|---|
| Automation conc. | 60–70% | High switching cost |
| Lead time | 8–16 wks | Timing risk |
| Crude steel | >1.8bn t | Cyclical prices |
| Modularity | ~25% | Negotiation flexibility |
 Detailed Word Document
Uncovers competitive drivers, supplier and buyer power, entry barriers, substitutes, and rivalry shaping Sintokogio’s market position, offering strategic insights on disruptive threats and protective dynamics.

 Customizable Excel Spreadsheet
One-sheet Porter's Five Forces for Sintokogio—clear visual scores and a spider chart to instantly reveal strategic pressures and relieve analysis bottlenecks.
Concentrated OEM buyers in automotive, aerospace and tiered manufacturing buy in sizable, infrequent lots—global light‑vehicle production was roughly 80 million units in 2024, concentrating spend with major OEMs—and use professional procurement teams to run competitive RFQs that extract price concessions. Volume and reference contracts give buyers leverage, while suppliers that can demonstrate measurable throughput and quality gains (reduced defects, faster cycle times) can defend pricing and secure long‑term slots.
Installed-base compatibility, operator training and facility layout create high switching barriers, with aftermarket parts and service often representing over 30% of vendor revenue in industrial equipment (2024 industry averages). Buyers still benchmark vendors to pressure service and parts pricing; lifecycle performance data can boost loyalty, while open interfaces lower perceived lock-in.
Customers now assess total cost of ownership across energy use, media consumption, downtime and maintenance, and in 2024 TCO evidence increasingly dictates procurement decisions. When measurable TCO advantages are clear, price sensitivity falls and buyers accept premiums tied to performance guarantees and uptime SLAs. Digital monitoring that documents savings and reduced downtime materially weakens buyer bargaining power.
Complex, tailored systems enable value-based pricing but typically extend sales cycles and increase negotiation scope, while buyer-driven design demands can shift integration and validation costs to Sintokogio, squeezing margins. Standard option kits help cap cost creep and streamline approvals; application labs and on-site trials reduce perceived risk and limit discount pressure by validating performance before purchase.
Concentrated OEM buyers (global light‑vehicle production ~80m units in 2024) exert strong price pressure via RFQs, but demonstrated TCO and uptime reduce sensitivity. Aftermarket/service often >30% of vendor revenue, keeping switching costs high when spare availability and <24h response are delivered. Multi‑year (3–5y) contracts trade price for revenue stability.
| Metric | 2024 |
|---|---|
| Light‑vehicle output | ~80m units |
| Aftermarket share | >30% |
| Service SLAs | <24h response |
| Contract length | 3–5 years |
This preview shows the exact Sintokogio Porter's Five Forces Analysis you'll receive immediately after purchase—no surprises or placeholders. The document displayed here is fully formatted, professionally written, and ready for immediate download and use. Once you buy, you'll get instant access to this same file.
Established peers include DISA/Wheelabrator (Norican), Rösler and others in molding/surface treatment, and Donaldson, Camfil and Nederman in dust collection; 2024 revenues among these firms span from several hundred million to over 3 billion USD, reflecting scale gaps. Rivalry is intense on performance, reliability and global service reach, with brand, customer references and installed base serving as primary differentiators.
Large-capex projects trigger head-to-head tenders, typically for contracts often exceeding $50m, driving intense price competition and bid frequency.
Price transparency from e-procurement (used in about 70% of public tenders by 2024) compresses margins and forces aggressive cost-downs.
Demonstrations, trials and rigorous ROI models become decisive tie-breakers, with buyers demanding payback analyses over 3–5 years.
Bundling equipment with long-term service contracts shifts outcomes toward suppliers offering lifecycle value, lifting deal win rates despite slimmer upfront margins.
IoT monitoring, process control and automation software are active battlegrounds as vendors invest in IIoT: analytics that can cut media use and energy by up to 15% differentiate offers. Rivals fast-follow features, compressing product lifecycles and raising table stakes for release cadence and R&D spend. Open APIs and retrofit kits defend the installed base, enabling legacy upgrades and reducing churn.
Aftermarket rivalry for Sintokogio extends beyond parts to upgrades and rapid field service, with 2024 market dynamics pushing faster response times as customers demand higher uptime. Multi-year service contracts stabilize share but trigger aggressive price matching by competitors, while proximity of service hubs frequently determines final deal awards.
Lower-cost entrants from China and India often undercut Sintokogio by roughly 20–40% on standard machines, intensifying price rivalry; however, local certification and after-sales support still limit their penetration in regulated sectors like automotive and medical. Hybrid strategies—premium cores with cost-optimized modules—preserve margins, while export finance and local assembly can cut landed costs by up to 10–15%.
Rivalry is intense among incumbents (revenues several hundred million to >3bn USD) and low-cost China/India players undercutting 20–40%. Large-capex tenders (>50m USD) and 70% e-procurement by 2024 heighten price pressure. IIoT/features (up to 15% energy/media savings) and service hubs decide wins, with multi-year contracts stabilizing share but compressing margins.
Additive manufacturing and near‑net‑shape forming can cut casting volumes, as the industrial 3D printing market reached about $15.8B in 2024, with increasing metal AM use in aerospace and tooling. Precision machining and peening alternatives are replacing shot blasting in niche aerospace and medical segments. Adoption remains limited by cost, throughput and material properties, so monitoring these shifts supports timely portfolio pivots.
C hemical deburring, acid pickling and thermal treatments increasingly substitute mechanical blasting where surface specs allow, offering faster cycle times and lower manual labor. Acid pickling produces hazardous spent acids regulated under RCRA, raising waste-handling costs and permitting burdens. Buyers often switch for convenience or cost differentials, while eco-friendly media and closed-loop systems recovering ~95% of abrasives help Sintokogio defend market share.
Third-party finishing and foundry services, with the global foundry market exceeding $120 billion in 2024, can substitute in-house equipment purchases by converting capex to opex and lowering customers technical burden. Large, high-volume production runs or IP-sensitive parts still favor in-house lines to protect margins and know-how. Emerging pay-per-use and equipment-as-a-service models offer an on-premise alternative that can blunt outsourcing appeal.
Robotic grinding, high-pressure waterjet, and laser texturing can substitute 일부 blasting tasks; laser/texturing offers 10–50 μm accuracy and programmable repeatability for complex geometries. High capex (robotic cell $150k–$500k) and material/porosity limits for waterjet restrict broad substitution. Integrating robots with blasting keeps Sintokogio competitive and can cut cycle times ~20–40%.
Additive manufacturing ($15.8B market, 2024) and third‑party foundries ($120B, 2024) pose material substitution and outsourcing risk, while chemical and wet systems compete on speed and cost; HEPA removes 99.97% (0.3 μm). High robotic capex ($150k–$500k) and AM throughput/material limits restrain rapid share loss.
| Substitute | 2024 metric | Impact |
|---|---|---|
| Additive manufacturing | $15.8B | Medium—material/throughput limits |
| Foundry/outsourcing | $120B | High—capex→opex shift |
| Filtration/Wet scrubbers | HEPA 99.97% | Low/Medium—regulatory tradeoffs |
| Robotics/laser | $150k–$500k/cell | Medium—capex barrier |
Design, testing and demo facilities demand heavy upfront capital—advanced pilot lines often require tens to hundreds of millions of dollars—raising barriers to entry. Long cash cycles (receivables and commissioning phases often exceed 6–12 months) and warranty liabilities (commonly 1–3% of sales) deter newcomers. Economies of scale in fabrication and global service networks cut unit costs, while captive financing programs and sizeable installed-base references further raise entry hurdles.
Application know-how, stringent safety standards and 2024 environmental compliance requirements make engineering and certification demanding; regional approvals typically take 12–24 months. Costly failures favor proven vendors, with industrial recalls often exceeding $5M in direct costs. Cross-border certification complexity raises entry costs and deep technical knowledge creates a durable moat.
24/7 support, spare-parts logistics and commissioning talent are essential for Sintokogio to ensure uptime and warranty compliance; building that service network typically requires 12–24 months and multi‑million-dollar investment. Without it, entrants face credibility gaps with buyers and higher churn. Partnerships with local integrators can bridge coverage shortfalls but rarely replace full capacity or proprietary expertise.
Software and IoT commoditization (IIoT market ~USD 106B in 2024) narrows product differentiation, yet embedding analytics into process control still demands deep domain expertise and legacy-systems know‑how; cybersecurity and data‑ownership issues (cybersecurity market ~USD 207B in 2024) raise trust barriers, while proven outcomes data remains a strict gatekeeper for entrants.
High upfront capex (pilot lines tens–hundreds of millions), long cash cycles (6–12+ months) and warranty risks create steep entry costs.
Scale, global service networks and supplier volume history (2–5y) yield 10–25% price premiums and 6–12m lead‑time penalties for entrants.
IIoT market ~USD 106B (2024) and cybersecurity ~USD 207B (2024) compress differentiation but deep domain trust and proven outcomes remain gatekeepers.
| Metric | Value |
|---|---|
| Capex | tens–hundreds $M |
| Price premium | 10–25% |
| Lead‑time penalty | 6–12 months |
| IIoT / Cyber | $106B / $207B (2024) |


