
Digital download
Access the files immediately after checkout.
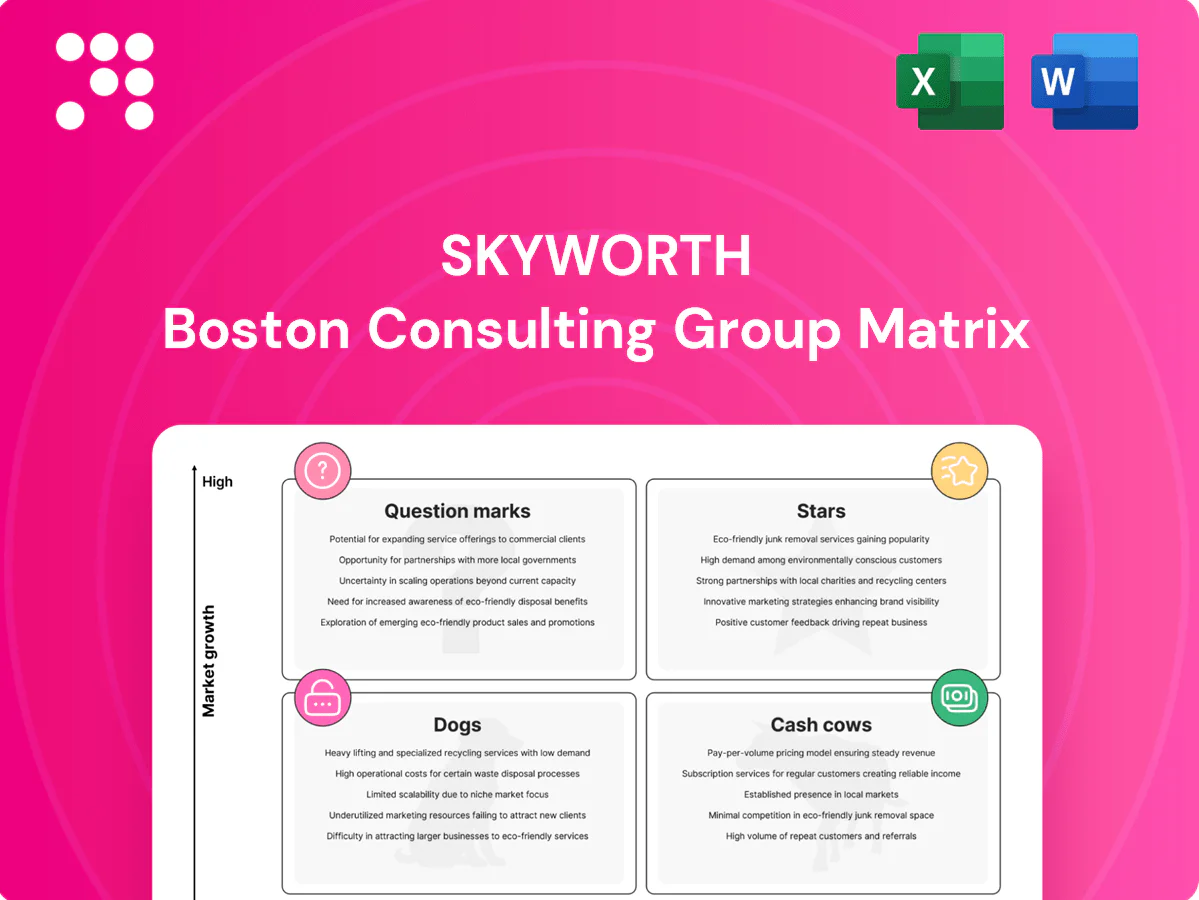
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Skyworth’s products sit—Stars, Cash Cows, Dogs, or Question Marks? This snapshot teases the shifts in market share and growth, but the full BCG Matrix gives the quadrant-by-quadrant clarity you need to act. Purchase the complete report for detailed placements, data-backed recommendations, and ready-to-use Word and Excel files that save you hours. Get instant access and start steering investment and product decisions with confidence.
Flagship MiniLED/OLED smart TVs sit in a fast-growing premium segment and Skyworth holds meaningful domestic share, buoyed by strong picture tech and Google TV/Android TV integration that keeps the brand in consideration. These models require heavy promo spend but deliver measurable brand lift and price resilience, so continued investment can convert them into future cash cows.
Global demand for streaming-first 4K Android/Google TVs continues climbing, and Skyworth, ranked among the top five global TV vendors (Omdia 2023), ships at scale to capture that growth. Broad app ecosystems and smooth UX on Android TV accelerate replacement cycles and lifetime monetization. Distribution wins matter—prioritize retail visibility and bundled services to defend shelf share. Hold share and ride the growth curve.
Console and PC gaming demand has pushed HDMI 2.1, 120Hz TVs into a high-growth pocket as the global games market exceeded $200 billion in 2023, boosting premium display demand. Skyworth’s early spec leadership (HDMI 2.1, VRR, low latency) lets it punch above weight and capture higher ASPs. Success requires steady engagement with gamer communities and influencers to convert enthusiasts. High-volume growth now should translate into margin-rich returns as scale and software partnerships deepen.
Coocaa, Skyworths internet-TV brand, builds users, first-party data and recurring ad/content revenue, positioning it as a Star in the BCG Matrix; engagement reportedly outpaces the broader TV market, driving higher CPMs and ARPU expansion. Scale in ad-tech and content partnerships enables monetization across ads and subscriptions, and with continued user growth it is maturing into a dependable earner by 2024.
Premium big-screen 8K/ultra-large demand expanded in 2024 across China and parts of North America, driven by premium living-room upgrades and showroom-led purchases. Skyworth’s 8K and ultra-large portfolio gives it a credible seat at the table versus Samsung and LG, supporting premium ASPs. High price points mean promotions and immersive showroom presence are critical to convert consideration. Win mindshare now, milk later through service and upsell.
Skyworth Stars (flagship MiniLED/OLED, gaming 120Hz, Coocaa, 8K) occupy high-growth premium pockets with domestic share strength and top-5 global scale (Omdia 2023); heavy promo spend and showroom investment required but convertable to cash cows as ASPs and service revenues rise. Coocaa drives recurring ad/sub revenue and 2024 engagement outpaces the TV market. Prioritize distribution, gamer/community engagement, and ad-tech scale.
| Tag | 2023/24 Data |
|---|---|
| Global rank | Top 5 (Omdia 2023) |
| Games market | >$200B (2023) |
| Coocaa trend | Engagement > TV market (2024) |
| Premium growth | 75+/85+ fastest in select markets (2024) |
 Detailed Word Document
Concise BCG analysis of Skyworth products with strategic moves for Stars, Cash Cows, Question Marks and Dogs.

 Customizable Excel Spreadsheet
One-page Skyworth BCG Matrix placing units by potential, easing resource decisions and exec-level clarity.
In 2024 Skyworth’s mass-market 4K/LCD TV segment remained a mature core category with a solid market share, generating consistent volume and margin. High unit throughput and an efficient supply chain keep channel margins stable and free cash flow strong. Limited need for heavy promotion beyond seasonal pushes preserves profitability. Management funnels surplus cash into adjacent growth bets and R&D for premium and smart-TV features.
OEM/ODM TV manufacturing yields steady repeat orders from retailers and brands in a low-growth market where global TV shipments hovered around 190–200 million units in 2023–24, delivering predictable cash flow and limited demand volatility. Skyworth scale and manufacturing know-how drive cost advantages via high utilization and procurement leverage, supporting gross-margin resilience. Capex remains modest relative to revenue, allowing free cash generation if line efficiency stays above benchmark rates and contracts remain sticky.
Set-top boxes for pay-TV operators sit in Skyworth’s cash-cow quadrant: category maturity with stable operator contracts sustaining volumes (global pay-TV subs ~900 million in 2024), engineering reuse trims unit costs and preserves gross margins, and the product line remains cash-positive despite gradual cord-cutting (~annual subscriber declines of low single digits). Maintain support SLAs and harvest cash while deferring heavy R&D.
Room air conditioners (mainline) are cash cows for Skyworth in 2024: demand remains stable across core geographies, supported by consistent replacement cycles. Skyworth competes on price-performance and dense distribution, while incremental efficiency upgrades in models raise margins and lower operating cost per unit. Low promotional intensity preserves reliable cash generation.
Mid-range refrigerators and washers are mature, replacement-driven cash cows for Skyworth with broad retail reach and stable sell-through; operations and sourcing sustain dependable gross margins, supporting steady EBITDA contribution. Marketing spend is light, prioritizing availability and after-sales service to maximize lifetime value. They provide a reliable funding reservoir for adjacent R&D and premium product development.
Skyworth cash cows in 2024—4K/LCD TVs, OEM TV lines, set-top boxes, room ACs, mid-range fridges/washers—delivered steady margins and free cash flow; global TV shipments ~190–200M, pay-TV subs ~900M, modest capex, high utilization and low promo sustain profitability and fund adjacent R&D.
| Asset | 2024 metric | role |
|---|---|---|
| 4K/LCD TVs | 190–200M global ship. | cash |
| Set-top boxes | ~900M subs | cash |
The Skyworth BCG Matrix you're previewing is the exact file you'll receive after purchase. No watermarks, demo placeholders, or surprise edits — just a fully formatted strategic report ready for use. Crafted for clarity and decision-making, the final document is immediately downloadable and editable for presentations or internal planning. Buy once, get the complete, market-informed BCG Matrix—simple, professional, done.
Legacy 3D/plasma TV lines face a flat-to-declining market with virtually no retail demand and minimal buyer interest. Skyworth’s share in this segment is negligible and aging inventory creates real balance-sheet and working-capital risk. Industry signals through 2024 (no major manufacturers promoting 3D/plasma at CES 2024) show turnarounds unlikely to recoup investment. Recommend exit and redeploy capital to growth segments.
Non-smart entry-level TVs face rapid decline as smart models exceeded over 80% of global shipments by 2023 (Omdia), pushing the legacy category into contraction. Intense price wars have compressed margins and erased differentiation; Skyworth’s non-smart lines show low share, low growth and minimal brand value. Recommend winding down SKUs and routing remaining stock through closeouts and clearance channels.
Streaming decimated standalone DVD/Blu‑ray growth; global player shipments have fallen over 90% from peak years and now trickle in with single‑digit million annual units, margins are razor‑thin and support costs persist, tying up cash in slow‑moving inventory and warranty liabilities; recommend divestment or licensing the lineup to a specialist to stop cash burn.
Commodity home security kits sit in Dogs: highly fragmented market with race-to-the-bottom pricing; the global DIY home security segment was about US$6.5bn in 2024, with top five vendors holding under 30% share, making shelf space and mindshare expensive to win.
Low marketing and R&D ROI (gross margins often below 25%) suggests Skyworth should scale back to B2B niches or exit commoditized SKUs.
Legacy DVB-only converter boxes sit in the Dogs quadrant: most national digital switchover cycles completed (EU ~2012–2013, many APAC/LatAm markets by late 2010s), so replacement demand in 2024 is tiny and sporadic, with units now typically in low thousands per market annually; Skyworth holds minimal share and no strategic upside, recommend discontinue and limit to servicing residuals.
Multiple legacy SKUs (3D/plasma, non‑smart TVs, DVD/Blu‑ray, DVB boxes, commodity DIY security) are low‑share, low‑growth Dogs in 2024: non‑smart TVs <20% shipments (post‑2023 Omdia), DIY security ≈US$6.5bn (2024) with top5 <30%, DVD players down >90% from peak; margins often <25%. Recommend exit or shift to B2B/licensing and clear inventory to free working capital.
| Segment | 2024 status | Share | Margin | Action |
|---|---|---|---|---|
| 3D/plasma | Declining | Negligible | <25% | Exit |
| Non‑smart TV | Contracting | <20% | <25% | Phase out |
| DVD/Blu‑ray | Post‑peak | Single digits | <25% | Divest/license |
| DIY security | Fragmented | Top5 <30% | <25% | Scale back/B2B |
| DVB boxes | Replacement only | Minimal | <25% | Discontinue |
Automotive cockpit displays sit in a high-growth segment—the global cockpit/display market was about $30 billion in 2024 with roughly 8% CAGR—yet Skyworth’s auto share remains small, under 5% of its product mix. Design wins require long sales cycles and OEM trust; securing Tier-1 partnerships and achieving ISO/auto-grade quality are prerequisites. Winning 2–3 major platform programs can flip this Question Mark into a Star within 2–4 years.
Commercial/interactive displays sit in Question Marks: digital signage, education and meeting-room segments are expanding—global digital signage market ~USD 23B in 2024 with ~8% CAGR; procurement-driven channels keep share thin. Skyworth should bundle hardware with software/services to lift attach rates; if attach rates climb quickly, scale aggressively; if not, prune investments.
Connected fridges, washers and ACs are in a high-growth AIoT segment with industry forecasts around a 13% CAGR through 2028, and 2024 saw double-digit unit growth for smart appliances in key markets. Skyworth’s AIoT footprint is expanding across China and SEA but remains non-dominant versus incumbents. Prioritize energy management, cleaner app UX and broad interoperability to win consumers. Either accelerate share gains quickly or re-scope SKUs for margin clarity.
AI analytics are driving category growth but incumbents (Hanwha, Hikvision) still hold leading share; the global video surveillance market was roughly $45B in 2024, with AI analytics segments growing fastest. Technology development and certifications (ONVIF, CE, local approvals) demand high cash burn and long sales cycles. Target verticals where Skyworth can bundle displays+security (retail, hospitality, transportation) to win. Prove traction in pilots, then scale.
Overseas premium appliance push sits in Question Marks: growth markets (Europe/SEA premium segments grew ~6% in 2024) but Skyworth brand equity varies by region, requiring heavy early marketing and channel incentives that burn cash. Focus must be on hero SKUs and service reliability; if velocity sustains 20%+ gross margin scale, otherwise pivot to narrower markets or licensing.
Skyworth’s Question Marks span high-growth pockets: cockpit displays (global $30B 2024, ~8% CAGR; Skyworth <5% mix), digital signage ($23B 2024, ~8% CAGR), AIoT appliances (~13% CAGR to 2028) and AI analytics (video market ~$45B 2024). Win platform design wins, attach-rate lift or bundle services fast; otherwise reallocate capital within 2–4 years.
| Segment | 2024 Market | CAGR | Skyworth position | Decision rule |
|---|---|---|---|---|
| Cockpit | $30B | ~8% | <5% mix | Win 2–3 platforms |
| Digital signage | $23B | ~8% | Low share | Bundle SW/Svc or prune |
| AIoT appliances | — | ~13% | Growing | Prioritize energy/UX |


