
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
STAG Industrial shows resilient cash flows from a diversified single-tenant industrial portfolio, but faces interest-rate sensitivity and competition for logistics space. Our full SWOT analysis dissects market positioning, financial drivers, and risk mitigants. Purchase the complete report (Word + Excel) for editable, research-backed insights to inform investment or strategy.
Specialization in single-tenant industrial assets lets STAG apply disciplined underwriting and operating playbooks tailored to warehousing, distribution and light manufacturing, driving better acquisition pricing, tenant fit and asset-level optimization. This consistency supports stable cash flows aligned with REIT investor expectations and positions the platform to capture e-commerce logistics demand as U.S. e-commerce reached about 16.2% of retail sales in 2023.
Diversified U.S. footprint across 40+ industrial markets reduces exposure to localized shocks, smoothing rent-growth cycles and supply pipelines. Geographic depth lets tenants relocate or expand within the portfolio, supporting retention and lowering downtime. Scale across markets enhances negotiation leverage with vendors and tenants, improving cost and leasing terms.
Net long-term net leases shift many operating expenses to tenants, stabilizing STAG Industrials cash flows and protecting margins. Longer average lease terms cut turnover frequency and downtime risk across its 550+ building, ~99 million rentable SF portfolio with ~97% occupancy. Predictable rent escalators support steady same-store NOI growth and align with income-focused investors seeking durability.
STAG Industrial’s portfolio targets tenants in online retail, omnichannel fulfillment, and inventory rebalancing, positioning assets to capture demand driven by faster delivery expectations and last-mile needs. Structural supply-chain shifts and reshoring trends support sustained occupancy and rental resilience. Management explicitly aligns acquisitions and lease strategy to harness these secular e-commerce tailwinds for long-term appreciation.
STAG's repeatable acquisition platform enables disciplined deployment into accretive deals across a portfolio of over 575 industrial properties and ~100 million rentable sq ft (2024). Access to capital markets supports scaling when spreads are attractive. Integration capabilities and portfolio rotation lift yields through leasing, light value-add and improved average lease metrics.
Specialist in single-tenant industrials with disciplined underwriting drives stable cash flow and capture of e-commerce logistics demand (U.S. e-commerce ~16.2% of retail sales in 2023). Diversified 40+ market footprint and ~97% occupancy across ~575 properties (~100M RSF, 2024) reduces localized risk and improves tenant retention. Net long-term leases shift expenses to tenants, supporting predictable same-store NOI and yield stability.
| Metric | Value |
|---|---|
| Properties (2024) | ~575 |
| Rentable SF (2024) | ~100M |
| Occupancy | ~97% |
 Detailed Word Document
Provides a concise SWOT overview of STAG Industrial’s internal strengths and weaknesses alongside external opportunities and threats shaping its industrial REIT strategy.

 Customizable Excel Spreadsheet
Condenses STAG Industrial’s strengths, weaknesses, opportunities and threats into a clear, visual SWOT matrix for fast strategic alignment and quick investor or stakeholder briefings.
Single-tenant assets carry binary occupancy risk: a vacancy wipes out 100% of that asset’s rental revenue, concentrating cash-flow exposure. Re-leasing often requires substantial time and tenant-improvement capital, and credit or operational issues at a single occupant can materially curtail distributions. This concentration elevates underwriting and asset-management complexity versus multi-tenant peers and has driven STAG to target high occupancy levels (above 95% in recent filings) to mitigate risk.
As a REIT, STAG's valuation and acquisition spreads are sensitive to interest rates: with the fed funds target near 5.25–5.50% and the 10-year Treasury around 4.2% (mid‑2025), rising rates pressure cap rates and FFO multiples, tighten debt service coverage, make refinancing costlier—compressing accretion from external growth—and rate volatility complicates capital planning and deal pacing.
STAG Industrial relies heavily on issuing equity and debt to fund acquisitions, and with a market cap near $4.5B (July 2025) share-price weakness can stall accretive external growth. Dislocated markets in 2022–24 pushed borrowing costs higher and can make capital scarce, limiting agility during attractive buying windows. This dependence constrains rapid portfolio expansion when opportunities arise.
Exposure to secondary markets leaves STAG facing thinner tenant pools and longer re-leasing timelines; STAG held 548 properties totaling about 114 million rentable square feet as of 12/31/2024, increasing backfill risk versus top-tier hubs. Disposition liquidity can be weaker, pressuring exit pricing, and lease-up operating costs per property tend to be higher.
Single-tenant concentration creates binary vacancy risk and higher re-leasing/TI costs, forcing underwriting rigor to maintain occupancy above ~95%. Rate sensitivity (fed funds 5.25–5.50%, 10yr ~4.2% mid‑2025) raises refinancing and cap‑rate pressure, compressing FFO multiples. Scale and secondary‑market exposure (548 properties, 114M RSF) limit pricing power vs mega‑caps.
| Metric | Value |
|---|---|
| Market cap (Jul 2025) | $4.5B |
| Properties / RSF (12/31/2024) | 548 / 114M |
| Occupancy target | >95% |
| Fed funds / 10yr (mid‑2025) | 5.25–5.50% / ~4.2% |
| Top peer market cap | Prologis >$100B |
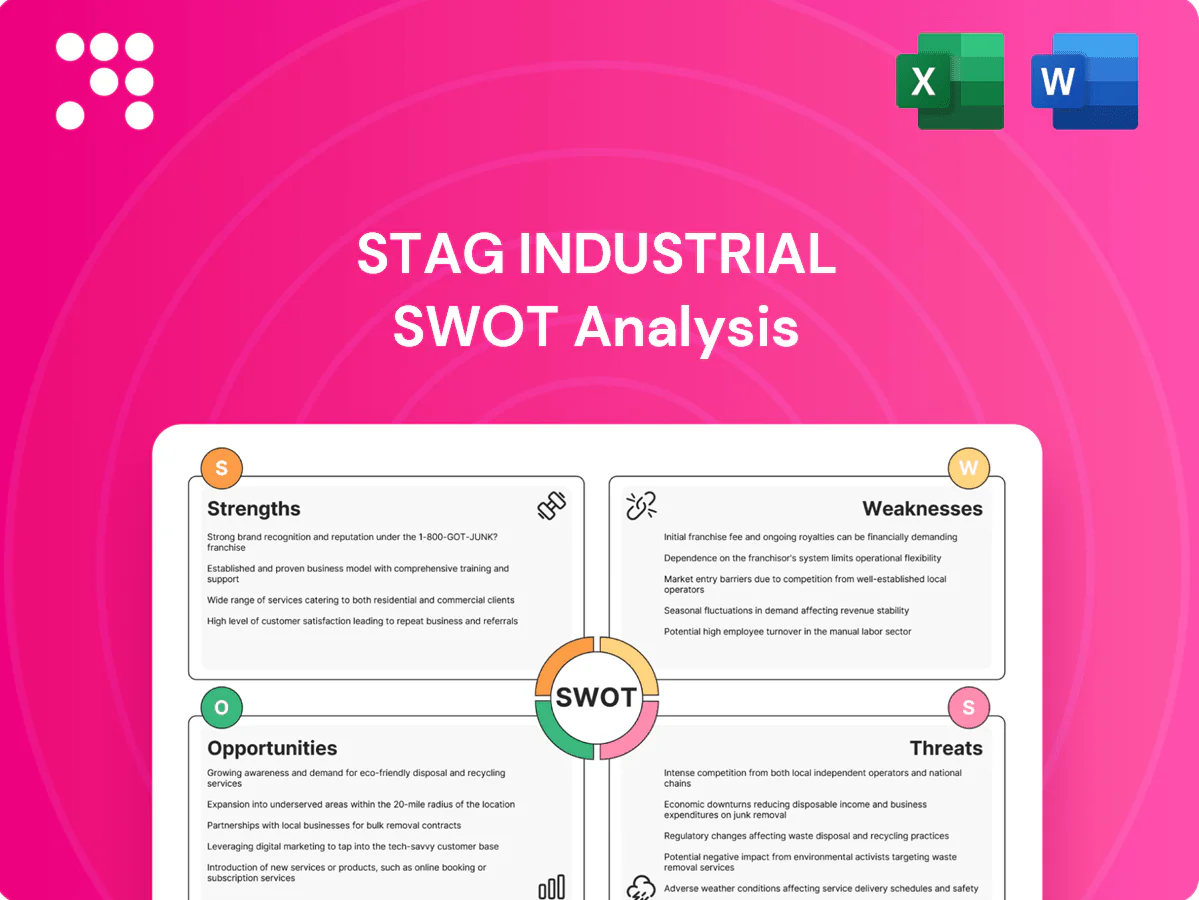
This STAG Industrial SWOT Analysis preview is the actual document you’ll receive after purchase—professional, structured, and ready to use. The excerpt below is pulled directly from the full, editable report; buying unlocks the complete, in-depth version with actionable insights and supporting data. No surprises—just the file shown available immediately after checkout.
U.S. e-commerce topped $1 trillion in 2023, representing roughly 16.5% of retail sales, sustaining demand for fulfillment and last-mile nodes. Nearshoring and higher safety-stock strategies have boosted national warehouse requirements, reflected in rising imports from Mexico and regional manufacturing growth. STAG can prioritize assets near population centers and transport corridors to capture rent growth and bolster occupancy resilience.
Selective upgrades—raising clear heights, adding docks and completing ESG retrofits—support higher rent capture and longer lease terms for single-tenant industrial assets. Repositioning older buildings widens the tenant pool and lease flexibility. Small-capex enhancements often yield outsized ROI. Recycling non-core sale proceeds into higher-yield projects can boost NAV.
Leases with annual rent escalators (typically 2%–3%) give STAG embedded NOI growth that compounds annually and supports predictable cash flow. As below‑market leases roll, re‑lettings can capture current market rates—U.S. industrial vacancy has remained tight in 2024–25 in many gateway submarkets, amplifying mark‑to‑market upside. This dynamic underpins steady FFO expansion without heavy capex.
Consolidating assets along interstates, major ports and air hubs raises tenant appeal and renewal odds; CBRE reported US industrial vacancy at ~4.4% in Q4 2024, supporting pricing power. Clustering drives network effects, cross-sell potential and operating-cost synergies while boosting asset-level data for yield optimization.
Partnering with developers or using JV structures lets STAG access new pipeline while limiting balance-sheet exposure, leveraging its public REIT status since 2011 and single-tenant underwriting expertise to originate build-to-suit deals that match tenant credit profiles.
U.S. e‑commerce surpassed $1 trillion in 2023 (~16.5% of retail), sustaining demand for last‑mile nodes; CBRE vacancy ~4.4% in Q4 2024 supports rent leverage. Nearshoring and higher safety stock raise warehouse demand; 2%–3% annual escalators compound NOI. Targeted capex and JV pipelines let STAG capture mark‑to‑market upside with limited balance‑sheet risk.
| Metric | Value |
|---|---|
| U.S. e‑commerce 2023 | $1T (16.5% retail) |
| Industrial vacancy Q4 2024 | ~4.4% |
| Typical rent escalators | 2%–3% |
Periods of heavy new construction can pressure rents and concessions; U.S. industrial completions surged in 2023–24, with over 50% concentrated in Sun Belt and port-adjacent metros, raising localized lease competition. Delivery waves that coincide with demand slowdowns lift vacancy and blunt mark-to-market upside. Elevated oversupply in fast-growth Sun Belt and port markets threatens renewal pricing and concession-free rent resets.
Economic slowdowns in manufacturing or retail can elevate defaults and space givebacks; STAG Industrial’s single-tenant portfolio concentrates risk so any one tenant failure can materially hit revenue. Re-leasing in weak markets typically extends downtime and raises capex, increasing vacancy and pressure on net operating income. Cash flow variability can strain dividend coverage, as seen in 2024 when tenant credit stress heightened portfolio-level risk.
Persistent high interest rates (Fed funds 5.25–5.50% as of July 2025; 10-year Treasury ~4.3%) compress acquisition spreads and limit FFO growth for STAG by raising financing costs. Refinancing maturing debt at higher coupons reduces dividend headroom and payout flexibility. Cap rate expansion since 2022 pressures NAV and equity valuations and may curtail accretive external growth.
Mega-cap peers such as Prologis (owning/operating ~1.2bn sq ft) can outbid STAG for prime assets, using global scale and balance-sheet depth to win trophy deals. Their advanced amenity, data and customer solutions deepen tenant ties, raising switching costs. Intense competition pushed gateway cap rates to about 4.0–4.5% in 2024, compressing yields and squeezing smaller players.
Local approvals and industrial zoning constraints can delay projects and raise holding costs; the SEC climate-disclosure regime finalized in 2022 has phased-in requirements through 2024–2026 that increase reporting burdens. Evolving environmental standards drive retrofit and reporting costs, while energy-performance and emissions expectations force ongoing capex. Non-compliance risks reputational damage and tenant attrition.
Rising Sun Belt supply and delivery waves (50%+ of 2023–24 completions) boost vacancy and concessions. Single‑tenant concentration increases default risk and downtime; 2024 saw heightened tenant credit stress. Higher rates (Fed 5.25–5.50%, 10y ~4.3% July 2025) and cap‑rate expansion compress NAV; mega‑peers (Prologis ~1.2bn sq ft) outbid STAG. SEC climate rules phased 2024–2026 add capex/reporting costs.
| Metric | Value |
|---|---|
| Prologis size | ~1.2bn sq ft |
| Fed funds | 5.25–5.50% (Jul 2025) |
| 10‑yr Treasury | ~4.3% (Jul 2025) |
| Gateway cap rates | ~4.0–4.5% (2024) |


