
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
STRABAG’s SWOT snapshot highlights robust European market reach, project execution strengths, and exposure to cyclical construction risks and regulatory pressures. Want the full picture—detailed strengths, risks, and strategic opportunities? Purchase the complete SWOT for a research-backed, editable Word and Excel pack to plan, pitch, and invest with confidence.
STRABAGs integrated value chain—covering design, planning, construction, operation and facility management—enables cross-selling and lifecycle revenue capture while standardizing data and processes across projects. Vertical integration improves schedule control and risk management on complex builds, supporting single-point accountability that boosts win rates. As one of Europe’s largest builders with ~75,000 employees (2024), STRABAG leverages scale to execute integrated contracts efficiently.
Balanced exposure to building construction, civil engineering, transport infrastructure and special foundation works helped STRABAG generate group revenue of about EUR 17.6bn (2023), reducing volatility across cycles. The mix smooths public infrastructure and private real estate swings, while tunneling and foundation expertise underpins pricing power and margins. Breadth enhances resilience with a multi-year order backlog supporting revenue visibility.
Scale across DACH and CEE gives STRABAG procurement leverage and deep local supply chains, supported by operations in 30+ countries and ~75,000 employees (2024). Longstanding ties with public authorities sustain an active infrastructure pipeline, while strong brand recognition improves prequalification for large, technically demanding tenders. Regional density reduces mobilization and logistics costs, enhancing bid competitiveness.
STRABAG's robust order backlog—above €20bn at end-2024—provides clear multi-year revenue visibility and enables precise capacity planning; long-duration infrastructure programs sustain utilization across cycles, while facility management and maintenance contracts generate recurring, lower-volatility cash flows that stabilize free cash flow and margins; this foundation supports targeted investment in innovation and talent.
Integrated value chain and vertical integration drive lifecycle revenues and single-point accountability; scale (~75,000 employees, 30+ countries) enables efficient execution. Diversified mix (building, civil, transport, geotechnical) and EUR 17.6bn revenue (2023) reduce cyclicality. Strong backlog (>€20bn end-2024) and PPP/megaproject expertise sustain margins and bid success.
| Metric | Value |
|---|---|
| Employees | ~75,000 (2024) |
| Revenue | €17.6bn (2023) |
| Backlog | >€20bn (end-2024) |
| Countries | 30+ |
 Detailed Word Document
Delivers a strategic overview of STRABAG’s internal and external business factors, outlining strengths, weaknesses, opportunities, and threats to assess its competitive position and growth prospects in construction and infrastructure markets.

 Customizable Excel Spreadsheet
Provides a concise STRABAG SWOT matrix for fast strategy alignment across projects and regions, enabling quick stakeholder briefings and board-ready slides.
Private non-residential and residential demand is highly rate-sensitive: ECB policy rates averaged about 4% in 2024, squeezing mortgage demand and contributing to Eurostat reporting a roughly 3% decline in EU construction output in 2023, which can depress volumes and intensify price competition for STRABAG. Public budgets are subject to election-driven delays, and this cyclicality complicates capacity and cost optimization, risking margin pressure and underutilized resources.
Construction's thin margins hit STRABAG: group EBIT margins have hovered near 2–3% recently, while fixed-price contracts leave limited room for cost overruns. Scope changes, design errors and 2021–24 inflation spikes have eroded project profits, with claims recovery often taking 12–24 months and remaining uncertain. A handful of problematic projects can swing quarterly earnings and strain cash flow.
Large projects demand substantial bonding, guarantees and advance financing, extending cash conversion cycles and raising working capital needs. Payment terms, retention and supply-chain prepayments tie up capital and force inventory buffers, increasing reliance on credit facilities. With euro-area policy rates near 4% in 2024, interest sensitivity and financing costs for such credit dependence have markedly risen.
STRABAG Group employed about 74,000 people in 2024, yet skilled labor shortages across Europe are driving wage inflation and constraining on-site capacity; heavy reliance on subcontractors increases coordination complexity and quality risk, while competition for engineers and site managers causes project delays; training and retention programs take years to scale.
Geographic concentration in Europe leaves STRABAG exposed: macroeconomic shocks or regulatory shifts in core EU markets can have outsized effects on margins and backlog. Limited exposure to faster-growing regions caps secular growth, with roughly 85% of 2024 revenues generated in Europe. Currency swings and cross-border compliance add operational friction, while diversification outside Europe remains modest.
High euro-area exposure (~85% revenues in 2024) and limited APAC/AMER presence cap growth. EBIT margins near 2–3% in 2024 leave little room for overruns; fixed-price contracts and 2021–24 inflation eroded profits. Workforce ~74,000 (2024) amid Europe-wide skill shortages raises wage and subcontractor risks. Elevated borrowing costs (~4% ECB in 2024) press working capital.
| Metric | 2024 |
|---|---|
| EU revenue | ~85% |
| Employees | ~74,000 |
| EBIT margin | 2–3% |
| ECB rate | ~4% |
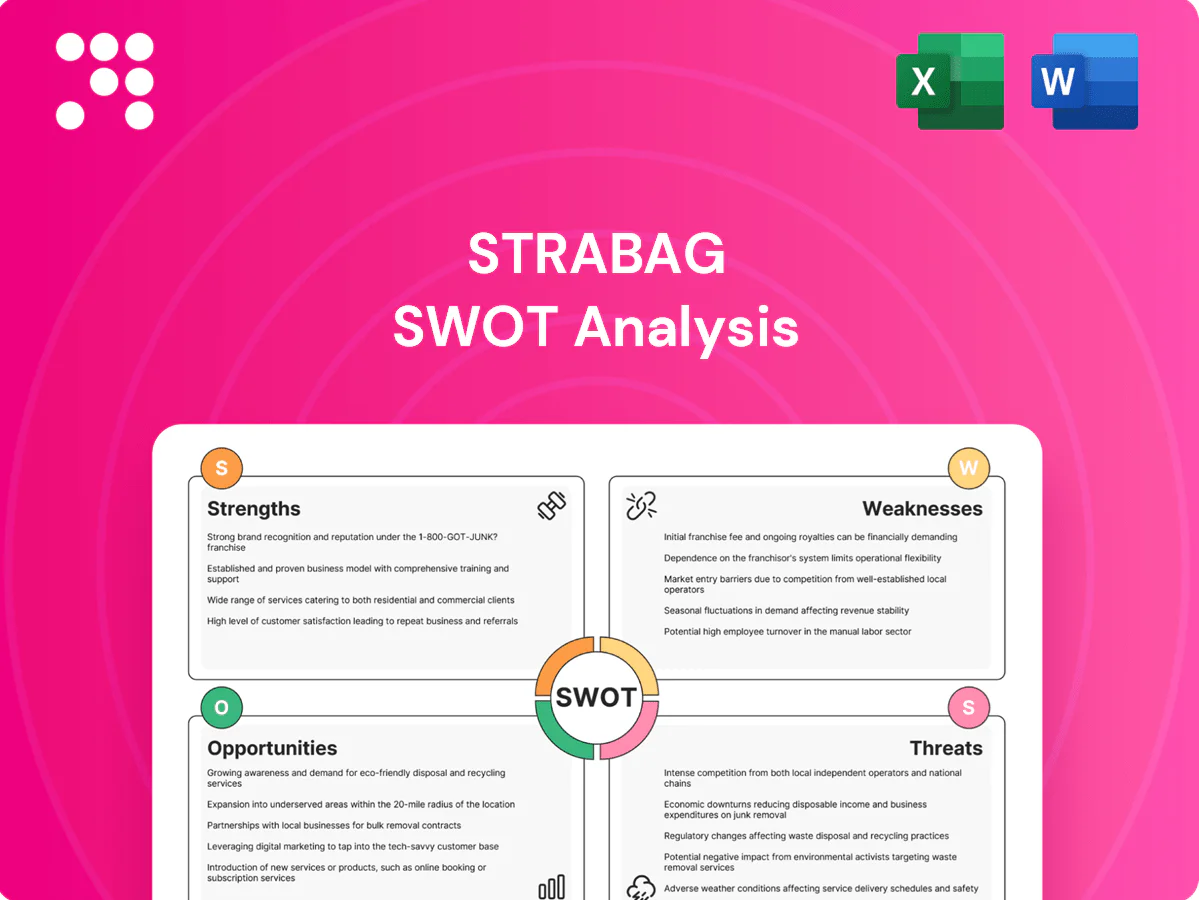
This is the actual STRABAG SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report you’ll get. Purchase unlocks the complete, editable version with in-depth strengths, weaknesses, opportunities and threats.
EU buildings consume about 40% of energy, and the Renovation Wave aims to at least double annual renovation rates by 2030, driving demand for insulation, HVAC and refurbishments. NextGenerationEU and cohesion funds (totaling €750bn) plus national recovery plans channel significant public funding to energy-efficient schools, hospitals and social housing. STRABAG’s integrated construction-to-lifecycle model can capture performance-based contracts and long-term service revenues.
European programs such as NextGenerationEU (€800bn) and the 2021–2027 Cohesion Policy (~€330bn) prioritize rail, bridges, tunnels and road rehabilitation, creating funded pipelines. Aging assets and EU safety mandates drive predictable tenders. STRABAGs geotechnics and large-civil expertise maps directly to these projects, while multi-year frameworks can stabilise volumes and pricing.
Wind, solar, battery and hydrogen projects drive demand for foundations, access roads and balance-of-plant works — global renewable additions reached about 540 GW in 2023–24, underpinning long-term civil works demand. Grid expansion and undergrounding require extensive trenching and substations, with IEA-style estimates pointing to roughly €1 trillion of grid investment across Europe by 2030. Industrial decarbonization adds civil packages for new plants, creating multi-year tailwinds for STRABAG’s civil construction pipeline.
E-commerce penetration rose to 22.3% of global retail sales in 2024, nearshoring and supply-chain reshuffles boost European logistics demand, and AI/data growth is driving hyperscale data-center capacity additions—supporting STRABAG’s industrial, logistics and data-center pipeline. Fast-track, high-spec builds favor firms with robust project controls; repeat-client frameworks and ancilllary O&M lift utilization and margins.
Scaling BIM/4D/5D and digital twins can cut rework and claims by up to 30%, while offsite modular and precast reduce schedules 20–50% and improve safety and productivity; drones, robotics and IoT boost site monitoring and quality, lowering defects and supervision costs. These levers can structurally lift margins and differentiate STRABAG bids in competitive markets.
EU Renovation Wave (buildings 40% of energy) + NextGenerationEU (€800bn) and Cohesion (~€330bn) create €1.13tn public retrofit/infra pipeline to 2030; renewables added ~540 GW (2023–24) and grid needs ~€1tn investment by 2030, underpinning civil works. E‑commerce 22.3% (2024) and hyperscale data-centres boost logistics/industrial demand. Digital construction (BIM −30% rework; offsite −20–50% time) raises margins.
| Opportunity | Metric | Impact |
|---|---|---|
| Public retrofit/infra | €1.13tn | Stable tender pipelines |
| Renewables & grid | 540 GW; €1tn | Civil works demand |
| Logistics/data | 22.3% e‑commerce | Spec builds, repeat clients |
| Digital/offsite | BIM −30% rework | Higher margins |
Price swings in cement, steel, asphalt and energy—with European steel spot prices swinging about ±25% and bitumen/asphalt varying ~30% in 2022–24—compress margins on STRABAG’s fixed-price contracts. Supply disruptions have delayed projects and increased liquidated-damages exposure. Indexation and hedging cover only portions of flows, and imperfect protection plus volatility complicates bidding and procurement planning.
Higher financing costs—ECB deposit rate 4.00% (June 2024) and US Fed funds 5.25–5.50% (2024)—dampen private development and reduce PPP affordability as discount rates and debt service rise. Governments facing fiscal tightening often defer projects, pressuring contractors’ pipelines. Client insolvencies and contract cancellations can increase, raising working capital needs. The squeeze intensifies price competition and margin erosion for STRABAG.
Tighter carbon, waste and labor rules increase complexity and costs for STRABAG as EU ETS carbon prices hovered near €100/t in 2024 and circular-economy targets tighten supply chains. Non-compliance risks fines, project bans and reputational loss—German LkSG penalties can reach €8m or 2% turnover. CSRD reporting now covers ~50,000 firms, escalating cross‑jurisdictional reporting burdens that can outpace adaptation.
Global majors such as Vinci, Hochtief and Skanska and aggressive local players increasingly undercut on public tenders; low‑bid procurement erodes Strabag’s margins and can reward underpricing. Ongoing consolidation (larger balance sheets, fleet scale) strengthens rivals’ bidding power, while commoditized contract packages limit meaningful differentiation and margin recovery.
Volatile input prices (steel ±25%, bitumen ~30% 2022–24), higher rates (ECB 4.00% Jun‑2024) and EU ETS ≈€100/t (2024) squeeze fixed‑price margins; rivals’ consolidation and low‑bid tenders compress margins further. Supply, nat‑cat losses (~$120bn insured 2023) and reinsurance +~20% (2024) raise delays, claims and working‑capital needs.
| Risk | 2023–24 metric |
|---|---|
| Input volatility | Steel ±25%, bitumen ~30% |
| Financing | ECB 4.00% (Jun‑24) |
| Insurance/nat‑cat | $120bn loss; reins +~20% |


