
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
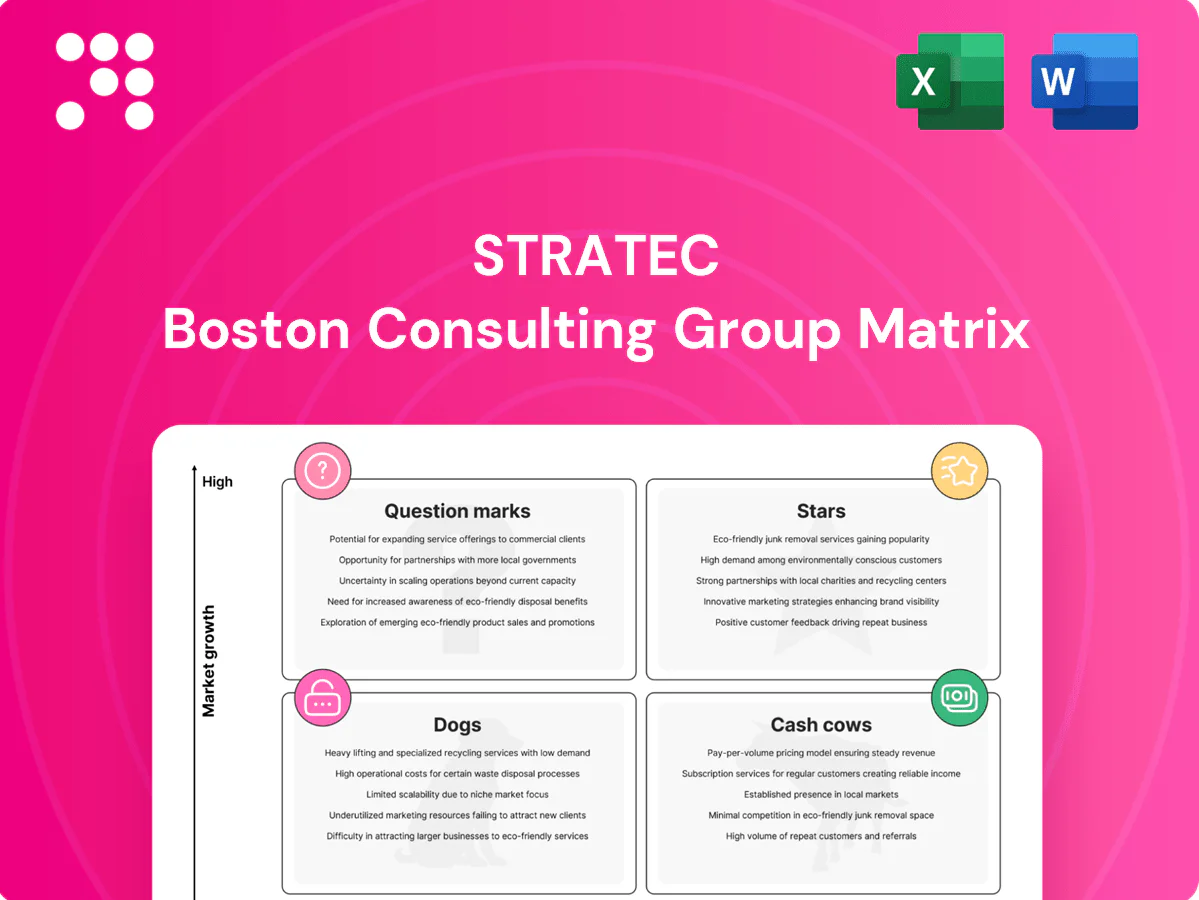
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Want clarity fast? Our STRATEC BCG Matrix preview shows you the rough map—who’s a Star, who’s a Cash Cow, and who’s costing you— but the full report is where strategy happens. Buy the complete BCG Matrix for quadrant-by-quadrant data, actionable recommendations, and ready-to-use Word and Excel files that save you hours and point to where to invest next. Purchase now and turn fuzzy choices into confident moves.
High-growth molecular testing keeps accelerating and STRATEC, via flagship OEM platforms, maintains meaningful share as systems that lead deals and require continuous application expansion, regulatory work, and field support. The global molecular diagnostics market reached roughly $18.5 billion in 2024 with ~8% CAGR, and STRATEC’s growth soaks up investment so cash in equals cash out for now. Continue backing these platforms—they are positioned to become tomorrow’s cash cows.
Integrated robotics that cut hands-on time are winning tenders in fast-growing labs; market adoption pushed STRATEC systems to reported utilization above 80% in 2024. STRATEC’s reliability and partner co-branding give it a leading edge, reflected in sustained high service contracts and recurring consumables revenue. The company remains promotion- and placement-hungry to scale across networks. Double down now to cement leadership as the market matures.
Locked-in cartridges and custom plastics ride installed-system growth: platform-hosted menus now capture roughly 60–70% share in key immunoassay segments (2024), with pull-through volumes rising ~20% year-over-year as installed bases expand. Maintaining this star position requires capacity, tooling and yield investments; typical scale-up capex for tooling runs into mid-single-digit millions of euros per platform. Invest now to lock lifetime value while competitors chase design-ins.
Middleware, LIS drivers and fleet monitoring are central to multi-site rollouts; enterprise lab consolidation accelerated in 2024 with lab informatics adoption growing at ~7.5% CAGR (2024 baseline), and STRATEC frequently shortlisted for enterprise deals.
Continuous releases, cybersecurity and integrations are required; aggressive software funding preserves hardware share via high stickiness and recurring software revenue (2024 emphasis).
Core analyzers co-developed with top diagnostics majors deliver industry-leading reliability and throughput (many platforms >1,000 tests/hour) and support a global immunoassay market of ~USD 11.5bn in 2024 with ~6% CAGR; menu expansion and mid-volume lab consolidation sustain growth, while assay support and 98–99% uptime SLAs are essential to retain share and convert growth into durable cash flow.
STRATEC’s OEM platforms are Stars: high-growth molecular and automation share, driving recurring consumables and service revenue while consuming capex to expand menus and tooling. Key metrics: molecular diagnostics ~$18.5bn (2024, ~8% CAGR), immunoassay ~$11.5bn (2024, ~6% CAGR), system utilization ~80%, consumables pull-through 60–70%. Continue focused investment to secure future cash cows.
| Metric | 2024 |
|---|---|
| Molecular Dx | $18.5bn (8% CAGR) |
| Immunoassay | $11.5bn (6% CAGR) |
| Utilization | ~80% |
| Pull-through | 60–70% |
| Tooling capex | €3–7m/platform |
 Detailed Word Document
STRATEC BCG Matrix: quadrant-by-quadrant analysis with clear invest, hold, or divest recommendations.

 Customizable Excel Spreadsheet
One-page STRATEC BCG Matrix maps units into quadrants, clarifying strategy and easing C-level decisions.
Legacy clinical chemistry platforms sit in a mature market with an entrenched installed base and predictable 7–10 year replacement cycles, supporting 2024 IVD spending of roughly 95 billion USD. High-margin parts, service and reagent kits (around 60% gross margin for consumables in 2024 industry averages) provide steady cash flow with low new-placement capex. Incremental hardware and software upgrades extend fleet life; prioritize milking the base and optimizing service routes for margin expansion.
Established immunoassay consumables remain STRATEC's 2024 cash cow with stable volumes year-over-year and low customer churn, driven by long-approved cartridges and recurring reagent demand.
Manufacturing is dialed-in: scrap rates are minimal and gross margins remain healthy, supporting consistent free cash flow without heavy marketing spend.
Minimal promotion beyond supply assurance is required; focus on maintaining tooling, continuous yield improvements and incremental efficiency captures to maximize cash generation.
Large installed base drives steady service contracts and spare-parts orders, delivering modest growth but excellent cash conversion for STRATEC; recurring service margins typically outpace product margins. Route density combined with remote diagnostics minimizes field costs and technician travel. Maintain strict SLAs and disciplined pricing to protect margins and lifetime value.
Middleware licenses in mature labs renew quietly year after year, with industry 2024 renewal rates around 90% and enterprise churn near 6%; feature development needs are low compared with net-new builds. High gross margins (~75% in 2024 SaaS/middleware benchmarks) make these stable cash cows; priority is protecting renewals and selectively upselling analytics where payback occurs within 6–12 months.
OEM customization toolkits—re-usable modules, enclosures, and control stacks sold into repeat programs—generate steady, high-margin cash flow for STRATEC because development costs are amortized across multiple programs; demand remains stable rather than explosive in 2024. Keeping libraries current and monetizing templates turns maintenance into recurring revenue and preserves margin leverage.
Legacy platforms and immunoassay consumables deliver steady, high-margin cash flow—IVD market ~95 billion USD in 2024—with consumables ~60% gross margin and middleware ~75% gross margin. Renewal rates are ~90% and churn ~6% (2024), minimizing new-placement capex; prioritize service efficiency, tooling upkeep and selective analytics upsells with <12-month payback.
| Metric | 2024 |
|---|---|
| IVD market | ~95 billion USD |
| Consumables GM | ~60% |
| Middleware GM | ~75% |
| Renewal rate | ~90% |
| Churn | ~6% |
The STRATEC BCG Matrix you’re previewing is the exact file you’ll receive after purchase — no watermarks, no demo slides, just the finished, professionally formatted report. It’s ready to edit, print, or present, built for strategic clarity and immediate use. Buy once, download instantly, no surprises.
Obsolete analyzers exhibit shrinking parts availability and thin usage, driving declining market share and heavy service burdens. Little market growth remains and support-heavy platforms erode margins, while attempted turnarounds typically burn cash with limited upside. Plan orderly sunsetting, negotiate parts last-buys and reallocate R&D to growth platforms to minimize lifecycle costs.
One-off bespoke projects for niche STRATEC clients consumed disproportionate engineering hours, produced little recurring revenue and rarely scaled; McKinsey found in 2024 that about 70% of bespoke/transformational tech initiatives fail to scale. At best these initiatives break even, often distracting core teams and reducing margin contribution. Recommendation: exit or fold validated learnings into standard modules only.
Non-core research instruments serve small, non-regulated labs with sporadic orders, representing low share and limited growth (single-digit contribution to STRATEC group revenue in 2024). Price pressure and high support costs make margins weak versus core IVD lines; support often outweighs strategic value. Divest or partner out distribution to cut overhead and redeploy capital to regulated IVD.
Unprofitable geographies in STRATEC act as Dogs: tenders are won on price rather than total value, with weak service density and 2024 regional growth near 0%, leaving market share unstable and margin dilution. Cash is tied up in inventory and travel, with working capital days reportedly elevated versus peers in 2024. Prune footprint or shift to distributor-only to stop cash bleed and stabilize margins.
Legacy STRATEC products are Dogs: old stacks that are hard to secure and integrate, with customers mostly tolerating rather than expanding contracts; in 2024 roughly 65% of IT budgets were consumed by maintenance, pulling engineering away from growth and new product work. Decommission or migrate these modules to current platforms to stop security exposure and free resources for scale.
Obsolete analyzers, bespoke projects, niche instruments and loss-making geographies are Dogs: low share and ~0–1% growth, high service/maintenance burden (65% of IT spend on legacy in 2024) and cash drag; recommend sunsetting/divest, migrate legacy, fold learnings into standard modules and shift to distributor-only to free R&D for growth.
| Metric | 2024 | Action |
|---|---|---|
| Market growth | ~0–1% | Prune footprint |
| Legacy IT spend | 65% of IT budget | Migrate/decommission |
| Bespoke scale failure | 70% (McKinsey 2024) | Exit or standardize |
Point‑of‑care OEM platforms are firing markets in 2024 but STRATEC’s share remains in the low single digits versus established incumbents. Early placement economics are tough, with OEM deals often absorbing R&D and validation costs before scale. If STRATEC lands sufficient menu breadth and design‑wins this year it could flip to star status rapidly; management must decide to invest for design‑wins or pursue partnerships.
Rapid-testing menus are expanding in 2024 but cartridge volumes remain nascent, often under 10,000 units/month per assay, while NRE and tooling frequently exceed $1M up front, creating unclear pull-through economics. Secure anchor assays and scale to shift toward star status, otherwise modules risk drifting into dog territory. Fund selectively with milestone gates tied to assay wins, scale thresholds and pay-per-run KPIs.
AI/analytics for QC and uptime sits as a Question Mark: the lab analytics segment is in high-growth (AI in healthcare ~17.4B USD in 2024 with ~37% CAGR to 2030), but STRATEC remains a challenger with limited monetization to date. Data hooks exist across instrument telemetry and assay QC, and early monetization has yielded pilot revenues only. Prioritize landing lighthouse customers to prove ROI and ROI case studies. Focus investment on a few high-impact use cases (predictive maintenance, assay drift detection) or pause until platform stickiness increases.
Bioprocess and life‑science automation sits in an attractive adjacent market: global lab automation was roughly USD 6.5 billion in 2024 with >8% CAGR, driven by demand for automated workflows in biologics and cell‑therapy supply chains.
STRATEC’s brand credibility helps entry but current market share in this segment remains small; success requires stronger BD capabilities and domain‑specific features (single‑use handling, GMP traceability).
Pilot with strategic partners, validate product/price and scale only if achieved margins converge toward IVD benchmarks (target gross margin band ~50–60% in 2024).
Healthcare systems are consolidating toward hub‑and‑spoke models but interoperability standards still vary across regions; in 2024 adoption momentum increased, leaving STRATEC early in footprint with high upside if it wins system‑wide deals to lock in switch costs.
POC OEM share low vs incumbents; cartridge volumes often <10,000/month per assay and NRE/tooling >1M USD. AI analytics market ~17.4B USD (2024, ~37% CAGR) but STRATEC shows only pilot revenues. Lab automation ~6.5B USD (2024, >8% CAGR); target IVD gross margin 50–60%; pursue lighthouse deals, milestone funding.
| Segment | 2024 size | CAGR | STRATEC share | Action |
|---|---|---|---|---|
| POC OEM | — | — | low single % | invest for design‑wins |
| AI analytics | 17.4B USD | ~37% | pilot | lighthouse customers |
| Lab automation | 6.5B USD | >8% | small | partner pilots |


