
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
Unlock the full strategic blueprint behind Summit Financial Services Group with our Business Model Canvas—three to five detailed sentences that map value propositions, revenue streams, and growth levers. Ideal for investors and strategists seeking actionable insights. Download the complete, editable canvas to benchmark and execute with confidence.
Partnerships with leading custodians enable secure asset safekeeping, trade execution and cash management across an industry that handles over $100 trillion in global custody assets (2024 industry estimate), ensuring regulatory-grade controls and settlement efficiency. Integrated brokerage platforms can cut reconciliation time up to 40% and materially improve reporting quality and client transparency. Scale pricing and rigorous SLAs typically boost operational margins by 10–20% while co-marketing and aligned technology roadmaps drive client acquisition and multi-year platform stability.
Open-architecture relationships with mutual fund, ETF, SMA and alternatives managers expand the investable universe—over 10,000 ETFs existed globally in 2024. Rigorous due diligence pipelines ensure fiduciary alignment and ongoing performance monitoring. Access to institutional share classes lowers client costs, while research access and portfolio tools improve portfolio construction.
Alliances with estate attorneys, CPAs (over 600,000 licensed in the US in 2024), and trust companies support complex planning around the 2024 federal estate tax exemption of $13,610,000 and 40% top rate. Coordinated strategies optimize tax efficiency, wealth transfer, and asset protection. Shared workflows reduce errors and client friction and joint client meetings elevate perceived value and retention.
Technology and fintech vendors—CRM, financial planning, risk‑profiling and reporting providers—form the advice stack, with the global CRM market worth about $59 billion in 2024 and cybersecurity spending topping roughly $170 billion in 2024; API‑enabled integrations cut manual work and improve data accuracy, while white‑label client portals raise engagement and transparency.
Relationships with carriers and private banks enable tailored risk transfer and liquidity solutions for high-net-worth (HNW) clients, with HNW defined as investable assets of 1,000,000 or more.
Premium finance and securities-based lending provide credit lines that commonly fund premiums from low six figures to over 1,000,000, meeting complex cash-flow needs.
Independent brokerage access and collaborative underwriting preserve fiduciary standards while improving product fit and pricing.
Custodian, brokerage and fintech partnerships secure custody and execution across a $100T global custody market (2024), cut reconciliation up to 40% and boost margins 10–20%. Manager, carrier and private bank alliances expand investable options (10,000+ ETFs in 2024) and enable HNW solutions (HNW ≥1,000,000). Advisor/legal/CPA ties support tax-efficient planning around the $13,610,000 estate exemption (2024).
| Partner | Benefit | 2024 Stat |
|---|---|---|
| Custodians | Settlement, custody | $100T global assets |
| Managers | Product access | 10,000+ ETFs |
| Advisors/CPAs | Tax/estate | Exemption $13,610,000 |
 Detailed Word Document
A comprehensive Business Model Canvas for Summit Financial Services Group that maps customer segments, channels, value propositions, revenue streams, and key resources across the classic 9 blocks, reflecting real-world operations and strategic plans. Ideal for presentations and investor due diligence, it includes SWOT-linked insights and competitive advantages to support decision-making and validation.

 Customizable Excel Spreadsheet
High-level view of Summit Financial Services Group’s business model with editable cells, streamlining complex strategy into a single pain-relieving snapshot for teams and executives.
Holistic plans integrate cash flow, taxes, retirement, education, insurance and estate strategies; annual reviews plus ad hoc updates track life changes and 2024 inflation (~3.4%). Scenario modeling uses 10,000 Monte Carlo runs and stress tests targeting a 90% probability of meeting goals to guide decisions. Thorough documentation meets fiduciary and regulatory recordkeeping standards and supports auditability.
Research-driven asset allocation and manager selection underpin portfolios, using quarterly rebalancing and target bands (typically ±5%) to preserve strategic exposures. Active rebalancing, tax-loss harvesting (which can boost after-tax returns by up to ~1% annually for high-bracket investors) and disciplined cash management maintain objectives. Continuous risk monitoring ensures alignment with the IPS and client goals, while monthly performance reporting closes the advice loop.
Structured discovery uncovers objectives, constraints, and preferences while regular reviews track progress, update assumptions, and surface new opportunities. Life-event playbooks ensure timely action and standardized responses. Meeting notes and tasks feed the CRM for continuity; CRM adoption among RIAs reached about 72% in 2024, linked to roughly 18% higher retention and cross-sell rates.
RIA policies enforce suitability, best execution, and conflicts management across ~13,500 registered advisers in 2024, with surveillance, trade supervision, and books-and-records designed to support regulatory exams. Cybersecurity, vendor oversight, and business continuity programs—72% of firms ran annual tabletop cyber exercises in 2024—reduce operational risk. Ongoing training embeds fiduciary duty and lowers compliance incidents.
Thought leadership, centers-of-influence, and client advocacy drive growth, with referrals converting at roughly 3x the rate of cold leads (industry benchmark 2024). Segmented marketing boosts revenue—Campaign Monitor/Hopkins data shows targeted campaigns can lift revenue up to 760%. Pipeline management tracks conversion and capacity; onboarding workflows create a consistent first-90-days client experience.
Comprehensive planning using 10,000-run Monte Carlo and 90% success targets guides decisions; annual reviews and life-event playbooks ensure updates. Portfolios use research-driven allocation, ±5% rebalance bands, tax-loss harvesting (~1% after-tax lift for high-bracket investors) and monthly reporting. Ops and growth: 13,500 RIAs, CRM adoption 72% (2024), referrals convert ~3x cold leads.
| Metric | 2024 |
|---|---|
| CRM adoption | 72% |
| RIA count | 13,500 |
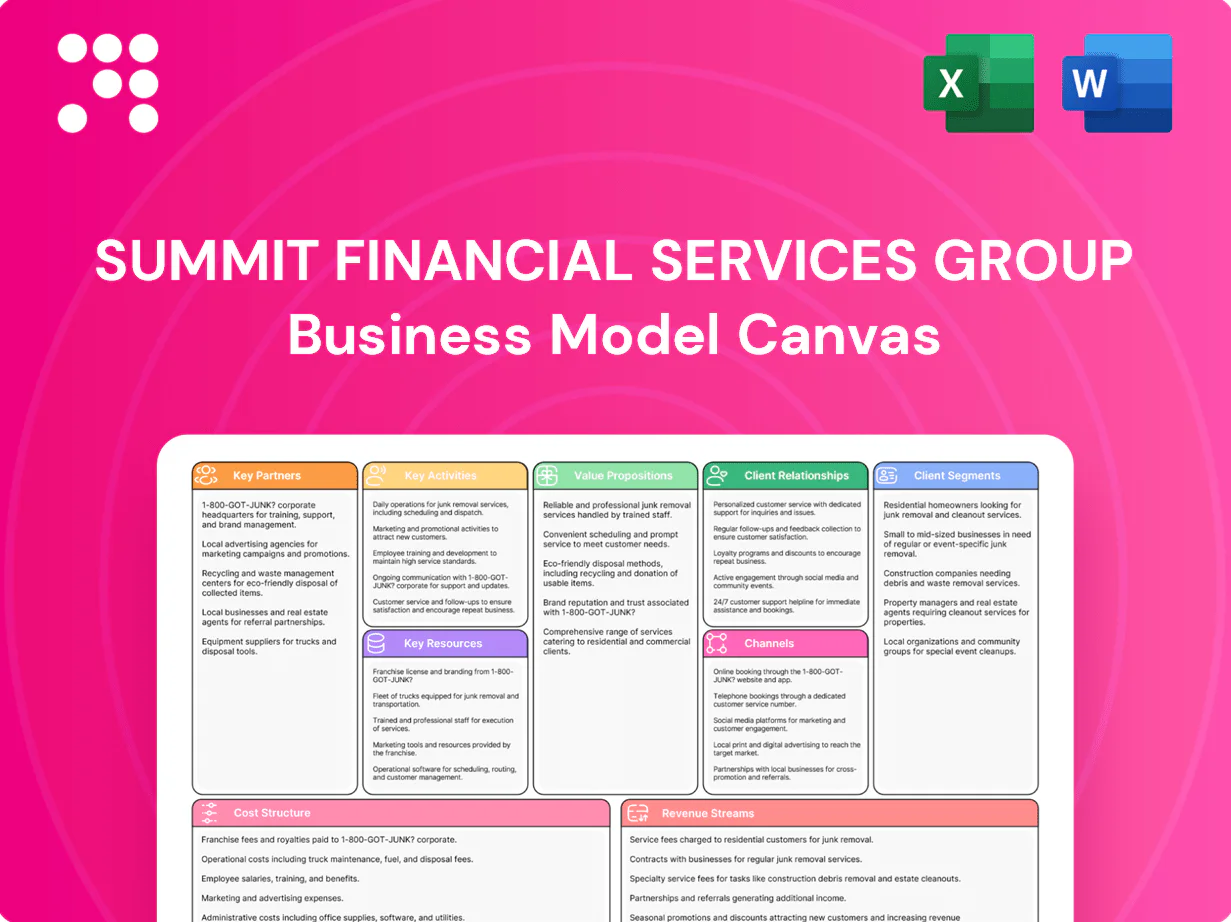
This preview is a genuine excerpt of the Summit Financial Services Group Business Model Canvas—not a mockup—and it’s the exact document you’ll receive after purchase. When you buy, you’ll get the complete, fully formatted file ready to edit and present in Word and Excel. No placeholders or additions—what you see is what you’ll own.
CFA, CFP, CPA and JD designations at Summit signal depth and credibility; globally there were over 200,000 CFA charterholders and roughly 100,000 CFP certificants by 2024. Teams blend planners, portfolio managers and client-service associates to deliver integrated advice. Ongoing training and mentorship programs sustain quality at scale. Active succession planning preserves client continuity across transitions.
Planning, CRM, portfolio accounting, trading, and reporting tools form the core tech stack, enabling end-to-end workflows across Summit Financial; integrated systems in 2024 cut reconciliation time by about 40% and error rates substantially. Data integrations improve timeliness and reduce manual touches, while client portal and mobile apps—adopted by roughly 70% of firms—boost transparency and client engagement. Embedded analytics drive practice management and compliance, surfacing KPI dashboards and regulatory-ready audit trails in real time.
Model portfolios, capital market assumptions and due diligence files are proprietary assets underpinning advisor decisions and compliance; in 2024 ETF assets surpassed 10 trillion USD, highlighting demand for transparent, research-driven solutions. Playbooks and checklists standardize quality and reduce onboarding time by up to 30%. Risk frameworks guide allocation and manager selection across volatility regimes. Content assets fuel marketing, education and lead generation.
Trusted brand and client relationships drive referrals and pricing power; 2024 industry surveys show trust and referrals remain primary acquisition channels. High-touch service produces strong loyalty and longevity, supporting retention and recurring revenue. Compliant testimonials and case studies validate outcomes, while multi-generational relationships expand lifetime value across decades.
RIA registration and ADV filings enable advisory activities and client disclosures; there were roughly 13,000 SEC-registered RIAs in 2024. Custodial and tech agreements underpin operations—major custodians hold trillions (Charles Schwab reported roughly 7 trillion in client assets in 2024). E&O insurance (typical limits 1–5 million) and fidelity bonds (100k–1M) reduce financial risk. SLAs formalize service expectations and accountability with common uptime targets of 99.9–99.99%.
Summit’s credentialed team (200k+ CFA, ~100k CFP in 2024) and integrated tech stack (CRM/trading/reporting; ~70% adoption) enable scalable, compliant advice. Proprietary model portfolios and due diligence support allocation and marketing. Custodial/RIA (≈13,000 SEC RIAs in 2024), E&O (1–5M) and SLA (99.9–99.99%) secure operations.
| Resource | Metric | 2024 |
|---|---|---|
| Credentials | CFA/CFP | 200k+/~100k |
| RIA | SEC-registered | ≈13,000 |
| Custodian | Assets (Schwab) | ~7T |
Advice is delivered under the fiduciary standard of the Investment Advisers Act of 1940 with transparent fees (industry median advisory fee ~0.65% of AUM). Recommendations are tailored to client goals, risk tolerance and time horizon, not product sales. Conflicts are minimized, disclosed and managed; 74% of investors cite fee transparency as a key trust driver. Outcomes are prioritized over product commissions.
Integrated, goals-based planning at Summit aligns investments, taxes, retirement and estate strategies into a single roadmap so clients see trade-offs and tax-efficient paths. Dynamic updates — with 58% of advisors using cash-flow/scenario tools in 2024 — keep plans relevant through life changes. Coordination with external professionals amplifies execution and reduces gaps between plan and outcome.
Tax-aware rebalancing, tax-loss harvesting and strategic asset location optimize after-tax returns—especially given the 37% U.S. top federal rate in 2024—by harvesting losses and placing tax-inefficient assets in tax-deferred accounts. Evidence-based allocations lower turnover and trading costs while controlling risk. Institutional access secures lower expense ratios and broader strategies. Transparent, periodic reporting drives client confidence and oversight.
Tailored strategies align with each client’s goals and risk profile, reflecting unique circumstances and preferences. Direct advisor access drives faster decision-making and responsiveness; 2024 industry surveys show 74% of clients value live advisor contact. Proactive outreach anticipates needs and white-glove onboarding cuts setup time and churn.
Multi-generational wealth stewardship aligns estate and legacy planning with family values to ensure purpose-driven asset transfer; the US faces an estimated 84 trillion dollar intergenerational transfer through 2045, driving demand for coordinated stewardship. Education for heirs builds next-gen stewardship while trust coordination preserves intent and efficiency and continuity plans secure long-term client relationships.
Fiduciary, tax-aware investing: 0.65% fee; goals tools 58%, advisor access 74%, $84T transfer
Fiduciary advice with transparent median advisory fee ~0.65% (2024) and minimized conflicts; outcomes-focused, tax-aware investing boosts after-tax returns. Integrated goals-based planning with dynamic cash-flow tools (58% adoption, 2024) and direct advisor access (74% prefer) supports multi-generational stewardship amid an $84T intergenerational transfer through 2045.
| Metric | Value | Year/Source |
|---|---|---|
| Advisory fee (median) | 0.65% | 2024 |
| Prefer live advisor | 74% | 2024 |
| Cash-flow tool use | 58% | 2024 |
| Intergenerational transfer | $84T | through 2045 |
Client households are supported by a three-person team: a lead advisor, an associate, and a service specialist, ensuring clear role-based accountability and faster responses. Built-in continuity protects service during absences and preserves client relationships. The team model enables scalable growth while maintaining personalization through role specialization.
Quarterly or semiannual reviews, chosen by client complexity and preference, create a predictable cadence; as of 2024 these scheduled reviews remain the industry standard for high-net-worth engagement. Agendas consistently cover markets, goals, and clear action items to drive accountability. Between-meeting touchpoints handle timely issues and urgent adjustments. All notes and follow-ups are recorded and tracked in the CRM for compliance and continuity.
Checklists and timelines set expectations from day one, reducing confusion and churn; 2024 industry ACAT averages ran about 9 business days, so clear timelines matter. Streamlined ACATs, beneficiary updates and IPS creation speed activation, while targeted education cuts errors and anxiety, and early wins build trust quickly.
Clients access portfolios, documents and reports 24/7 via Summit’s portal; secure messaging and e-sign workflows cut turnaround by up to 40% (2024 industry benchmark), while interactive dashboards raise goal-tracking engagement by ~30% (2024 study) and permission tiers enable family and professional collaboration across 68% of multi-advisor households.
Webinars, market updates and workshops extend value beyond meetings and position advisors as trusted guides; industry webinar benchmarks (ON24 2024) show average attendance around 42%, underscoring scalable reach. Live Q&A drives engagement and referral momentum, while segmented topics (retirement, wealth transfer, ESG) meet varied client needs and boost relevancy.
Client households supported by a 3-person team ensure continuity, faster responses and scalable personalization. Scheduled reviews (quarterly/semi) and CRM-tracked touchpoints drive accountability; e-sign/portal cut TAT ~40% and dashboards raise engagement ~30%. Webinars (~42% attendance) and segmented content boost trust and referrals.
| Metric | Value |
|---|---|
| Team model | 3-person |
| TAT reduction | −40% |
| Engagement lift | +30% |
| Webinar attendance | 42% |
| Permissioned access | 68% |
| ACAT avg | 9 days |
Relationship-driven prospecting leverages networks and centers of influence to access high-intent prospects; 2024 industry data shows referral-sourced leads convert about 3x more often and close ~25% faster. Warm introductions convert at higher rates, so advisors prioritize COI referrals. Personalized proposals tie recommendations to specific goals and AUM targets. A disciplined follow-up cadence (5–7 touches) nurtures trust and lifts conversion.
SEO, gated content and financial calculators drive qualified traffic—organic search accounted for about 53% of site visits in 2024 (BrightEdge). High-converting landing pages and clear CTAs (average landing-page conversion ~9.7%) feed prospects into the CRM. Retargeting keeps visibility with CTRs up to 10x higher than standard display (Google Ads 2024), while compliance-approved content ensures consistent messaging.
Satisfied clients introduce family and peers, and in 2024 referrals generated about 35% of new advisory clients for comparable firms. Structured ask moments and digital referral tools increase flow and lift conversion rates. Exceptional service makes advocacy natural, with referred clients showing higher retention. Consistent thank-you protocols reinforce appreciation and repeat referrals.
Seminars, philanthropy, and sponsorships build local credibility and brand visibility; Giving USA 2024 reported US charitable giving at $499.33 billion in 2023, underscoring community impact. Speaking engagements showcase expertise and create trusted touchpoints. Structured lead capture converts event attendance into measurable pipeline and follow-up content sustains momentum and nurtures leads.
Relationship-driven referrals, SEO/organic (53% of site traffic, BrightEdge 2024), events and professional alliances drive most qualified leads; referrals ~35% of new clients and close ~30% faster (2024). Disciplined 5–7 touch cadence and gated content lift conversions (~9.7% landing-page avg).
| Metric | Value | Source |
|---|---|---|
| Referral share | 35% | 2024 peer firms |
| Faster close | ~30% | 2024 |
| Organic traffic | 53% | BrightEdge 2024 |
| Landing conv. | 9.7% | 2024 avg |
High-net-worth individuals, numbering about 23.3 million globally in 2024 with roughly $86.3 trillion in investable wealth per Capgemini, demand bespoke, discretionary wealth management. Their needs include tax-efficient planning, concentrated stock strategies, and bespoke credit solutions. Time-poor executives prioritize delegation, expecting high performance and white-glove service.
Affluent families and multi-generational households often hold complex estates across multiple trusts and entities, requiring coordinated tax, legal and investment management; industry estimates in 2024 put intergenerational wealth transfers at roughly $84 trillion over coming decades. Heir education and formal governance frameworks are critical as about 60% of wealthy families prioritize succession planning. Philanthropy and legacy goals drive bespoke strategies, and long horizons (advisor relationships commonly exceeding 15 years) favor durable, multi-disciplinary partnerships.
Business owners prioritize liquidity planning, 401(k)/cash balance plans, and exit readiness to maximize enterprise value. Coordinating business and personal finances is essential across 33.2 million U.S. small businesses (SBA 2024). Risk management and asset protection feature prominently. Tax strategies, including federal long-term capital gains rates up to 20%, materially drive after-tax proceeds.
Corporate executives and professionals face complex equity comp, deferred comp, and 10b5-1 plan issues; in 2024 equity awards accounted for roughly 60% of median CEO pay at S&P 500 firms, making tax, liquidity, and insider-trading controls vital. Time constraints demand streamlined advisory workflows and pre- and post-vesting strategies to optimize outcomes while ensuring privacy and regulatory compliance.
Plan design, participant education and fiduciary oversight are core services for qualified plans and small business clients, ensuring compliance and tailored benefit strategies for employers and participants.
Managed accounts and QDIA solutions improve outcomes and engagement; auto-enrollment drives participation to about 85% (2024 industry data).
Vendor benchmarking controls costs while business continuity and administrative simplicity increase plan adoption and retention among small employers.
HNW (23.3M; $86.3T investable, 2024) require discretionary wealth, tax-efficient and bespoke credit/concentrated-stock strategies.
Affluent families face ~$84T intergenerational transfers, needing succession, governance and legacy/philanthropy planning.
Business owners & execs (33.2M US small businesses; CEO pay ~60% equity) need liquidity, exit readiness, tax and compliant equity solutions.
| Segment | 2024 stat | Primary needs |
|---|---|---|
| HNW | 23.3M / $86.3T | Discretionary, tax, credit |
| Families | $84T transfer | Succession, governance |
| Owners/Execs | 33.2M; 60% equity | Liquidity, exit, tax |
Salaries, incentives, benefits and training drive costs—compensation represented about 60% of operating expenses for median financial advisory firms in 2024. Clear career paths and certifications can cut turnover by up to 25% and raise client NPS; variable pay aligns to AUM growth and client outcomes; recruiting investment supports succession planning and scalable headcount.
SaaS licenses ($30–$200/user/month) and data feeds (Bloomberg ~ $24,000/year) plus integration and API fees are recurring. Cybersecurity, backups and BCP—commonly 10–15% of IT budgets—add resilience. Custom development tailors workflows, while analytics investments (BI platforms, ML models) inform strategic decisions.
Ticket charges (broker-assisted $25–50 in 2024), wire fees ($25–35) and account service costs ($50–150/yr) accrue per-client; negotiated pricing and volume discounts can boost margins 20–40%. Outsourced operations and TAMP fees (typical 0.25–1.25% AUM) may apply, while error resolution and QC add incremental overhead often equating to 5–15% of ops costs.
Compliance staffing, mandatory audits, and regulatory filings such as Form ADV and annual financial reports drive recurring personnel and external audit costs for Summit Financial Services Group.
Legal counsel manages contract review and litigation support for complex client matters and regulatory inquiries.
Errors and omissions and cyber insurance policies reduce balance-sheet exposure and support client trust; SOC 2 or equivalent audits often accompany cyber controls.
Content production, advertising, and CRM tools (CRM SaaS $50–150/user/month in 2024) drive pipeline and require ongoing spend; sponsorships and seminars (conversion uplift 10–20% in 2024 event studies) build brand while COI programs need dedicated budget lines. Prospect hospitality (avg. $100–500/event) measurably improves conversion.
Salaries and benefits drive costs—compensation ~60% of operating expenses for median advisory firms in 2024; training and certification reduce turnover up to 25%. Recurring tech and data: SaaS $30–200/user/month, CRM $50–150/user/month, Bloomberg ~$24,000/yr; cybersecurity adds 10–15% of IT spend. Client-level fees (broker ticket $25–50, wires $25–35) and TAMP fees 0.25–1.25% AUM compress margins; compliance, legal and insurance are fixed recurring costs.
| Category | 2024 Benchmark |
|---|---|
| Compensation | ~60% operating exp |
| SaaS | $30–200/user/mo |
| CRM | $50–150/user/mo |
| Data feeds | Bloomberg ~$24,000/yr |
| Marketing | 8–12% revenue |
| Broker/Wire fees | $25–50 / $25–35 |
| TAMP | 0.25–1.25% AUM |
Tiered, transparent advisory fees on managed assets are primary, typically structured from 0.25% to 1.25% depending on account size and complexity across brackets (0–500k, 500k–5M, >5M). Pricing scales with complexity and scale, quarterly billing smooths cash flow and improves predictability, and fee compression is mitigated by demonstrable value delivery, performance reporting, and advisory services bundling.
Flat or subscription fees ($100–$400/month) cover financial planning and ongoing advice with clear scopes defining deliverables and meeting cadence quarterly or semiannually.
Annual retainers ($2,000–$10,000) align incentives to client outcomes by tying continued advice to goals and performance metrics.
Standalone plans price at $2,000–$5,000 and, industry-wide, about 20–30% convert to AUM within 18–24 months as clients add investment mandates.
One-time project engagements address specific needs such as equity comp or rollover analysis, priced commonly at $150–$400 per hour or $2,000–$50,000 per project in 2024; fixed-fee or hourly structures scale to complexity and client risk tolerance. These engagements let prospects test fit and, with industry conversion rates of roughly 25–40%, serve as an on-ramp to broader advisory retainers.
Advisory fees for ERISA and non-ERISA retirement plans are asset- or participant-based, commonly 0.10%–1.00% of assets or $25–$200 per participant (2024 industry range); services include committee support and vendor benchmarking, while education programs measurably boost participation and deferral rates; cross-sell opportunities extend to owners via executive benefits and personal advisory services.
Where permissible, Summit charges advisory fees for analysis and coordination, typically in industry ranges of 0.5–1.5% AUM with a 2024 median advisor fee near 0.70% AUM; product commissions are avoided or fully disclosed to preserve fiduciary alignment. Strategic partnerships deliver client insurance and lending solutions without balance sheet risk, supporting fee-only compliance and enhancing the firm’s holistic value proposition.
Tiered AUM fees (0.25%–1.25%, median ~0.70% in 2024) are primary, billed quarterly and scaled by complexity. Subscription planning $100–$400/month; standalone plans $2k–$5k with 20–30% AUM conversion in 18–24 months. Projects hourly $150–$400 or $2k–$50k, ~25–40% convert. ERISA fees 0.10%–1.00% or $25–$200/participant (2024).
| Stream | Pricing (2024) | Conversion/Notes |
|---|---|---|
| AUM fees | 0.25%–1.25% (median 0.70%) | Quarterly billing |
| Planning subs | $100–$400/mo | Ongoing advice |
| Standalone plans | $2k–$5k | 20–30% → AUM |
| Projects | $150–$400/hr or $2k–$50k | 25–40% convert |
| ERISA | 0.10%–1.00% or $25–$200/pt | Committee support, upsell |


