
Digital download
Access the files immediately after checkout.
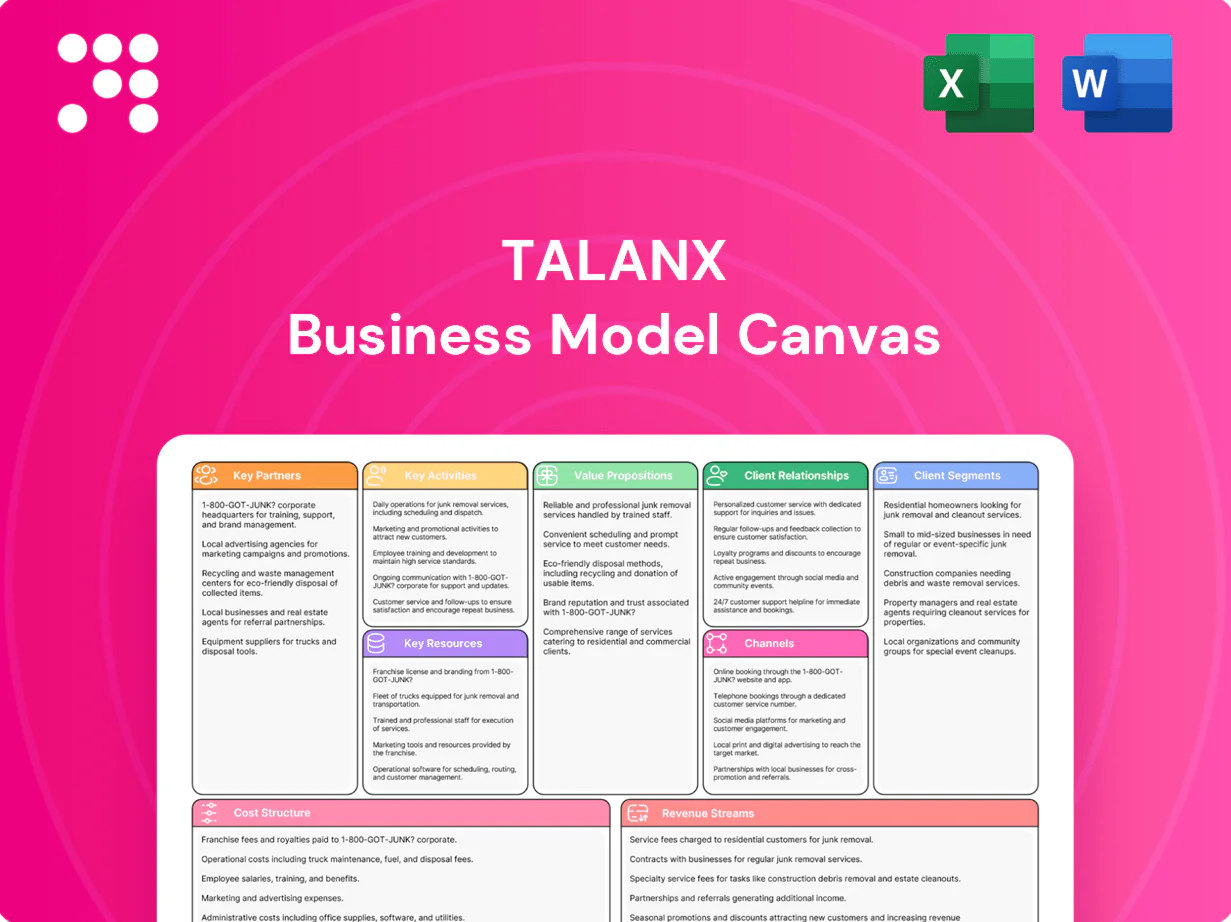
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
Unlock Talanx’s strategic blueprint and discover how it creates value across insurance, reinsurance and asset management. This Business Model Canvas maps customer segments, revenue streams, key partners and cost drivers. Ideal for investors, consultants and strategists seeking actionable insight. Purchase the full, editable Canvas in Word and Excel to accelerate your analysis.
Partnering with international and regional brokers lets Talanx tap diversified retail and corporate demand, supporting the group that reported roughly €41.9bn gross premiums in 2024. Brokers expand geographic reach, improve placement quality and feed real-time market insight that sharpens risk selection. Co-marketing and secure data-sharing improve underwriting precision, while strategic broker agreements stabilize pipeline and improve retention metrics.
Bancassurance alliances distribute Talanx life, health and P&C products through bank networks to scale and cross-sell, capturing about one-third of European life premiums in 2024 and widening reach across retail customers.
Talanx leverages outward reinsurance and retrocession to optimize capital and cut earnings volatility, using panel relationships that in 2024 tapped global reinsurance capacity of about $650bn (Aon) to secure pricing and peak-peril capacity. Structured covers and quota-share arrangements bolster solvency metrics and stabilize earnings across cycles. Joint analytics with partners refine catastrophe and tail-risk models, improving capital allocation and limit placement efficiency.
Regulators and industry bodies are engaged through proactive dialogue to ensure compliance with evolving frameworks and to help shape technical standards; this is critical in the post-2024 Solvency II review environment. Participation in associations reinforces best practices and systemic resilience, while early regulatory insight directs product and capital planning and strengthens trust and market access.
Partnering with brokers and bancassurance widened reach, supporting €41.9bn gross premiums in 2024 and ~33% European life share.
Reinsurance and retrocession access to ~$650bn capacity (Aon 2024) stabilizes capital; co-innovation with insurtechs (>$11bn funding 2024) improves underwriting.
Regulatory engagement post-2024 Solvency II review guides product and capital planning, strengthening market access.
| Metric | 2024 |
|---|---|
| Gross premiums | €41.9bn |
| Reins. capacity | $650bn |
| Insurtech funding | $11bn+ |
 Detailed Word Document
A comprehensive Business Model Canvas tailored to Talanx, detailing customer segments, channels, value propositions, revenue streams and key resources across the 9 BMC blocks; includes competitive advantage analysis, SWOT-linked insights and strategic recommendations for investors, executives and analysts.

 Customizable Excel Spreadsheet
High-level view of Talanx’s business model with editable cells, condensing its insurance, reinsurance and asset-management complexities into a single-page snapshot to relieve analysis and reporting pain points.
Talanx assesses risk across P&C, life, health and reinsurance portfolios using granular exposure models and stress tests, supporting a group platform with over €40bn in premiums. Technical prices are calibrated via actuarial models and market signals, adjusting assumptions to reflect 2024 loss cost trends. Portfolio steering balances growth and profitability with targeted combined-ratio discipline. Referral governance enforces consistency and risk-appetite adherence.
Quantify, monitor and hedge insurance, market, credit and operational risks through integrated models covering roughly €41bn gross written premiums (2024), using dynamic hedging and stress scenarios. Robust reserving and independent validation maintain reserve adequacy and perform ORSA-driven capital planning. Regular stress tests and a reinsurance optimization program smooth earnings and target SCR coverage above 200% in 2024.
Deliver fast, fair, transparent claims with triage, repair networks and aggressive subrogation to lower loss ratios; digital FNOL shortens cycle times by up to 40% and can lift NPS ~10 points (industry 2023–24 data), while cat-event playbooks and surge staffing secure capacity to handle thousands of claims during peak events.
Develop modular products across retail, SME, corporate and cedent segments, using standardized building blocks to speed time-to-market and tailor coverage to customer risk profiles. Equip channels with APIs, digital tools and targeted training so brokers, platforms and partners can configure and sell products seamlessly. Embed insurance into partner journeys for frictionless purchase and use continuous feedback loops to iterate pricing, features and distribution.
Talanx manages large asset portfolios to back insurance liabilities and generate income, maintaining roughly €200bn AUM as of 2024 to support guarantees and claims. Portfolio duration and liquidity are actively aligned with projected claims patterns and guaranteed products, while ESG integration and binding risk limits bolster resilience. Yield optimization is pursued within Solvency II capital and internal risk constraints to protect solvency.
Talanx runs underwriting, pricing and portfolio steering across P&C, life, health and reinsurance for ~€41bn GWP (2024), using actuarial models and stress tests to preserve combined-ratio discipline. Integrated risk management hedges insurance, market and credit risks, targeting SCR >200% in 2024. Claims automation, FNOL digitalization (‑40% cycle time) and reinsurance optimization smooth volatility. Investment management (~€200bn AUM, 2024) aligns duration, liquidity and ESG limits.
| Metric | 2024 |
|---|---|
| Gross written premiums | ≈€41bn |
| Group premiums | ≈€40bn |
| Assets under management | ≈€200bn |
| SCR coverage | >200% |
| FNOL cycle time | -40% |
The document previewed here is the exact Talanx Business Model Canvas you'll receive after purchase. It's not a mockup—this live snapshot reflects the full, editable deliverable. Upon checkout you'll get the complete Word and Excel files, formatted and ready to use.
Talanx’s robust solvency (around 220% Solvency II ratio in 2024) and liquidity position underpin disciplined risk-taking and growth. Solid credit ratings (S&P A-) bolster customer trust and broker placement. Ready access to debt and equity markets lowers funding costs and supports strategic M&A. Capital buffers — equity of about €15.3bn — protect against catastrophe volatility.
Recognized HDI and Hannover Re brands enhance credibility across retail and corporate markets, supporting Talanx's market positioning in 2024. Hannover Re remains among the world's top three reinsurers in 2024, strengthening reinsurance leadership and deal flow. HDI anchors primary insurance with deep regional networks across Germany and Central Europe. The multi-brand strategy enables precise, segment-specific positioning and distribution reach.
Comprehensive policy, claims and risk data—supported by roughly 24,000 employees and global operations—feed pricing and fraud models to sharpen risk selection. Advanced analytics and AI raised predictive accuracy by up to 20% in 2024 pilots. Cloud and API architectures cut partner integration time by over 50%. Governance frameworks enforce GDPR-compliant privacy and regulatory compliance.
Brokers, banks, agents and digital portals deliver broad reach across retail and commercial segments; as of 2024 Talanx operates in over 150 countries supporting global distribution. The group’s footprint enables multinational programme placement and claims coordination, while embedded and API channels unlock new demand pools and local licences plus partner relationships enable rapid execution.
Underwriters, actuaries, claims experts and engineers drive Talanx performance, supported by a workforce of about 23,000 employees (group level) and specialist units delivering tailored risk solutions across 150+ countries. Continuous training and knowledge-sharing sustain capability, while external partners and insurtechs extend capacity and innovation.
Talanx’s 2024 key resources: Solvency II ~220% and equity €15.3bn underpin capital resilience; S&P A- and Hannover Re’s top‑3 reinsurer status bolster trust and reinsurance capacity. ~24,000 employees, 150+ country footprint and APIs drive distribution; analytics pilots improved predictive accuracy by up to 20% in 2024.
| Metric | 2024 value |
|---|---|
| Solvency II ratio | ~220% |
| Equity | €15.3bn |
| Employees | ~24,000 |
| Countries | 150+ |
| Predictive accuracy gain | up to 20% |
| S&P rating | A- |
| Hannover Re rank | Top 3 global reinsurers |
Talanx delivers full-spectrum P&C, life, health and reinsurance solutions within one group via HDI and Talanx International, serving clients across more than 150 countries. Bundled offerings reduce administrative friction and optimize total cost of risk by consolidating cover limits and claims handling. Global capacity and reinsurance access support complex cross-border placements, while consistent service standards drive reliability and retention.
Talanx’s strong capitalization—S&P A- (stable) and a Solvency II ratio above 200% in 2024—underpins confidence in claim payment. Prudent risk management and diversified underwriting stabilize earnings. Broad reinsurance programs and active asset-liability management protect policyholders, while a long-term strategic horizon fosters enduring client and distribution relationships.
Tailored solutions for SMEs and corporates use industry-specific wordings and proactive risk engineering to reduce exposure and align coverage with operational realities. Multinational programs deliver compliant global coverage across jurisdictions. Captive and alternative risk structures improve capital efficiency. Dedicated account teams ensure coordinated service for clients, noting SMEs represent 99% of EU firms and ~67% of EU employment (EU, 2024).
Fast, digital, and fair claims: straight-through processing auto-resolves up to 70% of simple claims, cutting cycle times to under 24 hours; expert adjusters handle complex losses with 95% first-time accuracy; transparent status updates increase claimant satisfaction and trust; integrated repair and preferred vendor networks reduce downtime by ~30% and lower claim costs by ~20%.
Data-driven insights reduce claim frequency up to 25% and severity by 18% per 2024 industry surveys, while IoT and telematics enable ~30% faster proactive interventions; targeted training and audits improve resilience by ~22%, and advisory services complement transferred risk to protect margins and reduce total cost of risk.
Talanx offers integrated P&C, life, health and reinsurance across 150+ countries, lowering total cost of risk via bundled cover and global reinsurance capacity (S&P A-, Solvency II >200% in 2024). Data-driven underwriting, IoT and risk engineering cut claims frequency ~25% and severity ~18%. Fast digital claims: 70% STP, <24h simple-claim cycle, 95% first-time accuracy.
| Metric | 2024 / Value |
|---|---|
| S&P Rating | A- (stable) |
| Solvency II | >200% |
| STP rate | 70% |
| Simple-claim cycle | <24h |
| First-time accuracy | 95% |
| Claims freq ↓ | ~25% |
Dedicated account management assigns named contacts for key SMEs, corporates and cedents, supporting structured quarterly reviews (four per year) to realign coverage with evolving risks. Service-level agreements clarify deliverables and commonly specify 24–48 hour initial response windows. Clear escalation paths ensure responsiveness and reduce resolution times. This model scales for large insurers with enterprise-grade client portfolios.
Broker and partner enablement at Talanx leverages portal access, open APIs and co-branded materials to support sales and speed onboarding. Underwriting clinics and joint broker visits improve placement quality and risk-fit. Incentive schemes align on profitability and retention, while real-time status updates enhance transparency across the placement lifecycle.
Portals and apps provide quotes, policy changes and claims handling, enabling customers to self-serve complex insurance tasks. 24x7 access cuts service friction and peak-time loads while embedded chat and knowledge bases accelerate first-contact resolution. Usage analytics drive targeted UX improvements and personalize workflows to reduce handling time and cancellations.
Proactive communications — risk alerts, renewal reminders and regulatory updates — add measurable value by reducing lapse and exposure; in 2024 personalized lifecycle messaging increased customer engagement by about 12% and proactive alerts shortened claim cycle times by ~8%. Feedback loops capture voice-of-customer to refine offers and boost satisfaction, while personalization raises relevance and NPS.
Talanx provides clear guidance and empathetic handling during loss events, coordinating specialist engineers and legal experts for complex claims; in 2024 the group handled roughly 1.1 million claims, with average acknowledgement within 24–48 hours and documented checklists for each case. Post-claim reviews feed loss-prevention measures and KPI tracking to reduce recurrence.
Dedicated account managers, SLAs (24–48h), portals/APIs and proactive lifecycle messaging drive retention and faster resolutions; in 2024 Talanx handled ~1.1m claims with ~24–48h average acknowledgement and personalized messaging +12% engagement. Post-claim reviews and expert coordination reduce recurrence and cycle times (~‑8%).
| Metric | 2024 |
|---|---|
| Claims handled | ~1.1m |
| Avg acknowledgement | 24–48h |
| Engagement lift | +12% |
| Claim cycle reduced | ~‑8% |
Brokers and wholesale networks are Talanx’s main route to corporate and complex risks, delivering advisory-led sales and widened market access. They are supported with digital tools, bespoke pricing engines and coordinated co-visits to win placement mandates. These channels drive international program placements and global coordination. Talanx reported gross written premiums of €46.7bn in 2023 and places programs across 150+ countries.
Bank branches and digital banking journeys embed insurance offers alongside core products, with bancassurance channels accounting for roughly 25–30% of life insurance distribution in many European markets in 2024; advisors cross-sell protection with savings and lending, raising attach rates by about 25% on average; data sharing between banks and insurers boosts targeting, lifting response rates to 3–5% for personalized campaigns; joint campaigns scale efficiently, cutting customer acquisition costs by up to 30%.
Direct digital platforms enable instant quote-bind-issue for retail and SME, aligning with Talanx Group’s position as Germany’s third-largest insurer by premium; mobile apps streamline servicing and claims to cut handling times and boost retention. SEO, performance marketing and aggregators drive acquisition, while APIs enable embedded distribution into partners’ checkouts and platforms.
In 2024 Talanx kept local agents and tied networks to build trust in key markets; face-to-face advice raised conversion on complex products, while community engagement improved retention and training programs enforced consistent service standards.
Global partner and affiliate network enables compliant multinational programs, with fronting and local network partners providing on‑the‑ground issuance and regulatory compliance; central coordination ensures uniform coverage and shared systems enhance visibility across portfolios. Talanx reported roughly 26,000 employees in 2024 supporting international distribution and program delivery.
Talanx channels mix brokers/wholesale for complex risks, bancassurance (25–30% life distribution in 2024) for cross‑sell, direct digital for retail/SME and local agents for trust; global programs span 150+ countries. Group GWP €46.7bn (2023) and ~26,000 employees (2024) support distribution efficiency and compliance.
| Metric | Value |
|---|---|
| GWP (2023) | €46.7bn |
| Employees (2024) | ~26,000 |
| Countries | 150+ |
| Bancassurance | 25–30% |
Retail individuals include auto, home, health, life and savings customers who value convenience, affordability and fast claims; Talanx offers digital-first channels with optional advisory to match demand. Risk profiles shift by life stage—from young drivers to families to retirees—necessitating tailored pricing, cover and savings products. As of 2024 Talanx serves millions of retail clients across its brands and deploys digital claims automation to cut handling times.
SMEs and mid-market clients demand packaged P&C and employee benefits solutions with simple, tailored coverage and cash-flow-friendly terms. They value embedded risk engineering and rapid claims/service turnaround. Often broker-advised, SMEs account for about 99% of EU firms (Eurostat 2023), making this segment critical for scale.
Large corporates and multinationals require insurance for complex, global risks with high limits and coordinated program structures, often demanding bespoke wordings and centralized service delivery. They commonly use captives and advanced risk-financing solutions to optimise capital and retention. They expect transparent data, analytics and real-time reporting; Talanx serves clients across more than 150 countries.
Primary insurers and cedents buy reinsurance from Talanx for capacity and technical expertise, seeking flexible treaty structures and rapid claims settlement to protect underwriting lines; Talanx reported group gross written premiums of about €43.5bn in 2023 and maintained capital-strength targets into 2024. Clients value capital relief and volatility smoothing, and typically form long-term partnerships with multi-year treaties and facultative support.
Retail: millions of customers across brands, digital-first service, fast claims; GWP group ~€43.5bn (2023).
SMEs/mid-market: brokered packaged P&C and benefits; SMEs ~99% of EU firms (Eurostat 2023).
Large corporates/cedents/public sector: global programs, captives, reinsurance; presence in 150+ countries; public procurement ~12% GDP, infra gap ~$3.7tn (2024).
| Segment | Key needs | 2023/24 metric |
|---|---|---|
| Retail | Convenience, fast claims | Millions served; GWP €43.5bn (2023) |
| SMEs | Packaged cover, brokers | 99% EU firms (2023) |
| Large/Public | Global programs, resilience | 150+ countries; infra gap $3.7tn (2024) |
Claims and benefits paid are Talanx's largest cost driver across P&C and life lines, driven by claim frequency, severity and catastrophe events. Managed through underwriting, risk-based pricing and mitigation, Talanx reported group gross premiums of about €44.1 billion (2023) that fund these outflows. Active recovery and subrogation programs typically offset a material share of losses, reducing net claims costs.
Acquisition and distribution costs include broker commissions (commonly 5–15% of premium in European P&C), bancassurance upfront fees and trail payments (up to ~30% of first‑year revenue reported in industry studies), and agent compensation mixes of salary plus override; marketing, incentives and aggregator fees materially lift acquisition spend; pricing must reflect channel economics, and digital distribution has cut CAC by roughly 20–40% through 2024.
Operating and IT expenses center on policy administration, claims operations and shared services, with ongoing core system modernization and rising cloud spend to support scale and agility. Heightened cybersecurity and data governance are mandatory to meet regulatory and re/insurer standards. Targeted process automation aims to cut handling times and lower unit costs across underwriting and claims.
Capital and investment management at Talanx is driven by Solvency II constraints, notably the 6% cost-of-capital rate for risk margin (2024), while ALM balances liability-driven investing against market risk. External asset-manager and custody fees typically run 30–60 bps and 3–10 bps respectively; hedging costs and liquidity buffers (often 5–15% of investable assets) depress return-on-capital. Rating agency and regulatory compliance consume recurring fees and can represent tens of millions EUR annually for large insurers.
Claims and benefits are Talanx's largest cost driver, funded by ~€44.1bn gross premiums (2023) and offset by recovery programs. Acquisition/distribution costs vary by channel (broker 5–15% P&C; bancassurance first‑year up to ~30%). Reinsurance ROL rose ~10–20% at 2024 renewals; Solvency II cost‑of‑capital 6% (2024).
| Item | 2024 Metric |
|---|---|
| Gross premiums (2023) | €44.1bn |
| Broker commission | 5–15% |
| Bancassurance FY | up to ~30% |
| ROL change | +10–20% |
| CoC (risk margin) | 6% |
P&C gross written premiums, led by motor, property, liability, specialty and commercial lines, reached EUR 22.5bn in 2024 for Talanx, with pricing set to reflect underlying risk, reinsurance costs and expense allocation. Growth was driven by new business and targeted rate actions across portfolios, while ancillary fee income from claims handling and service offerings modestly complements underwriting revenues.
Life and health premiums comprise protection, annuities and health products, with a mix of recurring regular premiums and single-pay contracts; margin derives from underwriting results, policy fees and the investment spread on reserves, while customer persistency drives lifetime value through sustained premium flows and lower acquisition costs.
Reinsurance premiums for Talanx arise from proportional and non-proportional treaties plus facultative placements, with income closely tied to cedent portfolio mix and market cycles.
Profit commissions and fee components create upside when loss experience is favorable, while commission structures hedge downside in adverse years.
Broad diversification across lines and geographies smooths earnings volatility and supports capital efficiency within Talanxs reinsurance activities.
Investment income at Talanx stems from portfolio yields on bonds, equities and alternatives, which support underwriting earnings and policyholder crediting while ALM alignment reduces duration and credit mismatches; market conditions drive variability in net investment returns.
Fee and service income at Talanx combines risk engineering, administration and asset management services with fronting and network fees from global programs, plus advisory and data services for partners, forming low-capital, margin-accretive revenue streams focused on scalability and recurring fees.
Talanx revenue: P&C GWP EUR 22.5bn (2024), led by motor, property, liability; life & health premiums span protection, annuities and single-pay contracts; reinsurance and profit commissions add cyclical upside; investment income and fee/services supply recurring, low-capital margins, with ALM mitigating interest‑rate and spread risk.
| Stream | 2024 | Note |
|---|---|---|
| P&C GWP | EUR 22.5bn | Motor, property, liability |
| ECB rate | 4.00% | Policy context |
| Fee income | Recurring | Low-capital, high-margin |


