
Digital download
Access the files immediately after checkout.
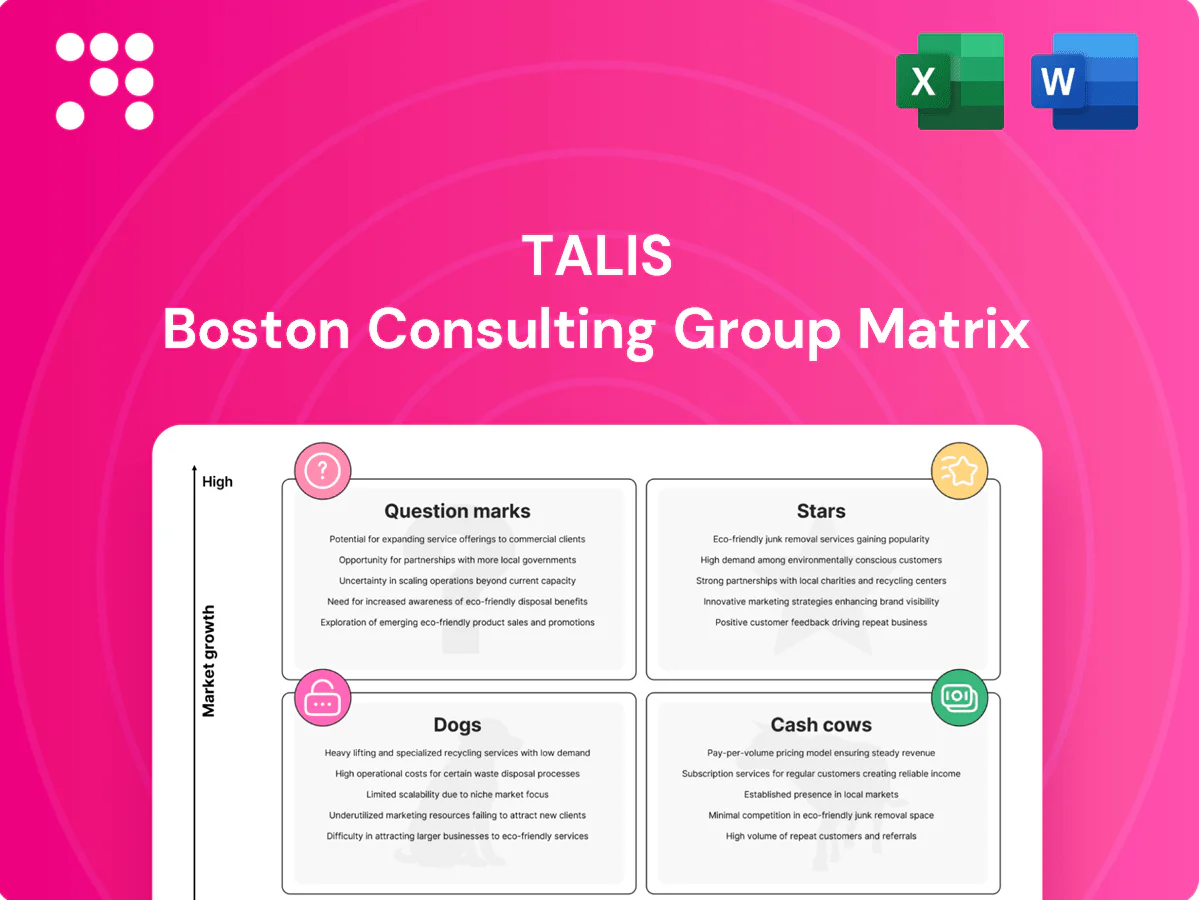
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Want a clear playbook for TALIS? This snapshot shows the shape of its portfolio—but the full BCG Matrix gives quadrant-by-quadrant placement, data-backed recommendations, and a ready-to-present Word report plus an Excel summary. Skip the guesswork: purchase the complete analysis to spot Stars to double down on, Cash Cows to harvest, Dogs to cut, and Question Marks to decide on—fast, practical moves you can act on today.
Exploding demand as utilities chase leakage reduction—non‑revenue water averages about 35% globally in 2024—driving rapid uptake of smart, IoT valve monitoring and real‑time visibility. TALIS’s strong installed base enables upsells of sensors and analytics, yielding meaningful share where deployed. Growth is high but cash‑intensive for R&D, integrations and pilots. Continue heavy investment to lock standards and convert scale into future cash cows.
Cities under 2024 pressure to cut non‑revenue water—often 20–60% of supply—are unlocking capital as UN‑Water/JMP notes 2.2 billion still lack safely managed water, pushing utilities to invest. TALIS’s engineered PRVs and controllers win on field-proven reliability, positioning it as a category leader. Projects are complex with long sales and heavy commissioning, so cash in equals cash out. Fund technical pre‑sales and reference sites to cement leadership.
Global capex in water treatment and key desal hubs is ramping, with GCC desal project awards near $25bn in 2024 and global desal capacity around 100 million m3/day. TALIS competes at the top end on specs and certifications, winning high‑value packages and sustaining premium pricing. Margins are solid (mid‑teens) but project working capital is chunky, tying up cash in long EPC cycles. Backlog is king — prioritize capacity expansion, QA, and strict project discipline to remain first call.
Advanced coatings and low‑lead potable valves are classified as Stars: tighter 2024 regulations make compliant valves must‑have, and TALIS’s portfolio meets stringent drinking‑water standards, winning premium municipal and industrial bids. Regional adoption accelerated in 2024, driving TALIS growth ~18% YoY versus a ~7% market gain; keep funding certification, audits, and rapid variant releases to stay ahead.
Integrated valve-control skids are Stars in TALIS BCG Matrix: EPCs in 2024 demand packaged, factory-tested assemblies to de-risk sites, and TALIS bundles valves, actuators, controls and full documentation with reported win rates ~65% in 2024. High-growth, engineering-heavy segment shows attractive ticket sizes ($150k–$1.2M) and projected CAGR ~7% through 2029. Invest in modular designs and expand factory FAT capacity to scale without margin creep.
Stars: high-growth, cash‑intensive segments—IoT valves, low‑lead potable, integrated skids—driving share and premium wins in 2024; focus on certification, FAT capacity, modular R&D to convert scale into future cash cows.
| Metric | 2024 |
|---|---|
| Share (low‑lead tenders) | >30% |
| YoY growth TALIS / market | ~18% / ~7% |
| Win rate (skids) | ~65% |
| Ticket size | $150k–$1.2M |
| Margins | Mid‑teens |
 Detailed Word Document
Concise TALIS BCG Matrix overview: evaluates units as Stars, Cash Cows, Question Marks, Dogs with strategic investment guidance.

 Customizable Excel Spreadsheet
One-page TALIS BCG Matrix mapping units into quadrants—export-ready for quick slides and clean C-level presentation.
Standard fire hydrants in mature markets sit in stable regulatory frameworks with replacement cycles around 40 years, driving predictable annual demand; TALIS units are widely approved and trusted by utilities and fire departments. Cash generative with steady margins, these products need modest R&D focused on materials and coatings. Maintain certifications, optimize SKUs, and defend price to protect cash flow.
Check valves and baseline fittings are evergreen components bundled into the majority of TALIS projects and remained core cash cows in 2024, with sales volume steady despite flat growth. Where TALIS is already approved, share is durable and aftermarket demand supports recurring revenue. Flat market growth but consistent project scale keeps gross margins healthy. Prioritize cost, availability, and strategic bundling to protect the installed base.
Aftermarket spares and service of TALIS deliver recurring revenue with low churn and high gross margins, typically 40–60% in industrial aftermarket segments (2024 industry range). TALIS’s installed-base footprint, serial documentation and O&M records create a durable moat; growth is limited by installed units rather than market hype. Standardize contracts, pre-packed parts kits and maintain sub-48h response SLAs to protect margin.
Manual and standard electric actuators are well known, reliable, and spec‑compatible, forming TALIS cash cows that generate steady aftermarket revenue; commodity actuators show low growth (industry CAGR ~3% as of 2024) but deliver consistent cash on every maintenance cycle, so prioritize cost leadership and attach rates over feature bloat.
Cash cows: mature valves, hydrants, actuators and spares deliver predictable, high-margin cash flow (production margins mid‑20s to mid‑30s; aftermarket 40–60% in 2024), low growth (~3% CAGR for commodity actuators) and durable share via installed base. Focus on cost leadership, SKU rationalization, service SLAs and attach rates to defend margins and cash generation.
| Item | 2024 Metric | Notes |
|---|---|---|
| Valves | GM 25–35% | Long replacement cycles |
| Aftermarket | GM 40–60% | Recurring revenue |
| Actuators | CAGR ~3% | Low growth, high attach |
The file you’re previewing is the exact TALIS BCG Matrix you’ll receive after purchase—no placeholders, no watermarks, no demo fluff. It’s fully formatted and analysis-ready, built for immediate editing, printing, or pitching to stakeholders. After purchase the same document is delivered directly to your inbox, ready to plug into planning sessions or investor decks. No surprises—just a polished, market-informed strategic tool that’s yours to use.
Regulatory headwinds (EU RoHS restrictions and growing US/CA toxic-chem rules) and customer risk aversion make legacy lead-bearing variants a drag; where still allowed they represent under 5% of shipments and are shrinking universally. Cash is trapped in niche runs and excess inventory; plan an expedited sunset and material substitution and avoid allocating turnaround CAPEX to sustaining these SKUs.
Ultra‑custom one‑off specials consume disproportionate engineering time—industry cases report 1–3% of SKUs using 25–40% of engineering hours—while repeatability is near zero and aggregate market share is by definition negligible with no growth trajectory. On paper gross margins can appear healthy (mid‑30s%), yet cash conversion turns negative (real‑world FCF impact often -3% to -7%), forcing SKU pruning, minimum order enforcement, or exit.
Utilities are standardizing on open, secure stacks; 2024 industry surveys report about 72% adoption of open architectures in grid telemetry, leaving obsolete closed‑protocol add‑ons noncompetitive. These legacy modules neither scale nor integrate, so field adoption is minimal and churn rates exceed 60% in pilot programs. Support costs persist—often 10–15% of legacy product revenue—without meaningful returns; migrate customers or discontinue.
Commodity small‑diameter fittings faced intensified price wars in 2024, eroding margins and brand value as buyers treated products as pure commodities; market share remained weak and volume gains were short‑lived. Turnaround efforts burned cash with minimal payoff, prompting moves to divest or focus on protected, spec’d niches.
Dogs: Aging product lines without certification refresh lose approvals and thus bids, accelerating market share erosion as the market is flat-to-declining and incumbent share drops each year. Carrying these SKUs ties up working capital and increases fixed costs; retire and redeploy resources to growth products to improve ROI and bid competitiveness.
Dogs: legacy SKUs <5% of shipments in 2024, facing EU/US regulatory squeeze; support costs 10–15% of legacy revenue, pilot churn >60% and open‑stack adoption 72%—margins appear mid‑30s but FCF drag -3% to -7%. Retire noncertified lines, stop turnarounds, redeploy working capital to winners.
| Metric | 2024 | Action |
|---|---|---|
| Legacy share | <5% | Sunset |
| Support cost | 10–15% | Cut |
| Pilot churn | >60% | Divest |
Smart hydrants are a Question Mark: global smart water market ~$5B in 2024 with ~12% CAGR, so growth is large while TALIS’s share remains early‑stage. Hardware is proven; integration and data UX need refinement. Pilots are cash‑hungry and cybersecurity adds cost. Strategy: double down where utilities pay for analytics or partner to scale fast.
Plant upgrades are rising as the global wastewater treatment market was about $40 billion in 2024 with ~6% CAGR, yet specs remain fragmented and incumbents are entrenched. TALIS has strong valve tech but limited references in high solids/cavitation duty. This is a high-growth, low-share Question Mark. Invest aggressively in application engineering and 2–3 marquee case studies or pivot to niches where win rates exceed 30%.
Industrial water packages for food, pharma and data centers sit in Question Marks: market ~USD 35B in 2024 with ~6% CAGR, capex rising and procurement cycles lengthening; qualification can take 6–12 months. TALIS’s potable credibility opens doors but buyers demand lifecycle analytics and 99.99% uptime SLAs. Opportunity is real, share is not yet—build vertical playbooks, co‑sell with OEMs and kill scattershot bids.
District metered area analytics sits in Question Marks: utilities demand outcome tools not dashboards, and TALIS has some modules but a small platform footprint; global non‑revenue water averages ~30% in 2024, driving urgent utility ROI requirements. Cash burn for product, integrations and 24/7 support is non‑trivial versus projected smart water market scale (~USD 10B in 2024). Either partner/white‑label to scale quickly or concentrate on valve‑centric analytics we can own and monetize faster.
Rapid urbanization in emerging markets (urban share ~55% in 2024) creates strong demand for modular PRV stations, yet route-to-market friction and an estimated infrastructure financing gap near 2.5 trillion USD/year slow adoption. TALIS designs are technically competitive, but local assembly and after-sales service depth remain inconsistent across target countries. Cracking delivery models and competitive price points can unlock a long growth runway; recommend pilots with EPCs, deeper localization, or exit low-margin tenders.
Question Marks: high-growth segments (smart water ~USD10B, wastewater ~USD40B, industrial water ~USD35B in 2024) where TALIS has tech but low share; NRW ~30% (2024) drives urgency. Strategy: partner/white‑label, localize, or double down on valve‑centric analytics and marquee pilots to reach profitable scale.
| Segment | Market 2024 | CAGR | TALIS position | Action |
|---|---|---|---|---|
| Smart hydrants | 10B | ~12% | Early | Partner/scale |
| Wastewater upgrades | 40B | ~6% | Low refs | Case studies |
| Industrial packages | 35B | ~6% | Credibility | Vertical playbooks |
| DMA analytics | - | - | Small footprint | White‑label/focus |
| PRV stations | - | - | Competitive | Localize/EPC pilots |


