
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
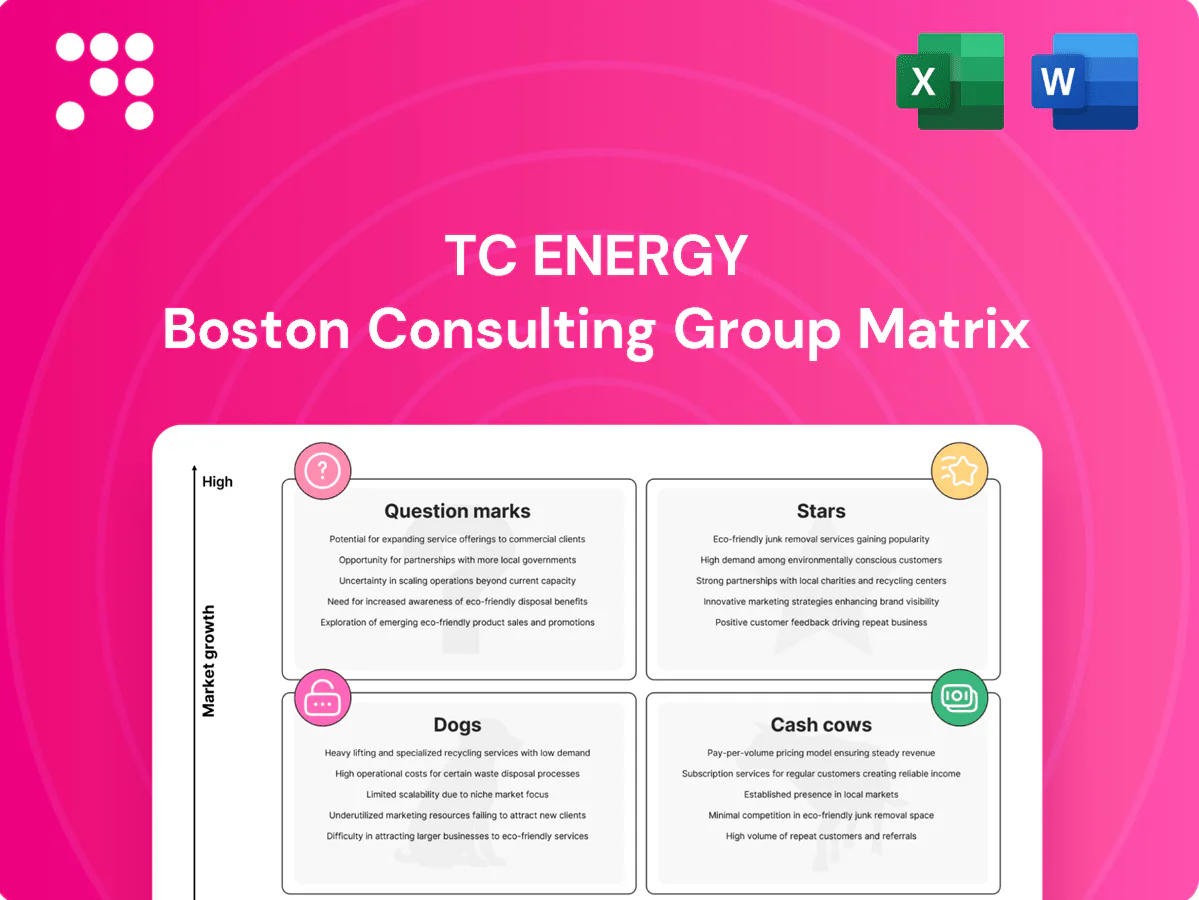
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where TC Energy’s assets sit — Stars, Cash Cows, Dogs, or Question Marks? This preview sketches the contours, but the full BCG Matrix maps every business line with hard data and clear strategic moves. Buy the complete report to get quadrant-by-quadrant placement, actionable recommendations, and downloadable Word + Excel files you can use in board decks or investor briefs. Get instant access and stop guessing where to invest or conserve capital.
Continental gas pipeline backbone: as of 2024 TC Energy operates roughly 57,500 km of pipelines, holding high market share moving natural gas across North America where regional demand remains firm. Mission-critical, first-call capacity attracts premium shippers and sustains strong utilization and stable tolls. The system generates significant cash but demands ongoing capex to expand and modernize; continue investing to defend share and transition toward Cash Cow status.
Export-driven gas flows are ramping — US LNG nameplate capacity reached about 13.5 Bcf/d in 2024 — and TC Energy sits on the main corridors feeding Gulf Coast terminals and Mexico demand centers, securing strong share while competitors are slower to build.
Growth is real and cash-in equals cash-out as expansions, compression and interconnect projects keep stacking up, funded by steady pipeline cash flow and contracts.
Double down while the market is hot.
Integrated storage plus pipeline clearly slots TC Energy as a leader: high utilization and pipeline-linked delivery near load centers create sticky customers and margin resilience. EIA reports North American working gas capacity near 4,400 Bcf in 2024, and rising price volatility this year increases payoffs for flexibility that TC can price. Invest to scale storage, secure multi-year contracts, and monetize transmission-storage spreads.
Regulated transmission with premium reliability positions TC Energy as a Star: brand reputation and a reported 99.99% uptime in 2024 drive contract wins in high-growth corridors, while regulatory visibility underpins permitted returns despite rising input costs. The company guided roughly CAD 4.0 billion in 2024 capex focused on integrity and capacity to sustain network leadership.
Industrial + utility anchor contracts are long-dated ship-or-pay agreements with blue-chip counterparties securing dominant shares in expanding basins and load pockets. As gas displaces coal and supports renewables, contracted volumes trend upward and revenues recycle into targeted growth capex. Maintain renewal cadence and add lateral connections to entrench position.
Continental backbone (≈57,500 km) holds high market share and strong utilization. Export corridors (US LNG ≈13.5 Bcf/d) plus storage (working gas ≈4,400 Bcf) drive growth while CAD 4.0B capex and 99.99% uptime sustain network leadership. Long-dated ship-or-pay contracts secure cash flows; invest to convert Star into Cash Cow.
| Metric | 2024 |
|---|---|
| Pipelines (km) | ≈57,500 |
| US LNG capacity (Bcf/d) | ≈13.5 |
| Working gas (Bcf) | ≈4,400 |
| Uptime | 99.99% |
| Capex (CAD) | ≈4.0B |
 Detailed Word Document
BCG Matrix review of TC Energy: categorizes units into Stars, Cash Cows, Question Marks, and Dogs with clear investment guidance.

 Customizable Excel Spreadsheet
One-page TC Energy BCG Matrix easing portfolio decisions, spotlighting stars and dogs for faster executive action
Mature legacy gas mains in stable markets deliver high share, low growth cash flows with dependable tolls and minimal promotion, generating steady opex and strong cash conversion that underpins debt service and new-build funding; TC Energy’s 2024 capital program of CAD 4.7 billion illustrates reinvestment capacity. Optimize throughput and squeeze cost per mile to preserve margins and free cash for servicing obligations and growth.
Established liquids pipeline systems like Keystone (590,000 bpd capacity) deliver stable volumes with modest growth, and TC Energy maintains durable market positions across core corridors. Long‑term tolling and take‑or‑pay contracts sustain healthy margins and predictable cash flow. Capex is largely maintenance and integrity spend rather than major expansions, supporting a milk‑the‑asset approach while keeping integrity spend tight.
Long-term ship-or-pay portfolios provide contracted capacity that cushions commodity cycles and ensures steady cash inflows, supporting TC Energy’s broad pipeline network of roughly 92,000 km across North America. Growth is limited while churn remains low and credit remains investment-grade, making these assets ideal for funding R&D, corporate overhead, and selective growth bets. Management should prioritize renewals and upselling ancillary services to extract incremental margin and preserve cash generation.
Where PPAs or regulated returns are in place, cash flow is steady and predictable; PPAs commonly run 10–25 years and anchor revenue despite tepid market growth and limited upside. Margins are established, so operational focus is on heat-rate improvements and maximizing uptime; excess cash is deployed as a backstop for new ventures. In 2024, 10-year sovereign yields sat near 4%, supporting contract valuations.
Compression and maintenance services are embedded, non-glamour work that runs daily across TC Energy’s extensive network, which spans about 92,000 km of pipelines; margins are solid while organic growth is low and customer switching is rare. Efficiency upgrades and predictive maintenance lift cash conversion with limited incremental capital, so keep operations lean, reliable and highly predictable.
Mature gas mains and liquids pipelines generate high-share, low-growth cash flows with strong cash conversion, funding debt service and selective growth; 2024 capital program CAD 4.7B. Keystone capacity 590,000 bpd and TC Energy network ~92,000 km underpin durable tolling and ship-or-pay contracts. Focus: maximize throughput, cut cost per mile, prioritize renewals and maintenance.
| Metric | Value |
|---|---|
| 2024 capital program | CAD 4.7B |
| Network length | ~92,000 km |
| Keystone capacity | 590,000 bpd |
| 10y sovereign yield (2024) | ~4% |
The TC Energy BCG Matrix you’re previewing here is the exact file you’ll receive after purchase. No watermarks, no placeholders — just the final, fully formatted strategic report ready for action. It’s designed for clarity, built on market-aware analysis, and immediately downloadable. Use it in investor decks, board meetings, or internal planning without edits. Buy once, get the production-ready document delivered to your inbox.
Small, non-core pipeline laterals in declining basins have low market share in shrinking supply areas and, per TC Energy disclosures in 2024, represent only a minor portion of system EBITDA, tying up capital without materially moving company performance. Turnarounds are costly with low probability of significant uplift, often prompting pruning, targeted sales, or mothballing to stem cash burn.
Permitting-stalled projects accrue interest and overhead while policy rates hovered near 5% in 2024, accelerating carrying costs and capital drag for TC Energy assets. Delays allow market momentum to pass them by, eroding future returns so that even eventual success may only break even. Best pragmatic answer is exit or restructure to stop ongoing value destruction.
Marginal liquids gathering/feeder lines are Dogs for TC Energy: in 2024 they rely on volatile local producers with fragmenting share, offering little pricing power while facing rising maintenance and environmental compliance costs. These assets act as cash traps rather than contributors to enterprise value. Management should evaluate targeted divestment packages to reallocate capital to higher-growth, higher-margin pipelines.
Aging power units without firm contracts expose TC Energy to merchant risk in flat markets, contributing to low market share and minimal growth; by 2024 the segment accounted for under 5% of consolidated EBITDA, pressured by stagnant wholesale prices. Ongoing maintenance and compliance consumed disproportionate cash flow, with rehab costs often exceeding expected incremental returns. Retirement or sale of these units aligns with capital reallocation to core pipelines.
Stranded storage or terminals away from demand hubs depress utilization and margins as competing sites nearer load routinely capture volumes; capital tied in low-turn assets drags TC Energy’s ROIC and prompts reallocation decisions.
Small non-core laterals and marginal gathering lines are low-share, low-growth Dogs: <5% of TC Energy 2024 EBITDA, high maintenance and limited pricing power.
Permitting delays and ~5% policy rates in 2024 raised carrying costs, turning stalled projects into cash drains.
Recommendation: targeted divest, mothball, or retire to redeploy capital to core pipelines.
| Metric | 2024 |
|---|---|
| EBITDA share | <5% |
| Policy rate | ~5% |
| Maintenance trend | Upward |
| Preferred action | Divest/mothball/retire |
Carbon capture and CO2 transport corridors show high growth potential but TC Energy’s market share is still forming as it develops corridor proposals. Policy tailwinds are strong: US 45Q tax credit up to US$85/ton and IRA funding bolster economics, while global CCS capacity was ~40 MtCO2/yr in 2023 (Global CCS Institute). Projects are capital-hungry (often >US$1bn) with uncertain throughput; could scale into a Star if anchor shippers land, so commit selectively or partner to de-risk.
Everyone’s exploring hydrogen-ready conversions across TC Energy’s network of about 92,000 km of pipelines (2024), yet few shippers report material hydrogen volumes today. Engineering appears feasible for blends and retrofit, while economics and regulation remain TBD and hinge on standards and demand crystallization. First movers who pilot now and secure firm offtake agreements will capture value when markets scale.
Renewable natural gas interconnects sit in a fast-growing but small market—global biomethane was valued around USD 7.8 billion in 2023 with ~14% CAGR projected to 2030—while TC Energy’s share is still early-stage. Interconnects can be sticky, yet feedstock is highly fragmented, so scale and aggregation matter. Returns will hinge on incentives and feedstock aggregation; pursue clustered investments or step back.
Grid-scale storage co-located at TC Energy pipeline nodes is an attractive adjacency to serve peaking and flexibility, but TC’s storage footprint is nascent relative to its ~57,500 km pipeline network (2024). Revenues can be lumpy and depend on evolving market rules and capacity markets. With the right long-term PPAs and firming contracts this segment could scale quickly. Pursue co-located projects with contracted cash flows to de-risk returns.
Customers increasingly seek flow flexibility and real-time transparency, and demand for capacity products is rising; TC Energy, operating roughly 92,600 km of pipelines in 2024, sits on a large physical backbone but currently holds low share in digital/flex offerings because these products are new and evolving. Low incremental capex makes pilots attractive: build, test, price, then scale fast if uptake persists.
Carbon capture corridors, H2-ready conversion, biomethane interconnects and co-located storage show high-growth potential but TC Energy’s share is nascent; CCS ~40 MtCO2/yr (2023), 45Q up to US$85/t, projects >US$1bn. Pilot selectively, secure anchor shippers/PPAs and partner to de-risk; digital FLEX pilots have low capex and rapid scale potential.
| Segment | 2023/24 metric | Key lever |
|---|---|---|
| CCS | 40 MtCO2/yr; 45Q US$85/t | anchor shippers |
| H2-ready | 92,600 km pipelines (2024) | firm offtake |
| Biomethane | US$7.8bn (2023); ~14% CAGR | feedstock aggregation |


