
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
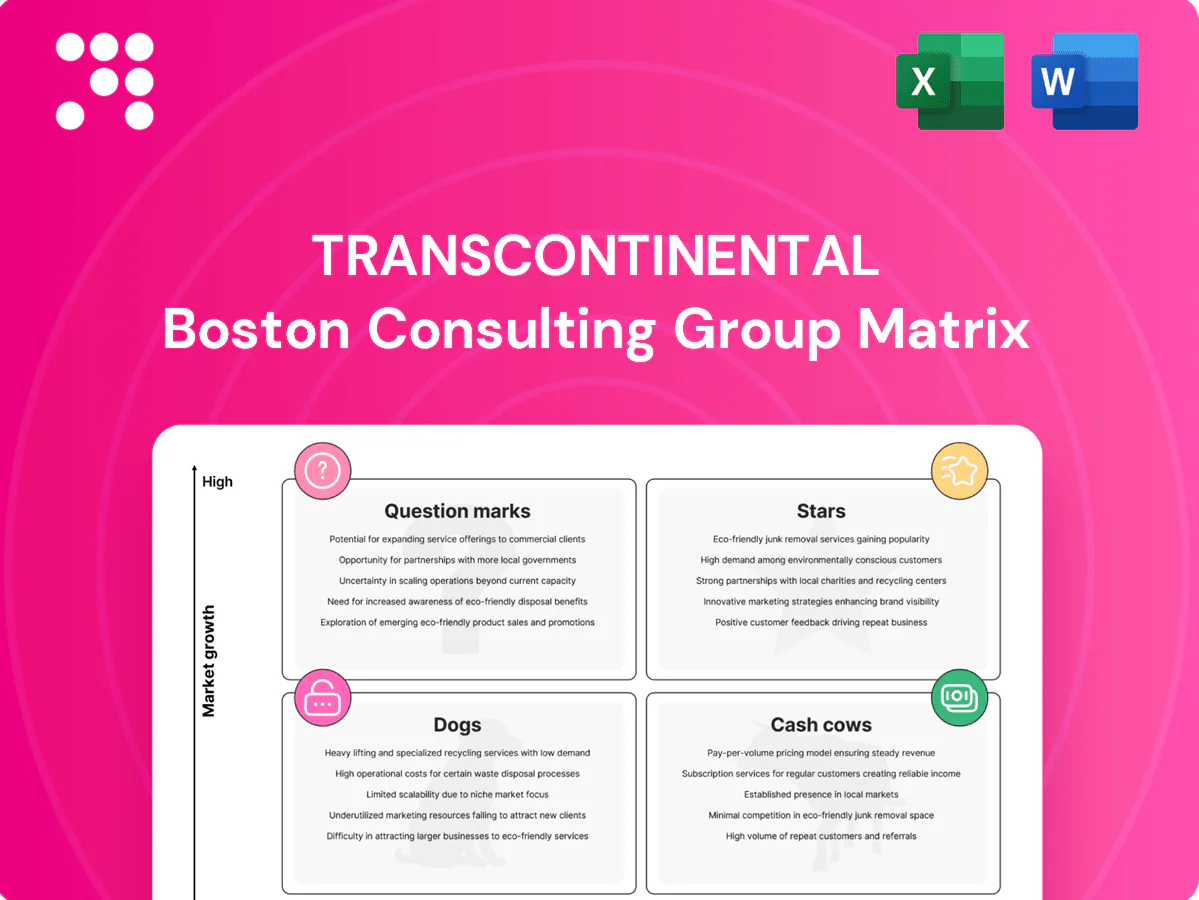
Transcontinental’s BCG Matrix cuts through the noise—showing which divisions are Stars, Cash Cows, Dogs, or Question Marks so you can stop guessing and start acting. This snapshot highlights where growth and cash collide, but the full report gives quadrant-by-quadrant evidence and practical moves. Purchase the complete BCG Matrix for a Word report and Excel summary with clear, data-backed recommendations you can use today.
Food & beverage flex-pack is a high-growth end market where Transcontinental leverages real scale and long-standing relationships with major CPGs, showing strong share across pouches, lidding and films while volumes continue compounding.
The segment soaks up cash for capacity expansion, innovation and service, yet the operational flywheel converts investment into improving margins and customer lock-in.
Maintain investment to defend share and capture market expansion, transitioning the business toward Cash Cow status as scale and recurring volumes mature.
Regulatory tailwinds and retailer mandates are driving strong growth in sustainable mono-material and recyclable films, with 2024 seeing accelerated spec requirements across North America and Europe. TC is early to market with recyclable PE structures and PCR content, securing specification wins with major brands. Margins remain solid but elevated R&D and line upgrade CAPEX pressure cash flow in the short term. Recommend doubling down to lock specs and capture first-to-scale advantage.
High-barrier engineered packaging sits in Stars: premium niches (fresh, frozen, pet, specialty) grew ~6–8% in 2024 versus ~2–3% for base SKUs, and TC’s coatings, multilayer and barrier know‑how create a durable moat; customers routinely accept 10–20% price premia for performance. Rising demand plus TC’s 2024 capital allocation to barrier R&D and rapid scale-up speed-to-commercial should cement leadership.
Stars: Long-term CPG programs & conversions — brand owners are shifting rigid to flexible packaging in a secular growth wave; TC’s platform is positioned to capture multi-year conversions with strong stickiness. Programs need upfront tooling and qualification dollars; invest through the ramp and retention typically converts spend into annuities in 2–3 years.
Integrated prepress-to-pack services position Transcontinental as a Star by winning growth-account bids through end-to-end color management, design, and short-run agility; in 2024 this approach accelerated onboarding and cut proof-to-press cycles by measurable days across accounts. It boosts speed, reduces errors, and embeds TC into customer workflows, differentiating the bundle in a crowded market and supporting revenue momentum (TC reported ~CAD 2.5B annual revenue in 2023).
Food & beverage flex-pack and engineered barrier packaging are Stars: high-growth (segment +7–8% in 2024), strong share gains, and sticky CPG programs converting to annuities in 2–3 years. TC’s recyclable PE, barrier R&D and prepress-to-pack bundle drive specification wins but keep near-term CAPEX elevated.
| Metric | 2023 | 2024 |
|---|---|---|
| Company revenue | CAD 2.5B | ~CAD 2.7B |
| Star segment growth | 6% | 7–8% |
| Incremental CAPEX | — | ~CAD 150M |
 Detailed Word Document
Comprehensive BCG Matrix review of Transcontinental's units, showing Stars, Cash Cows, Question Marks and Dogs with investment guidance.

 Customizable Excel Spreadsheet
One-page Transcontinental BCG Matrix pinpointing portfolio pain points and clear growth levers.
Canadian large-format retail and book printing is a mature market where Transcontinental holds a leading position (estimated market share around 40%), with stable-to-slightly-down volumes (~1–2% annual decline) but high plant utilization (circa 80–90%) and tight cost discipline generating strong free cash flow. Capex needs for printing are modest versus packaging (printing capex roughly CAD 20–40m annually versus packaging higher), so the business consistently funds operations and dividends while pruning SKUs and optimizing runs to milk cash.
Premedia and distribution in Canada hold a high share of Transcontinental’s print services with sticky client relationships and predictable repeat work; Transcontinental reported roughly CAD 2.0 billion in revenue in 2024, with print/related services a stable contributor. Growth is muted but margins remain resilient due to process depth and scale, needing low incremental investment, freeing cash to fund packaging growth bets.
French-language K–12 backlist is a defensible niche in Quebec (population ~8.7 million in 2024) servicing roughly 1.1 million K–12 students, enabling steady adoption cycles and strong brand trust. Growth is low, but backlist and recurring adoptions generate reliable cash flow. Working capital stays manageable through disciplined print runs and inventory turns. Strategy: maintain core titles, refresh selectively, harvest excess cash.
In-store marketing and specialty print programs are not explosive but reliably awarded by large retailers and CPGs; in 2024 TC continued to convert renewals into steady revenue streams, sustaining strong plant utilization and low per-unit costs.
TC’s North American footprint and integrated logistics keep costs down and SLAs tight, driving predictable cash generation with limited incremental capex and positive operating cash flow in the print segment during 2024.
Maintain high utilization and bundle these offerings with premedia services to defend share, cross-sell higher-margin creative services, and preserve conversion economics against digital substitution.
Catalogs and transactional print sit in a mature segment for Transcontinental with stable, long-term contracts delivering predictable cash flow; in 2024 the business continued to contribute roughly CAD 300M in annual revenues with limited volume growth but strong margin stability.
Low innovation burden allows focus on pricing and capacity optimization to maximize cash yield, with consistent overhead absorption and predictable free-cash-flow contribution despite limited upside.
Transcontinental’s Canadian print cash cows (≈40% market share) deliver steady free cash flow with high utilization (80–90%) and low capex (printing CAD20–40m vs packaging higher). Print-related revenue stayed ~CAD2.0B in 2024 with catalogs/transactional ≈CAD300M; K–12 Quebec backlist serves ~1.1M students, providing recurring cash. Strategy: sustain utilization, bundle premedia, and harvest excess cash.
| Metric | 2024 |
|---|---|
| Group revenue | CAD2.0B |
| Print rev (catalogs) | ≈CAD300M |
| Print capex | CAD20–40M |
| Plant util. | 80–90% |
| QC K–12 students | ≈1.1M |
The Transcontinental BCG Matrix you’re previewing here is the exact final file you’ll receive after purchase. No watermarks, no demo text — just a fully formatted, analysis-ready report built for strategic clarity. Buy once, download immediately, and start editing or presenting to stakeholders right away. It’s the real document, crafted for practical use across planning, pitches, and portfolio reviews.
Newsprint and legacy magazine volumes face structural decline as global print ad spend slid further in 2024, with newspapers and magazines representing roughly 9% of total ad spend, compressing revenues and prompting format exits. Low market share in remaining demand and severe price pressure leave thin margins while tying up presses and labor. Operational capital is immobilized in low-return assets; divest, consolidate, or sunset capacity quickly to stem losses.
Retail flyers face structural decline as retailers shift to digital and app-based promotions, with flyer volumes down roughly 15% year-on-year in 2024 while digital coupon and app engagement reached ~60% of promotion interactions; pricing pressure has driven per-unit margins into the low single digits. High changeover and waste make flyers a cash trap; exit low-margin segments and retain only strategic accounts with firm margins.
Small commercial print jobbing is highly fragmented, commoditized and bid-driven with Transcontinental holding no material share in this subsegment and average job-level margins often at break-even due to overhead and setup costs. Industry print volumes declined about 2–4% in 2023–24, intensifying price pressure. Recommend culling SKUs, closing underperforming presses/cells or outsourcing to consolidate fixed costs.
Underutilized regional print plants show fixed costs outweigh local demand: in 2024 average utilization sat near 50%, cutting margins by roughly 400 basis points; capital yields in packaging (~12% ROI) materially outpace print (~5%), so redeploying capex makes more sense than sustaining low-volume plants.
Non-core industrial packaging SKUs are commodity film lines lacking spec lock and delivering price-only competition with volatile resin pass-throughs, eroding margin and positioning them as Dogs in Transcontinental’s BCG matrix.
They account for low share of portfolio (<5% of packaging volumes) and bring minimal strategic value; rationalize the tail and redeploy lines to higher-value, structured multilayer or coated formats to uplift profitability.
Non-core commodity film lines are Dogs: <5% of packaging volumes, heavy price competition and volatile resin pass-throughs compress margins. Print assets underperform—packaging ROI ~12% vs print ~5%, regional plant utilization ~50% in 2024 cutting margins ~400 bps. Exit, sell or redeploy to structured multilayer/coated formats.
| Metric | 2024 | Impact |
|---|---|---|
| Portfolio share | <5% | Low strategic value |
| Flyer decline | -15% y/y | Low margins |
| Ad spend (news/mag) | ~9% | Revenue squeeze |
| Plant util | ~50% | -400 bps margins |
| ROI | Packaging 12% vs Print 5% | Redeploy capex |
Healthcare and pharma flexible packaging is high-growth, regulated and margin-rich (industry EBIT margins often 10–15%), but TC’s share remains modest versus market leaders. Qualification cycles typically run 12–24 months and are costly; won accounts are sticky 5–7 years. Invest in ISO cleanrooms, FDA/EMA certifications and scalable CAPEX to capture long-term contracts.
Schools are shifting budgets to digital learning as the global EdTech market reached about US$252 billion in 2024, with Francophone K‑12 demand rising in Quebec and France. TC has deep French‑language content but limited platform scale and low adoption, and monetization models are still nascent. The strategic choice is clear: build or buy a robust platform and sell hard to capture share, or partner fast with an established LMS to accelerate reach and revenue.
Direct-to-consumer brands demand lightweight, protective, brandable ready-to-ship formats and expect quick-turn, small-batch runs with data-driven artwork to personalize packs. E-commerce now represents about 21% of global retail sales (2024, eMarketer), fueling hot DTC growth while Transcontinental’s share in DTC flexible formats remains emerging and fragmented. Pilot dedicated cells with rapid SKU changeover and target lighthouse DTC logos to build credibility and scale.
Recyclable paper-flex hybrids sit as Question Marks for Transcontinental: consumer demand for paper-look packaging with barrier properties grew in 2024 as the flexible packaging market reached about 127 billion USD with a ~4.6% CAGR, yet materials and specs are still evolving. TC runs pilots but lacks category dominance and must scale R&D and co-development with retailers to set specs. Invest selectively with anchor customers to secure early standards and capture share before commodity entrants move in.
Advanced digital print for packaging is a Question Mark in Transcontinental’s 2024 BCG matrix: short runs, versioning, and speed-to-shelf demand are accelerating, driven by e-commerce and promotional cycles. TC’s digital footprint is developing across North America and Europe but is not market-leading in 2024. Economics depend on workflow automation and ink/laminate unit costs; targeted capacity plus integrated workflows can convert growth into profitability.
Question Marks: multiple high-growth pockets (healthcare packaging, EdTech, DTC, recyclable hybrids, digital print) where TC has modest share; invest selectively in certifications, scalable CAPEX, platform or M&A, and anchor-customer co‑dev to convert growth into profitable scale.
| Segment | 2024 size | CAGR | TC position | Action |
|---|---|---|---|---|
| Flexible pharma | part of 127B | — | modest | ISO/FDA certs |
| EdTech | 252B | — | limited | build/buy |
| DTC | 21% retail | — | emerging | pilot cells |


