
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
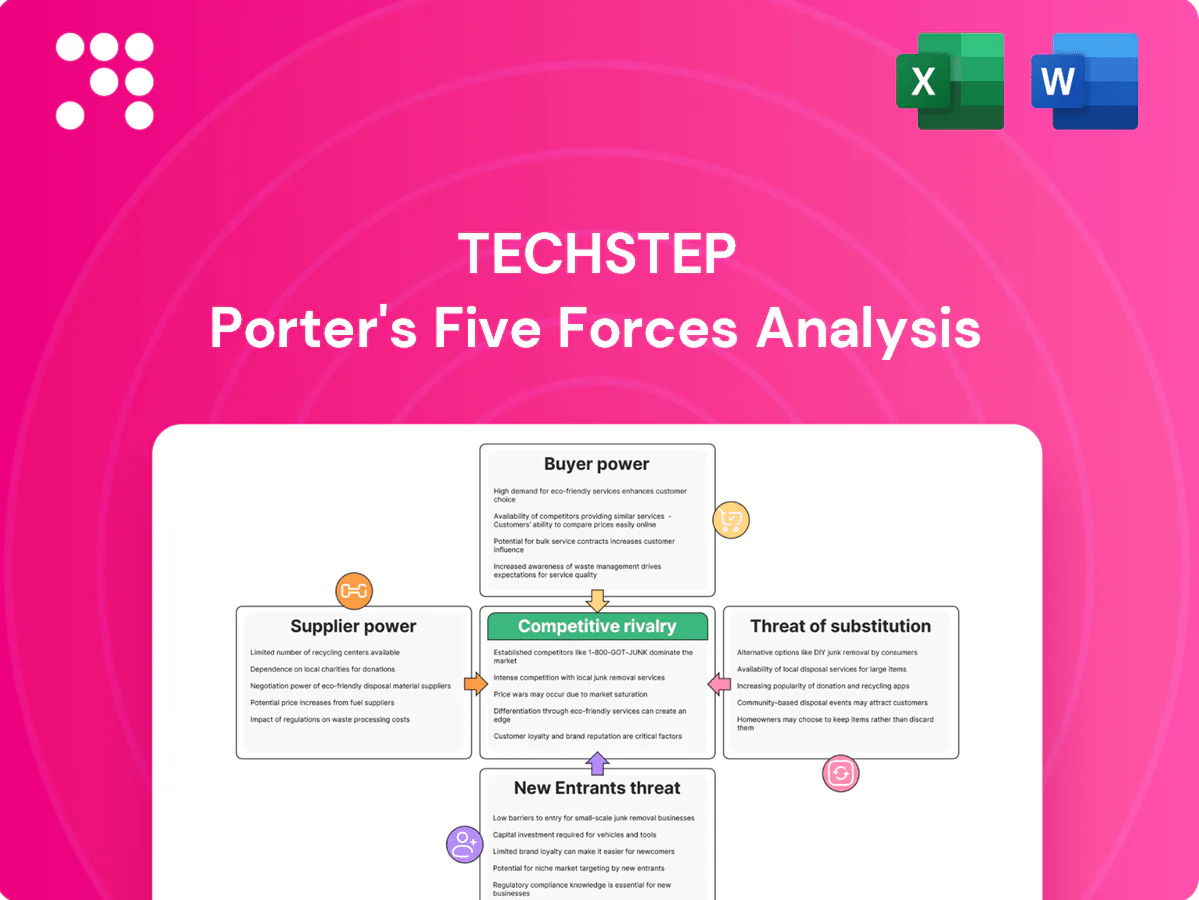
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Techstep operates in a niche enterprise comms market with moderate buyer power, low supplier leverage, limited substitute threats, and rising rivalry as consolidation accelerates; barriers to entry are moderate due to tech and compliance needs. This brief snapshot only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore Techstep’s competitive dynamics, market pressures, and strategic advantages in detail.
Apple and Google control critical MDM/EMM APIs and policy roadmaps; combined iOS (28%) and Android (71%) held ~99% of global mobile OS share in 2024, amplifying supplier leverage. Changes to iOS/Android management frameworks can ripple through Techstep’s portfolio; annual major iOS releases and monthly Android updates force certification timelines. This concentration raises supplier power and scheduling dependency for compliance.
Handset and rugged device makers such as Apple, Samsung and Zebra materially influence pricing, availability and support; Apple and Samsung together held roughly 40%+ of global smartphone market in 2024, while Zebra retained about 30% of the rugged handheld segment (2024). Allocation during tight supply cycles has delayed enterprise rollouts and constrained project timelines. Preferred partner tiers can secure rebates but demand volume commitments and lead-time guarantees. OEM leverage is moderate to high.
Reliance on hyperscalers (AWS 32%, Azure 22%, GCP 11% in 2024) and leading cybersecurity vendors for hosting, identity, and threat services creates significant switching friction for Techstep, raising migration costs and integration risk.
Supplier pricing changes or bundle strategies can compress gross margins, while strict SLAs and limited data residency options constrain viable alternatives.
Collectively, these factors increase supplier bargaining strength.
Operators and distributors gate SIM provisioning, device financing and logistics, enabling bundling of competing services and demands for MDF and revenue shares; GSMA reported about 8.5 billion mobile connections in 2024, underscoring carrier reach. Multi-carrier device options and MVNOs provide some countervailing power, leaving supplier bargaining power balanced to moderately high for Techstep.
Integration with EDR, IAM and ticketing platforms demands ongoing support; Gartner 2024 reported API and integration maintenance grew ~30% year-over-year, raising operational costs for vendors and clients. Vendor API changes and niche suppliers can create hold-up power over critical features, while a diversified integration roadmap and multiple provider bindings reduce single-supplier risk.
OS duopoly (iOS 28%, Android 71% in 2024) and hyperscaler concentration (AWS 32%, Azure 22%, GCP 11%) give suppliers high scheduling and pricing leverage; OEMs (Apple+Samsung ~40% smartphone, Zebra ~30% rugged) and carriers (8.5bn mobile connections) amplify deployment risk. Diversified integrations and multi-carrier options moderate but do not eliminate supplier power.
| Supplier | 2024 stat | Impact |
|---|---|---|
| Mobile OS | iOS 28% / Android 71% | High |
| Hyperscalers | AWS 32% / Azure 22% / GCP 11% | High |
| OEMs | Apple+Samsung ~40% / Zebra 30% | Moderate-High |
 Detailed Word Document
Uncovers key drivers of competition, buyer and supplier power, substitute threats, and entry barriers tailored to Techstep—identifying disruptive forces and strategic levers to protect market share and inform investor or internal reports.

 Customizable Excel Spreadsheet
A concise one-sheet Porter's Five Forces for Techstep that clarifies competitive pressures and helps prioritize strategic actions; customizable ratings and radar chart enable fast boardroom-ready slides and scenario comparisons without complex tools.
Mid-large enterprises routinely use RFPs and multi-year tenders (commonly 3–5 years) to extract lower prices. Standardized MDM feature sets enable like-for-like comparisons across vendors, spurring aggressive discounting and service credits. In 2024 buyer power remains high in larger segments, forcing margin compression and elevated contract concessions.
Policy templates, device enrollments, and user training create moderate switching costs for Techstep by bundling configuration and admin effort into deployments; in 2024 enterprises continued prioritizing prebuilt templates to cut rollout time. Migration tooling and professional services reduce friction but rarely eliminate bespoke integrations or IAM rework. Buyers can credibly threaten to switch to extract price or feature concessions, leaving customer leverage at a moderate level.
Customers gravitate to Microsoft 365/Intune and UEM bundles to reduce vendor sprawl; Microsoft reported over 300 million commercial seats for Microsoft 365 by 2024 and Gartner/IDC rank Intune as the leading UEM vendor (~40% share in 2024). Consolidation pressure forces Techstep to match fees or offer value-add services, shrinking margin levers. Buyers exploit suite economics to negotiate across licensing, elevating their bargaining power.
Compliance demands (GDPR: fines up to €20 million or 4% of global turnover) and certifications (ISO, SOC 2) raise SLA expectations, shifting risk to Techstep; the IBM 2023/24 Cost of a Data Breach benchmark (~$4.45M average) underscores financial exposure. Buyers now require reporting, third‑party audits and uptime credits (typical SLAs 99.9%+), broadening negotiating leverage.
SMBs, which account for roughly 90% of global firms, prioritize total cost of ownership and out-of-box simplicity, limiting room for upsell, while enterprises accept higher spend for depth, customization, and stronger security posture; tiered pricing (commonly 3 tiers) lets buyers downshift to lower-cost plans. Net effect: buyer power remains medium-high for Techstep in 2024.
Large buyers use 3–5y RFPs to extract discounts; standardized MDMs enable like‑for‑like cuts. Switching costs are moderate—templates help retention but integrations persist. Microsoft 365/Intune ~300M seats; Intune ~40% UEM share (2024) heighten consolidation pressure. GDPR fines up to €20M/4% turnover and avg breach cost ~$4.45M tighten SLAs; overall buyer power: medium‑high.
| Metric | 2024 | Impact |
|---|---|---|
| Intune share | ~40% | Consolidation pressure |
| Microsoft 365 seats | ~300M | Bundle leverage |
| GDPR fine | €20M/4% rev | Stronger SLAs |
| Avg breach cost | $4.45M | Financial risk |
This preview shows the Techstep Porter's Five Forces Analysis exactly as delivered—no placeholders or excerpts. The file you see is the complete, fully formatted document you'll receive and can download immediately after purchase. It’s ready for use in reports, presentations, or strategic planning.
Rivals such as Microsoft Intune, VMware Workspace ONE, Jamf, Ivanti/MobileIron, SOTI and Cisco Meraki create intense UEM/MDM competition, with 2024 industry reports placing Microsoft, VMware and Jamf among the clear leaders. Feature parity across core MDM capabilities drives commoditization, prompting frequent price promotions and migrations that heighten rivalry. Vendors increasingly compete on managed services, vertical-specific integrations and support depth to differentiate.
Telcos and MSPs increasingly compete with overlapping managed mobility bundles, with channel-led deals accounting for roughly 25% of enterprise mobility spend in 2024, compressing margins and driving price-based rivalry. Distribution partners often favor in-house or carrier-aligned solutions to protect margins, blurring vendor boundaries and accelerating churn. Co-opetition requires Techstep to adopt a selective channel strategy, clear carrier incentives, and margin-preservation pricing.
OS updates like iOS 18 and Android 15 in 2024 force quarterly-to-annual roadmap acceleration as new APIs and security patches hit devices. New form factors (more foldable launches in 2024) and rising threat vectors require rapid feature and patch cadence or enterprises switch vendors at renewal. Continuous innovation is now table stakes; the faster the change, the fiercer the rivalry.
Migration services lower renewal friction, enabling customers to switch more easily; competitors increasingly target incumbents with sign-on incentives, driving churn pressure that compresses margins. Retention for Techstep hinges on demonstrable outcomes and strict SLAs to justify premium pricing and reduce churn risk.
Service-led differentiation—through managed services, compliance tooling, and vertical solutions—shifts competition away from pure price wars by creating recurring revenue and higher switching costs; the global managed services market was about $245 billion in 2024 while worldwide IT spending reached roughly $5.4 trillion (Gartner 2024). Rivals are making similar bets, so proof of value via analytics and automation is decisive, making execution quality the primary battleground.
Market led by Microsoft, VMware, Jamf; feature parity fuels commoditization and frequent price-driven churn. Channel/MSP overlap (≈25% of enterprise mobility spend in 2024) and migration services lower switching barriers, compressing margins. Service-led plays (managed services ~$245B; global IT spend ~$5.4T in 2024) shift competition to execution, analytics and SLAs.
| Metric | 2024 |
|---|---|
| Top leaders | Microsoft, VMware, Jamf |
| Channel share | ≈25% |
| Managed services | ~$245B |
| Global IT spend | ~$5.4T |
Organizations can rely on built-in Apple and Google management capabilities (global OS share 2024: Android 71.0%, iOS 28.4% per StatCounter) and basic policy controls; for simple fleets this often suffices and can bypass full-service MDM providers. It trades depth and vendor support for lower cost and is a credible substitute at the low end.
Suite-based consolidation poses a high substitute threat as Microsoft 365 (hundreds of millions of commercial seats in 2024) and Google Workspace (enterprise footprint expanding in 2024) increasingly absorb device management and identity, and buyers cite vendor consolidation and integrated billing as a top priority; where these suites dominate, substitution risk is high and Techstep must demonstrate value that exceeds inclusion in those suites.
Larger IT teams can build scripts, leverage open-source tools and manage systems directly, internalizing expertise and reducing recurring managed-service fees. Viable especially in standardized cloud estates—Flexera 2024 reports ~92% of enterprises use cloud, enabling in-house automation at scale. For firms with mature DevOps, this trend substitutes external managed services and compresses TAM for providers like Techstep.
Permitting unmanaged or lightly managed BYOD reduces device enrollment — a 2024 industry survey found 58% of IT leaders reported lower MDM/EMM enrollments after loosening BYOD policies. VDI/DaaS can confine corporate access without full device control, shifting security spend from endpoint management to session/isolation tools. This policy-driven substitution materially reduces addressable market for comprehensive MDM/EMM vendors like Techstep.
Built-in OS management (Android 71.0%, iOS 28.4% StatCounter 2024) and suite consolidation (Microsoft/Google large commercial footprints 2024) present credible low-cost substitutes. Zero-trust/SASE adoption (~60% planning by 2025, Gartner 2024) and BYOD/VDI (58% lower MDM enrollments 2024) materially shrink demand for full MDM/EMM services.
| Substitute | 2024 stat | Impact |
|---|---|---|
| OS built-ins | Android 71.0%/iOS 28.4% | Low-end displacement |
| Suites | MS/Google enterprise scale | Consolidation risk |
| Zero-trust/VDI | 60%/58% | Reduce MDM TAM |
Cloud-native architectures and open APIs have made basic MDM builds feasible for startups, aided by a global SaaS market of roughly $197B in 2024 and 94% enterprise cloud adoption; niche-focused entrants can launch with relatively low capital and target vertical needs. However, scaling secure multi-tenant operations, compliance and SOC2-grade controls raises costs and complexity, keeping the overall entry threat at moderate.
Winning enterprise deals requires SOC 2, ISO 27001 and strict data residency controls; SOC 2 implementations and audits typically cost $30k–$150k and take 6–12 months, ISO 27001 often $20k–$100k and 6–18 months, while data residency setups can add $250k+ in infrastructure and legal costs. These time and capital burdens deter new entrants and materially raise effective barriers to entry.
Deep integrations with OS vendors, EDR/IAM platforms and carriers are table stakes for Techstep; API coverage and vendor certifications commonly require 12–36 months of engineering and compliance work. Entrants lacking breadth are routinely disqualified in roughly 70% of enterprise RFPs in 2024, making integration depth a concrete barrier that materially delays market entry.
Regulated clients view security incidents and downtime as unacceptable; IBM 2024 reports an average data breach cost of $4.45 million and GDPR fines can reach 4% of global turnover, making proven incident response, 24/7 support, and customer references decisive purchasing factors. New entrants face high credibility hurdles, so demonstrated SLAs and incident history create a durable trust moat for Techstep.
Large platforms bundle device management into broader suites at low marginal cost, and the global EMM/MDM market was valued at about USD 5.2 billion in 2024, narrowing price umbrellas and squeezing entrant margins. Carriers and major resellers control distribution channels and often prefer incumbent partners, suppressing new-entrant viability.
Cloud-native stacks and open APIs lower initial MDM build costs—global SaaS ~$197B in 2024 and 94% enterprise cloud adoption—so niche startups can enter quickly, but scaling secure multi-tenant ops, SOC2/ISO and data residency raises costs and time, keeping threat moderate. Deep integrations (12–36 months) and 70% RFP disqualification, plus $4.45M avg breach cost, create durable barriers.
| Metric | 2024 Value |
|---|---|
| Global SaaS | $197B |
| Enterprise cloud adoption | 94% |
| EMM/MDM market | $5.2B |
| Avg breach cost | $4.45M |


