
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Tecsys faces moderate supplier leverage, rising buyer expectations, and intensifying rivalry from logistics software specialists. Barriers to entry and threat of substitutes are tempered by industry specialization and long-term customer contracts. This brief snapshot only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore Tecsys’s competitive dynamics, market pressures, and strategic advantages in detail.
Major clouds concentrate supplier power: AWS (~33%), Microsoft Azure (~22%) and GCP (~12%) in 2024 (Synergy Research) can set pricing, SLAs and data egress fees (commonly ~$0.05–0.09/GB). Tecsys leverages multi-cloud optionality to limit risk, but migration frictions and reserved-instance commitments (savings up to ~72% on EC2) create switching lock-in. Outages or SLA breaches at providers can cascade into Tecsys’s contractual obligations and customer penalties.
Tecsys depends on databases, analytics engines and cybersecurity tools that are not perfectly substitutable, giving niche vendors pricing and roadmap power; global cybersecurity spending topped 200 billion USD in 2024 and the top three DBMS vendors account for roughly 70% of market share, concentrating leverage. Long certification cycles (months to >12 months) raise switching costs, and while volume discounts erode margins, critical features sustain supplier bargaining strength.
Reference data, carrier rates, and medical item catalogs are strategic inputs for Tecsys, with proprietary healthcare and logistics datasets commanding premium subscription fees and driving product differentiation. Contractual usage limits and API throttles (commonly in the 1,000–100,000 calls/day range) create vendor dependence and renewal leverage. Loss of access or rate reductions materially degrades solution value and customer retention.
Skilled system integrators and consulting partners drive Tecsys delivery capacity and customer success, with scarcity of domain expertise pushing partner rates higher and extending time-to-value. Preferred-partner tiers often require revenue sharing and certifications, increasing implementation costs. Partner concentration risk can bottleneck deployments and raise total project expense.
Major clouds concentrate power: AWS ~33%, Azure ~22%, GCP ~12% (Synergy 2024), setting pricing, SLAs and egress fees; reserved-instance commitments (savings up to ~72%) create lock‑in. Databases and cybersecurity tools are poorly substitutable—global cyber spend >200B (2024) and top‑3 DBMS ≈70% share—sustaining vendor leverage. Skilled SIs and senior talent scarcity push implementation and wage costs higher.
| Supplier | 2024 Metric |
|---|---|
| Cloud | AWS 33% / Azure 22% / GCP 12% (Synergy) |
| Cybersec/DB | Cyber spend >200B; top‑3 DBMS ≈70% |
 Detailed Word Document
Comprehensive Porter's Five Forces analysis for Tecsys that uncovers key competitive drivers, buyer and supplier power, and barriers to entry shaping its market position. Identifies substitutes, disruptive threats, and strategic levers to protect margins and inform investor or executive decision-making.

 Customizable Excel Spreadsheet
A compact one-sheet Porter's Five Forces for Tecsys that visualizes competitive pressure in a spider chart and lets you tweak inputs for scenarios—clean, slide-ready output for quick strategic decisions.
Health systems, retailers and complex distributors run competitive RFPs that force aggressive pricing and concessions; in 2024 multi-year contracts accounted for roughly 30% of enterprise software vendor revenue, concentrating account-level power. Their scale secures favorable terms, customizations and strict SLAs, while referenceability and case studies can only partially offset required discounts and concessions.
Integration footprints and process changes make switching onerous—2024 surveys show 68% of enterprises cite high switching costs, with average supply-chain system migrations costing about $1.2M and taking nine months, which softens buyer leverage post-implementation. Buyers target renewal windows to negotiate; data migration and training remain mutual bargaining chips, while demonstrated KPIs (eg 15–25% efficiency gains) cut price sensitivity.
Buyers demand seamless integration with ERP, EHR, WMS, TMS and carrier networks, and 2024 KLAS data shows 65% of healthcare buyers rank interoperability as a top procurement criterion. Such requirements expand customization scope and strengthen customers’ negotiating leverage. Open APIs and pre-built connectors reduce deployment friction, while compliance and security assurances remain table stakes in healthcare.
Clients demand outcome-based contracts focused on inventory turns (typically 8–12x in distribution), fill rates (95–99%) and service levels with clear ROI; these KPIs drive penalty/bonus structures tied to measurable savings and service improvements. When Tecsys demonstrates value it can defend pricing and margin; weak outcomes typically trigger concessions, renegotiation or re-competition.
Consolidation of buyers and centralized IT procurement in 2024 increase customer bargaining power, driving stricter SLAs and longer procurement cycles that compress vendor margins.
Standardized vendor assessment frameworks further compress pricing premiums, while land-and-expand strategies often dilute unit pricing over time; strong account management is crucial to protect expansion economics.
Buyers wield strong leverage via competitive RFPs and centralized procurement, with multi-year contracts ~30% of enterprise software revenue in 2024, forcing discounts and strict SLAs. High switching costs (68% cite this) and average migration costs ~$1.2M and nine months reduce churn risk post-deployment. Outcome KPIs (inventory turns 8–12x; fill rates 95–99%) drive penalty/bonus pricing and renewal leverage.
| Metric | 2024 Value |
|---|---|
| Multi-year contract share | ~30% |
| Enterprises citing high switching costs | 68% |
| Avg migration cost / time | $1.2M / 9 months |
| Inventory turns | 8–12x |
| Fill rates | 95–99% |
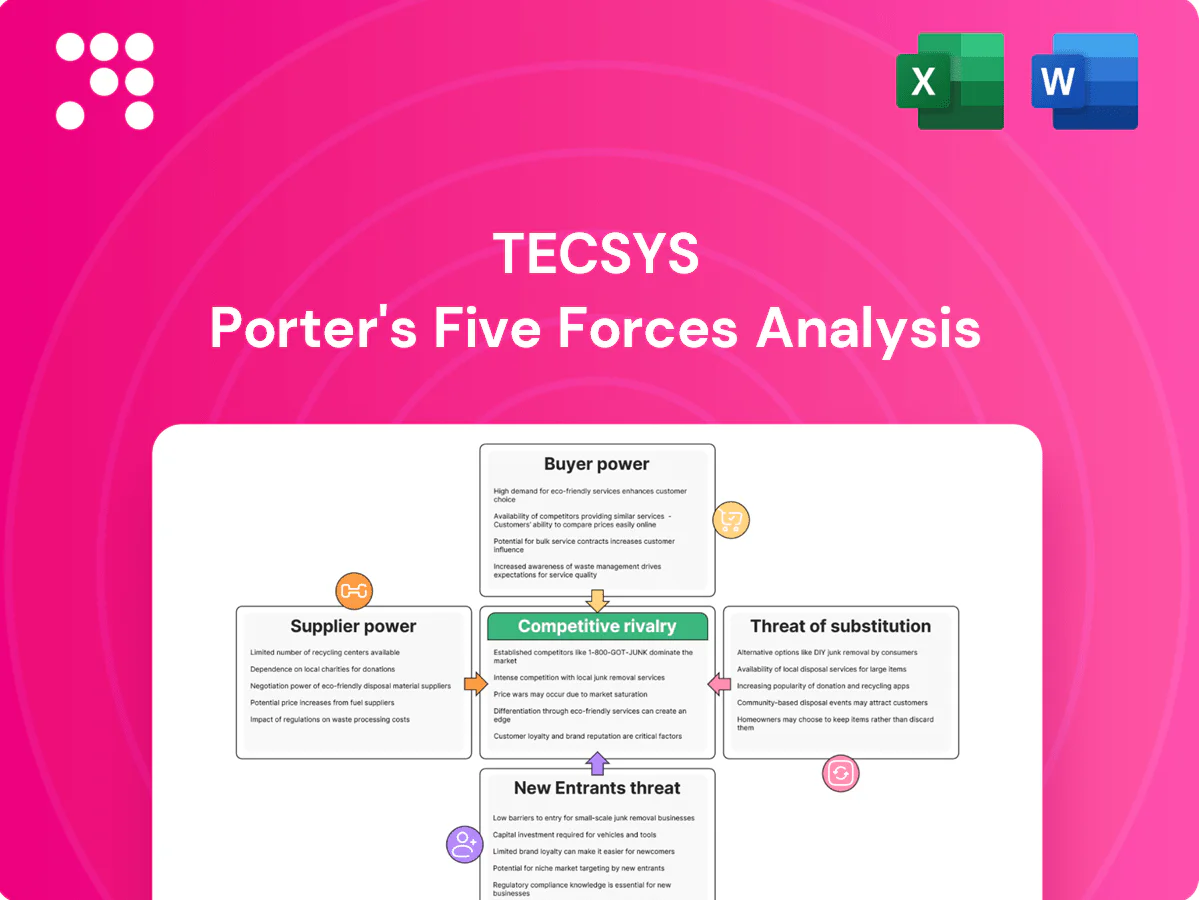
This preview shows the exact Porter’s Five Forces analysis for Tecsys you'll receive immediately after purchase—fully formatted and ready to use. The content covers competitive rivalry, supplier and buyer power, and threats of substitutes and new entrants, with actionable strategic insights. No placeholders or samples; instant download upon payment.
Large platforms such as SAP, Oracle and Infor bundle supply chain modules into ERP suites; SAP reported about 440,000 customers worldwide in 2024, increasing bundling stickiness.
Bundling compresses pricing for standalone players and raises switching costs, pressuring Tecsys on margins.
Differentiation rests on Tecsys depth in healthcare and complex distribution, while integration agility has become a key battleground.
Manhattan Associates, Blue Yonder and niche best-of-breed WMS/TMS vendors compete intensely on performance and vertical fit; feature velocity and optimization science (AI-driven routing and inventory optimisation) have accelerated releases in 2024, driving faster differentiation. The global WMS market grew about 9% in 2024 to roughly $4.2B, keeping rivalry high. Tecsys can differentiate on lower total cost of ownership and faster time-to-value, where reference wins in target verticals are often decisive for procurement committees.
Healthcare supply chain needs sterile processing, point-of-use, and regulatory workflows where HIPAA and 21 CFR Part 11 compliance drive audit trail requirements; 95% of US hospitals have certified EHRs, so EHR-adjacent tools compete for budget. Vertical specialists and EHR vendors vie for share. Tecsys’s deep domain expertise is an edge but must accelerate clinical integration and certification to stay competitive. Compliance and audit trails remain critical comparators for buyers.
Competitive bids force discounts, extended payment terms and flexible bundles, and rivals increasingly deploy pilot pricing and co-innovation credits to win deals in 2024. Robust ROI cases and quantified TCO analyses help Tecsys defend average selling prices and limit erosive concessions. Driving multi-module adoption reduces per-module price compression by increasing solution stickiness and lifetime value.
Enterprises run 6–12 month evaluations with proofs-of-concept in 2024, so rivalry centers on solution engineering and reference checks; Tecsys competes on technical fit and documented ROI. High presales costs elevate the impact of win-rate swings, making post-sale expansion (upsell/renewals) essential to amortize acquisition spend and reach target LTV/CAC ratios.
Rivalry is intense as ERP bundling (SAP ~440,000 customers in 2024) and WMS competitors compress margins; global WMS grew ~9% to ~$4.2B in 2024. Tecsys differentiates via healthcare depth and lower TCO, but 95% of US hospitals with certified EHRs raise integration stakes. 6–12 month POC cycles and aggressive bid concessions make ROI/TCO and post-sale expansion decisive.
| Metric | 2024 |
|---|---|
| SAP customers | ~440,000 |
| WMS market | $4.2B (9% growth) |
| Hospitals w/ certified EHRs (US) | 95% |
| Evaluation cycle | 6–12 months |
Larger organizations increasingly build proprietary solutions on public cloud stacks to capture fit-for-purpose workflows, but custom builds demand sustained engineering and expose talent risk. Maintenance commonly consumes 60–80% of total lifecycle costs, and accumulating technical debt erodes initial competitive advantage. Total cost of ownership frequently exceeds commercial software once upgrades, security and scaling are accounted for.
Customers often accept ERP native modules as "good enough"—about 70% of firms use built-in supply chain features in 2024—because tight native integration cuts complexity and lowers TCO. However functionality gaps surface in complex distribution and healthcare specifics, where best-of-breed solutions still win when optimization depth matters, driving higher ROI for specialist vendors.
Smaller operations often rely on spreadsheets and basic tools as a short-term substitute due to low upfront cost and ease of setup. Spreadsheet error rates have been documented as high as 88%, creating significant operational risk and compliance gaps. As scale grows, accuracy, auditability, and labor inefficiency drive migration to integrated WMS solutions.
Outsourcing to 3PL and BPO shifts technology choice to providers; the global 3PL market reached about USD 1.4 trillion in 2024, and many shippers adopt provider platforms rather than licensing software. Tecsys can mitigate substitution by partnering with 3PLs to stay embedded, while strict SLA and visibility demands constrain pure substitution.
Emerging AI planning and autonomous decision tools can bypass traditional WMS/SCM modules; in 2024 major providers (OpenAI, Google, Microsoft) expanded APIs enabling point-AI substitution. If standardized APIs proliferate, best-of-breed AI modules may slot in as substitutes, so Tecsys should integrate or offer native AI to hedge. Data quality and governance remain adoption gatekeepers.
Tecsys faces moderate substitute threat: 70% of firms used ERP native modules in 2024, 3PL market reached USD 1.4T (2024) shifting platform control, and spreadsheets persist with error rates up to 88% at small scale. Proliferating AI APIs in 2024 enable point-substitutes but data governance slows uptake. Partnerships and native AI reduce displacement risk.
| Metric | 2024 |
|---|---|
| ERP native adoption | 70% |
| 3PL market size | USD 1.4T |
| Spreadsheet error rate | up to 88% |
| AI API proliferation | Major vendors expanded APIs |
Healthcare and complex distribution demand deep process, compliance (FDA, HIPAA) and item master expertise, with hospitals typically managing 100,000+ SKUs. New entrants face 12–24 month learning curves to master workflows and regs. Early missteps erode credibility and contracts. Established playbooks and templates from incumbents such as Tecsys form strong defensible moats.
Connecting Tecsys to ERPs, EHRs, carriers and devices is arduous: 2024 industry studies show third-party integrations can add roughly 15–25% to implementation costs and extend timelines by months. Certification, testing and ongoing maintenance are costly and recurring, making pre-built connectors a durable competitive advantage. Buyers increasingly choose vendors with proven interoperability, driving higher deal win rates for incumbents.
Long enterprise sales cycles of 12–18 months demand significant upfront funding, with reference customers and third-party validations now decisive in deals; industry surveys show peer references and case studies heavily influence B2B procurement. Security audits add measurable cost: SOC 2 audits typically run $20k–$150k and HITRUST assessments $100k–$250k. New entrants also struggle to scale support and professional services capacity to reach typical 70%+ utilization and SLA expectations.
Entrenched Tecsys deployments and a fiscal 2024 installed base tied to ~CAD 132.4M revenue sharply reduce customer openness to trial entrants; data migration complexity and retraining costs create high switching friction. Incumbent product roadmaps and ongoing module expansion further preempt displacement, while within-base upsells compound the moat, raising time-to-win for newcomers.
Regulatory and security compliance in healthcare—privacy, traceability, and auditability—significantly raise entry barriers; 2024 IBM data cites the average healthcare data breach cost at about $11.1M, making procurement contingent on proven controls. Continuous compliance upkeep is resource-intensive, and established vendors leverage certification maturity as a strict procurement filter, often excluding newcomers.
High technical, regulatory and interoperability demands create steep 12–24 month learning curves and 12–18 month sales cycles, favoring incumbents. Integrations add ~15–25% to implementation costs; SOC 2 ($20k–$150k) and HITRUST ($100k–$250k) raise fixed entry costs. Tecsys installed base (~CAD 132.4M 2024 revenue) and data migration/retraining create high switching costs and durable moats. Buyers prioritize proven controls given average healthcare breach cost ~$11.1M.
| Metric | Value | Impact |
|---|---|---|
| Installed base revenue (2024) | CAD 132.4M | High inertia |
| Sales cycle | 12–18 months | Capital intensity |
| Integration uplift | 15–25% | Higher implementation cost |
| Avg breach cost (healthcare) | ~$11.1M | Procurement filter |
| Compliance audit | SOC 2 $20k–$150k; HITRUST $100k–$250k | Barrier to entry |


