
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
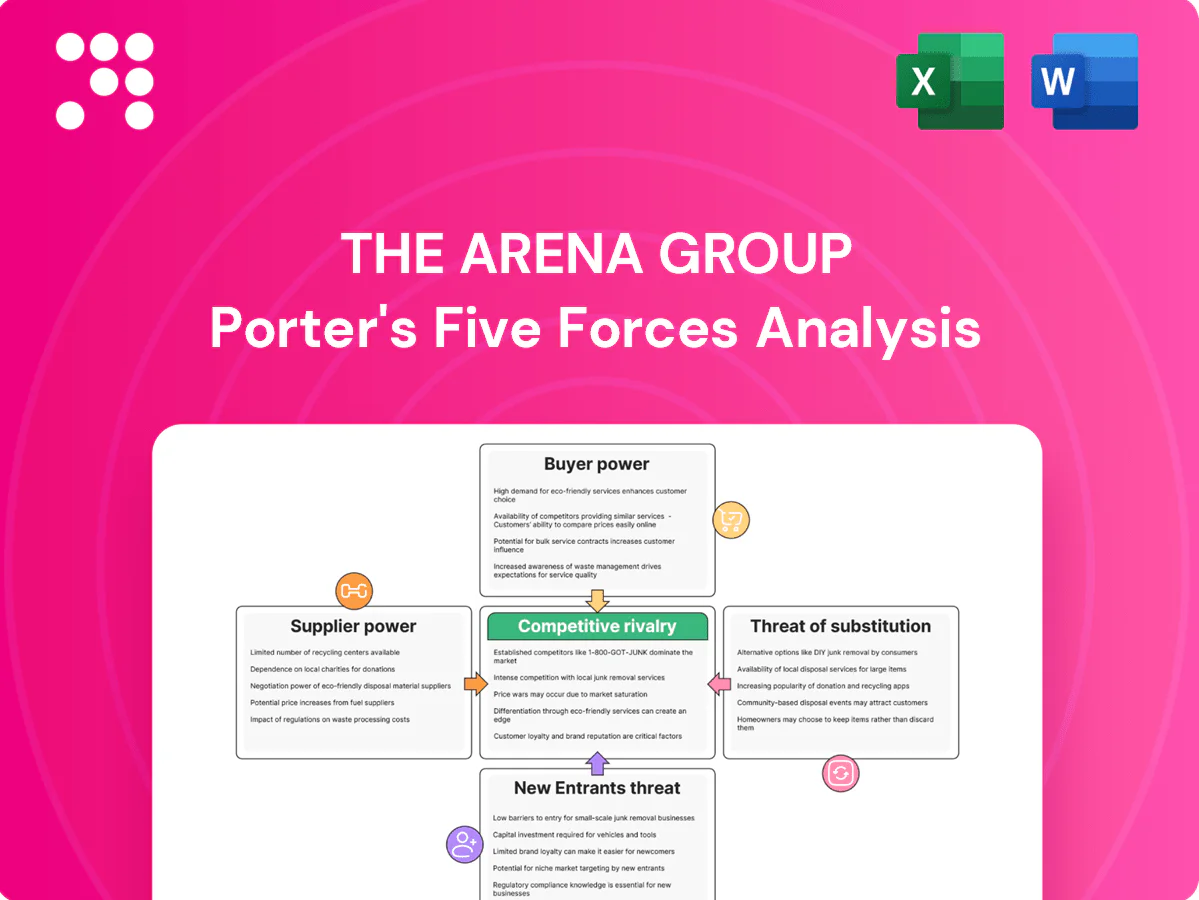
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
The Arena Group faces intense rivalry from diversified digital publishers and rising niche platforms, while buyer power and ad-platform dependence pressure margins; supplier and content-creation costs add variability to profit models. This brief snapshot only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore The Arena Group’s competitive dynamics, market pressures, and strategic advantages in detail.
Licensors of marquee brands, athlete IP and photo libraries—Getty Images alone catalogs over 415 million assets—increase content costs and compress margins for The Arena Group. The global sports media rights market was roughly $60 billion in 2023, and agencies restrict availability during peak events, driving up short-term fees. Dependence on exclusive or semi-exclusive assets raises switching costs and contract friction. Negotiation leverage spikes when content is time-sensitive or viral, enabling licensors to command premium rates.
High-quality journalists, analysts, and on-air talent with strong followings can negotiate higher pay and exclusivity, raising supplier leverage for The Arena Group.
Competition for niche sports-analytics and entertainment scoops intensifies bargaining power as specialized contributors are scarce and command premium rates.
Platforms enabling the creator economy, valued at about $250 billion in 2024, provide alternatives and increase churn risk, though long-term contributor contracts can reduce pricing volatility.
Cloud/CDN/CMS and ad-tech stacks are concentrated—AWS, Azure and GCP held about 67% of cloud market in 2024—creating clear supplier dependency for The Arena Group. Post-cookie, identity, measurement and brand-safety tools (eg LiveRamp-scale providers) become mission-critical, boosting vendor leverage. Integration complexity raises switching costs and operational risk, while volume commitments and multi-year contracts may secure discounts but limit flexibility.
Search engines, social platforms and app stores function as quasi-suppliers of audience access: Google handles ~92% of global search queries (StatCounter 2024), Meta platforms dominate social referrals and app stores enforce standard revenue shares up to 30%, all of which can abruptly alter traffic and monetization through algorithm or policy shifts. Diversifying channels reduces single-gatekeeper exposure but cannot eliminate platform leverage.
Sports leagues, financial data providers and entertainment databases control essential feeds; timely, accurate data underpins TheStreet and sports coverage, making quality non-negotiable. Bloomberg terminal access cost roughly 27,000 USD/year in 2024, illustrating base data expense. Licensing often involves multi-year contracts and can spike around major seasons and earnings cycles.
Licensors of brand/IP and time-sensitive sports rights (global market ~$60B in 2023) and scarce top talent raise content costs and switching barriers for The Arena Group. Concentrated cloud/CDN (67% AWS/Azure/GCP 2024), search (Google ~92% 2024) and app-store rules amplify supplier leverage. Data feeds and terminals (Bloomberg ~27,000 USD/year 2024) add recurring licensing pressure.
| Supplier | Metric |
|---|---|
| Getty | 415M assets |
| Sports rights | $60B (2023) |
| Cloud | 67% share (2024) |
| Search | Google 92% (2024) |
| Bloomberg | $27,000/yr (2024) |
 Detailed Word Document
Concise Porter's Five Forces analysis of The Arena Group highlighting competitive rivalry, buyer and supplier power, threat of new entrants and substitutes, and the key disruptive forces shaping its digital media and publishing margins; actionable insights for strategy, investor materials, and internal planning.

 Customizable Excel Spreadsheet
One-sheet Porter's Five Forces for The Arena Group that translates competitive complexity into a clear, customizable spider chart—perfect for quick strategic decisions. Easy to edit, slide-ready and integrates with reports to relieve analyst workload and speed boardroom alignment.
Advertisers and agencies wield strong leverage: programmatic purchasing now drives about 80% of display spend, enabling large buyers to use multi-publisher RFPs that compress CPMs. Brand buyers increasingly require viewability and attention metrics plus performance guarantees. Budget fluidity lets spend shift rapidly to social and CTV. Direct-sold, high-context placements still capture a 20–40% premium, partially defending pricing.
DSPs and SSPs raise price transparency—programmatic accounted for about 86% of US digital display in 2024, boosting buyer leverage. Auction dynamics and header bidding, which can lift publisher yields roughly 10–20%, also compress sell-side margins by intensifying bid competition. Brand-safety filters and blocklists shrink eligible premium inventory, reducing high-value bid opportunities. Curated private marketplaces, representing roughly a quarter of programmatic spend, improve take rates via guaranteed packages.
Consumers face abundant free alternatives, increasing price sensitivity and elevating churn risk for The Arena Group unless content or product utility is exclusive; by 2024 global paid news subscriptions exceeded 500 million, intensifying competition for paid attention. Flexible monthly billing in most publishers empowers switching, while bundling and member-only experiences can reduce elasticity and improve retention.
Sponsors increasingly demand multi-property integrations and use scale to negotiate discounts; in 2024 buyers intensified demand for cross-property deals. Measurement expectations require custom reporting and guaranteed KPIs, raising implementation costs and bargaining leverage. Seasonality concentrates leverage around tentpole events, while tiered packages with category exclusivity help protect pricing and margins.
Buyers hold strong leverage: programmatic reached about 86% of US display in 2024, enabling multi-publisher RFPs and CPM compression. Direct-sold premium placements still command 20–40% uplift, partially insulating revenue. Affiliates negotiate 5–20% commission rates tied to attribution; private marketplaces ~25% of programmatic improve guaranteed take rates. Sponsors push cross-property deals and KPI guarantees, concentrating leverage around tentpole events.
| Metric | 2024 Value |
|---|---|
| Programmatic share | 86% US display |
| Direct-sold premium | 20–40% uplift |
| Paid news subs | 500M global |
| Affiliate commission | 5–20% |
| PMPs share | ~25% programmatic |
This preview shows the exact The Arena Group Porter's Five Forces Analysis you'll receive immediately after purchase—no surprises, no placeholders. The document displayed is fully formatted, professionally written, and ready for download and use the moment you buy. You're viewing the final deliverable; after payment you'll get instant access to this identical file.
Major sports and news brands—ESPN (c.75 million monthly uniques in 2024), The Athletic (≈1.2 million subscribers in 2024), Yahoo Sports and league-owned media—intensely compete for audience and ad dollars. Exclusive rights and insider access differentiate coverage and command premium CPMs. Cross-platform distribution (social, apps, OTT) amplifies rivals’ reach. SI heritage helps, but freshness and speed remain decisive.
Vox, BuzzFeed, Barstool and pure-play entertainment sites compete fiercely for culture coverage and sponsorships, with viral cycles compressing differentiation windows and ad CPMs increasingly tied to short-term trends. Rivals now drive reach via short-form video—TikTok 1B+ MAU (2024)—forcing publishers to prioritize social-first clips and rapid iteration. Community features and creator networks, part of a creator economy estimated near $250B in 2024, emerge as key moats.
TheStreet competes directly with Bloomberg, CNBC, Wall Street Journal, and Seeking Alpha for investor attention; WSJ reported over 4 million digital subscribers in 2024, underscoring scale gaps. Differentiated analysis, proprietary tools, and platform features drive retention and ARPU. Rapid commoditization of market news intensifies headline and traffic competition. Premium data and education products can soften rivalry by creating higher-margin, stickier revenue streams.
Open web CPMs face persistent pressure from programmatic commoditization, with programmatic buying representing about 80% of US digital display spend in 2024, compressing CPMs and margins. Introductory subscription offers and discounts prompt short-term price wars and churn as bundles from larger media groups undercut standalone products. Value-added utilities and exclusive franchises can sustain premiums, often commanding materially higher ARPU for differentiated content.
Breakneck publishing cadences reward speed over depth, pushing The Arena Group to prioritize rapid headline-first workflows that drive short-term traffic spikes; Google held roughly 92% of global search market share in 2024, amplifying the stakes of ranking shifts. Frequent SEO and Discover algorithm changes reshuffle rankings, escalating tactical rivalry, while evergreen explainer hubs provide stable referral traffic against news volatility. Technical SEO and first-party engagement (newsletters, logged-in users) are critical defenses to retain CPMs and recurring audiences.
Competitive rivalry is intense across sports, news, finance and culture: ESPN (c.75M monthly uniques 2024), TikTok (1B+ MAU 2024) and platform giants amplify reach, while programmatic commoditization (~80% US display spend 2024) and Google dominance (~92% search 2024) compress CPMs and favor speed; scale gaps (WSJ ≈4M digital subs 2024) force differentiation via exclusives, premium tools and creator networks (~$250B creator economy 2024).
| Metric | 2024 |
|---|---|
| ESPN monthly uniques | ~75M |
| TikTok MAU | 1B+ |
| Programmatic share | ~80% |
| Google search share | ~92% |
| WSJ digital subs | ~4M |
| Creator economy | ~$250B |
Platforms like TikTok (1+ billion MAU in 2024), YouTube (2+ billion MAU in 2024), Reddit (~430 million MAU) and X (~450 million MAU estimates in 2024) deliver creator-driven highlights and analysis, letting users swap articles for bite-sized clips; algorithmic feeds cut visits to owned sites, while community interactivity and comments increase switching stickiness and reduce retention for traditional publishers.
Direct-to-consumer league apps and CTV bundles now deliver highlights, stats and commentary inside streams, reducing clicks back to publisher articles. Viewers increasingly consume analysis embedded in live streams and second-screen experiences, shifting time from web articles to screens with shoppable ads. US CTV ad spend surpassed $30 billion in 2024 (Insider Intelligence), amplifying revenue incentives for platforms. Co-viewing and synced features deepen engagement away from traditional publishers.
Independent analysts on platforms such as Substack surpassed roughly 1 million paying subscribers by 2023, building loyal, subscriber-only followings that compete directly with Arena Group traffic. Habit-forming newsletter and podcast formats erode web visits while podcast ad revenue topped $2 billion in 2023 (IAB), attracting brand budgets through host-read ads and memberships. Aggressive cross-promotion across shows and newsletters accelerates audience migration and wallet-share shifts away from traditional web inventory.
AI-driven summaries and answer engines (Google SGE expansion in 2024; ChatGPT with ~100M+ monthly users) are reducing clicks to source content by surfacing instant market and sports recaps on-platform, with search generative experiences increasingly satisfying user information needs. Publishers must double down on exclusive reporting, investigative depth and proprietary data to preserve direct engagement and subscription value.
Sportsbooks and fantasy platforms offer embedded data, live odds and communities that replicate editorial insights, with US legal sports-betting handle topping $93.6B in 2023 (AGA), driving second-screen substitution for Arena Group analysis. Integrated rewards and odds boosts deepen user lock-in, while content partnerships with publishers blunt but do not eliminate substitution pressure.
Substitutes erode Arena Group traffic: short-form platforms (TikTok 1B+ MAU 2024, YouTube 2B+), AI answer engines (ChatGPT ~100M monthly) and newsletters/podcasts (Substack ~1M paid; podcast ad rev $2B 2023) divert attention and ad spend; CTV ad spend $30B+ 2024 and US sportsbooks (handle $93.6B 2023) create second-screen replacement, pressuring retention and CTRs.
| Source | 2023/24 |
|---|---|
| TikTok MAU | 1B+ |
| YouTube MAU | 2B+ |
| CTV ad spend | $30B+ (2024) |
| Sportsbook handle | $93.6B (2023) |
Modern CMS, creator tools and AI cut startup costs, with WordPress powering ~43% of sites (W3Techs 2024). Niche entrants can rapidly own micro-communities via targeted content. Distribution on platforms like TikTok (≈1.5B MAU) and YouTube (2+B users) removes early audience hurdles. Monetization often begins with affiliates and sponsorships—influencer marketing was ≈$21B in 2023—before ads.
Influencers with built-in audiences can launch media properties quickly; the creator economy is estimated over $100B and influencer marketing was $21.1B in 2023, shortening time-to-scale. Direct fan subscriptions and DTC commerce weaken incumbents' moats as creators monetize audiences. Merch, memberships and live events drive early revenue while platform discovery (TikTok ~1.5B MAUs) accelerates traction.
Programmatic pipes give newcomers instant demand access, with programmatic handling roughly 86% of US display ad spend in 2024, lowering technical entry barriers. Curated marketplaces and PMPs—around 45% of programmatic deals in 2024—surface higher-quality new inventory and ease sales. Brand-safety and viewability filters (industry viewability ~55% in 2024) still prune revenue. Established direct-sales relationships remain critical for premium CPMs, often 2–3x programmatic rates.
Regulatory and privacy headwinds raise fixed costs for entrants: GDPR/CCPA enforcement can impose fines up to 4% of global turnover, and Apple ATT led some publishers to report ad revenue drops near 30%, showing consent and identity rules materially raise compliance and monetization risk. Cookie deprecation (Chrome phase-out through 2024–25) complicates audience targeting; building data partnerships and first-party login reach often takes months to years, letting larger incumbents absorb overhead more easily.
Credibility in sports and financial reporting is hard to replicate quickly; Reuters Institute Digital News Report 2024 found average news trust at 42%, underscoring barriers for new entrants. Rigorous fact-checking, legal review and editorial standards raise operating costs and time to scale. Exclusive sources and access develop over years, and heritage brands keep advantage in marquee sponsorships and paid subscriptions.
Modern creator tools, WordPress 43% of sites (W3Techs 2024) and platforms (TikTok ~1.5B MAU) lower startup costs and audience barriers; influencer marketing was $21.1B in 2023 enabling rapid launch. Programmatic (~86% US display 2024) eases ad access but premium CPMs favor incumbents; privacy headwinds (GDPR fines up to 4%, ATT ~30% ad hits) and trust gaps (news trust 42% 2024) raise scale costs.
| Metric | Value |
|---|---|
| WP share | 43% (W3Techs 2024) |
| TikTok MAU | ~1.5B |
| Influencer spend | $21.1B (2023) |
| Programmatic US display | ~86% (2024) |
| News trust | 42% (Reuters 2024) |


