
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
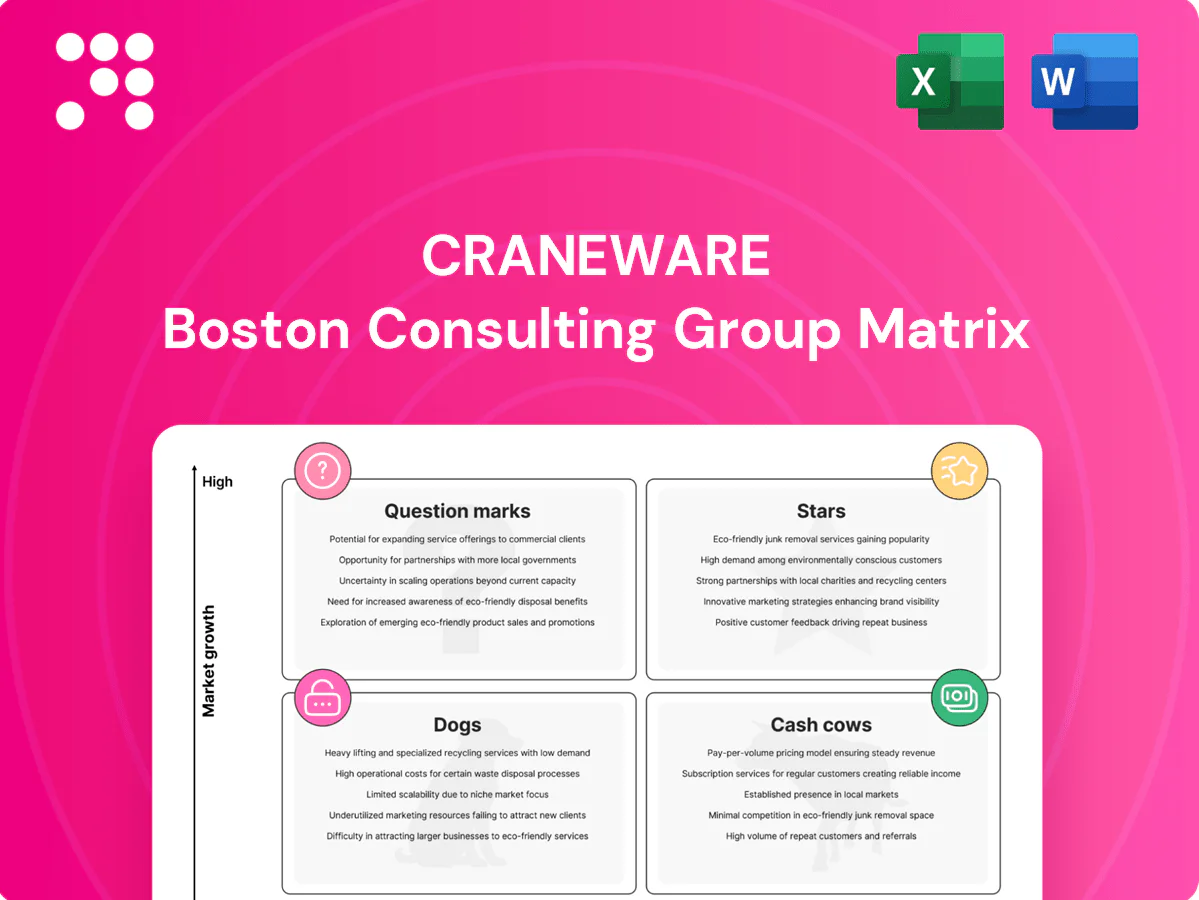
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
This snapshot teases where products might land—Stars, Cash Cows, Dogs, or Question Marks—but the full Craneware BCG Matrix gives you the full map and the moves to make. Buy the complete report to unlock quadrant-by-quadrant placement, data-driven recommendations, and a ready-to-use Word + Excel package that saves you hours of work. Get instant clarity on where to invest, divest, or double down—strategic guidance you can act on today.
Revenue Integrity SaaS Platform sits as a Star in Craneware’s BCG matrix, powering charge capture and pricing accuracy across hospitals and capturing high share in a market growing as CFOs pursue every compliant dollar. Craneware reported FY2024 revenue near £85m with ARR growth ~14%, underscoring momentum. Continued investment in integrations, automation, and outcomes proof will cement pole position.
Pricing & Transparency Analytics rides the regulatory tailwind from the CMS Hospital Price Transparency Rule (effective Jan 1, 2021) and the CMS civil monetary penalty framework (up to 300 USD per day), driving strong uptake among health systems. Clear ROI, board-level dashboards and measurable margin recovery position it as a flagship growth engine. Double down on benchmarks, payer-rate intelligence and speed-to-insight to sustain star performance.
As payer complexity spikes, Contract & Payer Reimbursement Optimization forecasts, models, and helps collect the right amounts, targeting rising Medicare Advantage volumes (over 31 million enrollees in 2024) and mixed commercial plan rules. The module is sticky and strategic, with adoption increasing as new value-based and bundled reimbursement models expand. Invest to broaden coverage across service lines and close the loop with denials prevention, addressing average denial rates near 6% in 2024.
Compliance & Audit Automation is a Star for Craneware as regulatory pressure remains high; CMS reported a Medicare FFS improper payment rate near 6.0% in 2023, making automated audit trails and AI-assisted reviews critical to cut rework and exposure. Hospitals pay premiums for compliance when fines and recoveries (DOJ health care recoveries exceeded $2.8B in FY2023) threaten margins. Build proactive alerts and AI reviews to stay ahead.
Enterprise Data Backbone is the Stars asset: its role as connective tissue across EHRs, billing, and finance keeps switching costs high and underpins recurring revenue; with healthcare cloud adoption exceeding 60% of workloads by 2024, this layer gains strategic value as migrations accelerate. Prioritize deeper APIs, certified connectors, and fast time-to-value to lock customers and expand wallet share.
Revenue Integrity SaaS is a Star for Craneware: FY2024 revenue ~£85m and ARR growth ~14% show momentum; products capture share as hospitals chase margin recovery. Pricing, Contract Optimization, Compliance and Enterprise Data drive adoption amid >31m Medicare Advantage enrollees and ~6% denial/improper payment rates.
| Product | FY2024 metric | Key stat |
|---|---|---|
| Revenue Integrity | £85m rev | ARR +14% |
| Pricing & Transparency | Uptake ↑ | CMS rules enforced |
| Contract Optimization | Adoption ↑ | MA >31m (2024) |
 Detailed Word Document
Craneware BCG Matrix: quadrant-by-quadrant review with strategic buy/hold/sell guidance and trend context.

 Customizable Excel Spreadsheet
One-page Craneware BCG Matrix placing each business unit in a quadrant to spot growth, risks and prioritize resources quickly.
Chargemaster Management is a mature, widely adopted, mission-critical solution for revenue integrity—driving dependable renewals and cross-department expansion despite low market growth (mid-single-digit sector-wide growth in 2024). Maintain product margins by prioritizing UX refreshes and efficiency tweaks that reduce coding errors and lift reimbursement capture rates. In 2024, incremental optimization projects commonly deliver 3–7% net revenue uplift per site, reinforcing steady cash-cow returns.
Denials Tracking & Workflows is a Craneware cash cow: well entrenched with standardized workflows that routinely reduce write-offs, supporting customers where 2024 industry denial rates averaged 5–10%. Market growth is modest but steady, with the module delivering predictable recurring revenue. Continued optimization of automation and reporting—automation can cut write-offs by up to 30%—keeps churn near zero.
Professional Services & Training at Craneware are repeatable, software-tied enablement with predictable gross margins typically in the 25–35% range (2024 industry benchmark), delivering stable growth around 5–8% CAGR rather than explosive expansion. Systematize delivery by packaging assessments, fixed-scope implementations and playbooks to reduce variability and protect margins. Keep utilization above 85% through blended delivery (onsite + remote) and standardized training modules to maximize revenue per consultant and cash generation.
Regulatory Content Updates drive predictable subscription revenue by delivering annual code-set and rule changes (ICD-10-CM October 1, 2024 update; annual CPT updates) that hospitals embed into workflows; KLAS 2024 benchmarks show vendor retention for embedded solutions exceeds 90%, so churn is minimal. Tight cost control and flawless uptime convert updates into high-margin cash flow.
Legacy Reporting Packs are classic KPI dashboards customers still rely on for routine ops; they show low innovation but high stickiness, providing stable, low-cost maintenance revenue that supports cash flow through predictable renewals (industry renewal benchmarks in 2024 remained above 85%).
Chargemaster, Denials, Services and Regulatory updates generate stable subscription and services cash with >90% retention (KLAS 2024) and SaaS gross margins ~70–80% (2024); optimization projects yield 3–7% site revenue uplift.
| Metric | 2024 |
|---|---|
| Retention | >90% |
| SaaS gross margin | 70–80% |
| Uplift per site | 3–7% |
This preview is the final Craneware BCG Matrix you'll receive after purchase. No watermarks or demo text—just the fully formatted, analysis-ready report. Crafted by strategy experts, it's designed to drop straight into your planning, pitch decks, or board packs. After buying you'll get the exact file—editable, printable, and ready to share. No surprises, no extra steps—one purchase and it's yours.
On-premise deployments are maintenance-heavy, show low-growth and are increasingly out of sync with buyer preferences; Gartner reported in 2024 that roughly 78% of organizations have adopted a cloud-first strategy, underscoring declining demand. Migration costs and complexity trap engineering and capital resources, eroding ROI and agility. Recommend sunsetting with clear upgrade paths to cloud and minimizing new custom work to avoid further technical debt.
Bespoke one-off customizations demand high effort and deliver low repeatability, creating a persistent margin drag versus core SaaS; median public SaaS gross margin was about 70% in 2024, so bespoke work can materially reduce profitability. These projects distract engineering and sales from scalable product roadmaps. Tightly qualify or decline one-offs and actively steer demand toward productized, repeatable offers to preserve scale economics.
Outside the US, regulatory fit and sales motion get tough fast; Craneware (LSE: CRW) faces low share and slow cycles as international healthcare IT procurement typically spans 12–18 months. Low share, slow cycles, and higher support costs squeeze margins—international support often adds 20–30% to operating expense. Consider partnerships or exit until scale economics make sense.
Perpetual-license holdovers generate lumpy revenue and leave persistent support burdens as customers resist upgrades yet still require care; in 2024 many healthcare software vendors reported growing maintenance cost ratios and slower upgrade adoption trends. Nudge conversions through targeted incentives or plan phased retirements to reduce long-term support liabilities.
Standalone point tools that do not plug into EHR/RCM workflows see adoption collapse; with over 90% of US hospitals using EHRs by 2024, disconnected tools fail to reach clinicians and revenue cycle teams. Low differentiation makes them easy to replace and drives total cost of ownership up while ROI falls below platform alternatives. Recommend consolidation or retirement into Craneware’s core platform to recapture ~$10–30k per provider/year in operational value seen in integrated deployments.
On-prem, bespoke, international low-share, perpetual-license holdovers and standalone point tools are low-growth, high-cost Dogs for Craneware: 78% cloud-first adoption (Gartner 2024), median SaaS gross margin ~70% (2024), intl procurement 12–18 months, support +20–30% Opex, EHR >90% US adoption, $10–30k/provider/yr lost value if not integrated.
| Metric | Value |
|---|---|
| Cloud-first | 78% (2024) |
| SaaS gross margin | ~70% (2024) |
| Intl sales cycle | 12–18 mo |
| Support Opex uplift | +20–30% |
| EHR US adoption | >90% (2024) |
AI-Assisted Coding & Documentation offers huge upside in accuracy and speed—controlled studies report up to 55% faster coding and material error reduction; the market is crowded and still early in 2024. If Craneware can demonstrate measurable lift in coder throughput or revenue-per-claim it can flip to Star status. Achieving that requires bold investment and earned clinical trust from hospitals and coding teams.
Question Marks: Payer Rate Intelligence & Negotiation Tools — price transparency (CMS rule effective 2021) has unlocked competitive insights but share is not guaranteed. Hospitals (about 6,090 U.S. hospitals) want leverage at the negotiating table and demand actionable models. Build unique datasets and scenario models to win mindshare and convert pilots into contracts.
As reimbursement shifts toward value-based models, providers need precise cost and outcome views; the global value-based care analytics market is projected to grow at about 14% CAGR through 2030 to roughly $11bn. Craneware's share is still forming as it expands beyond revenue integrity into cost-to-serve and outcomes analytics. Integrating clinical and financial signals is required to break through and win contracts with payers and ACOs.
Ambulatory & ASC Revenue Solutions sit as Question Marks: tapping a fast-growing outpatient market (US ASCs ~6 million procedures/year, market CAGR ~5% in 2023–24) but facing different buyers and workflows, so Craneware’s current share is low despite strong adjacency to hospital clients. Packaging light-weight modules and channeling through health systems can accelerate adoption and convert this quadrant to Stars.
Question Marks: Pharmacy/340B Optimization sits in a high-opportunity, high-uncertainty quadrant — complex 340B rules, real-dollar recovery potential (program provides billions in outpatient drug discounts annually) and rising HRSA/DOJ scrutiny make it attractive; adoption remains early with competitive pressure, so proving compliance rigor and scaling recoveries fast is critical.
Question Marks: payer-rate intelligence, ambulatory/ASC revenue and 340B optimization have high upside but low share. US: ~6,090 hospitals; ASCs ~6M procedures/year; value-based analytics ~14% CAGR to ~$11B by 2030. Convert pilots via unique datasets, clear ROI and compliance rigor.
| Seg | Metric | Need |
|---|---|---|
| Payer | 6,090 hospitals | ROI models |
| ASC | ~6M/yr | modular GTM |
| 340B | billions in discounts | compliance+scale |


