
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
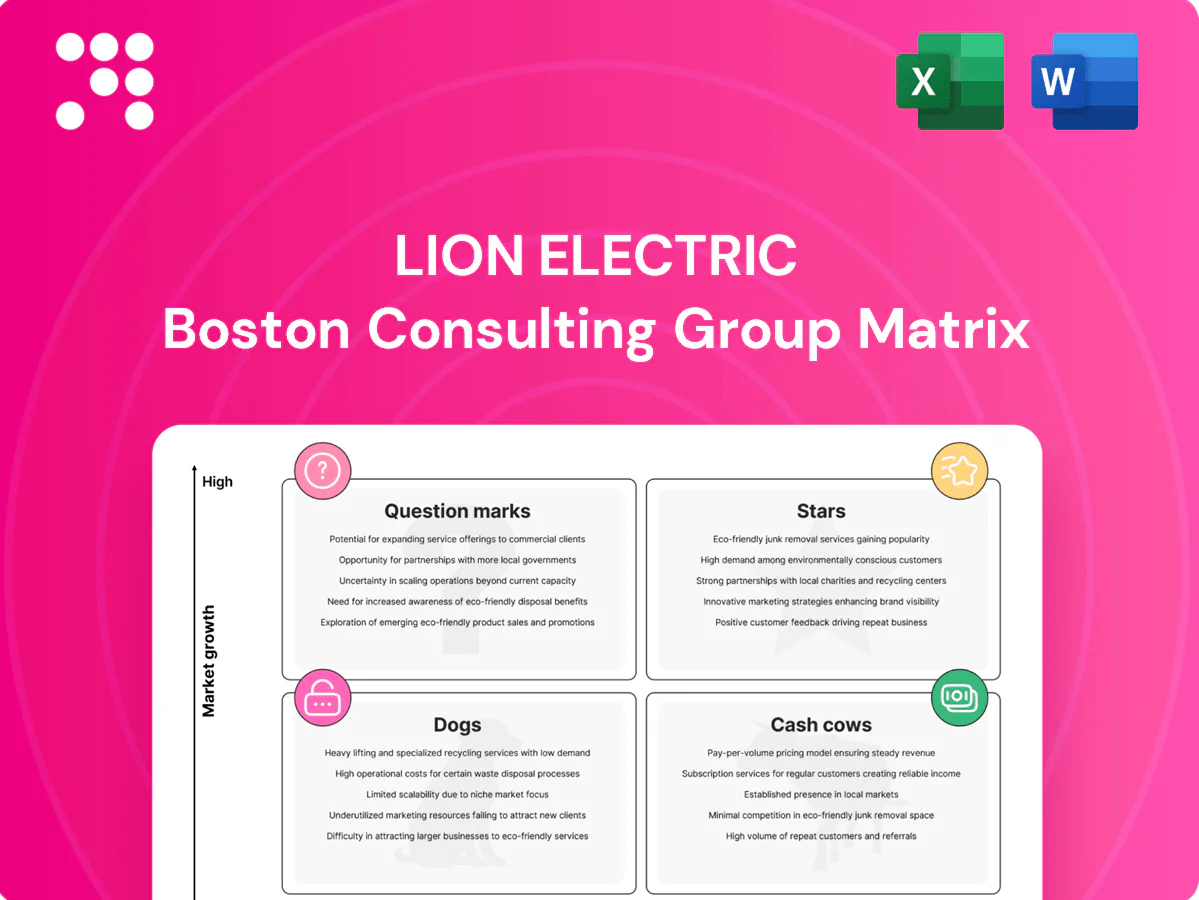
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Lion Electric’s quick BCG snapshot shows who's winning and who's costing you—now see the full picture. Purchase the complete BCG Matrix for quadrant-by-quadrant placements, data-backed recommendations, and a clear roadmap for where to invest or divest next. Skip the guesswork: get the Word report plus an Excel summary, ready to present and act on. Buy now for strategic clarity you can use today.
Electric school buses leadership is Lion’s flagship with a strong North American share in a category expanding rapidly; districts are lining up as the EPA Clean School Bus Program (over 5 billion USD) and state diesel phase-outs targeting the 2030s unlock orders. Keep investing in production capacity, delivery operations, and customer success to defend share. Hold the line now and this segment can mature into a cash-generating business later.
Turnkey depot charging for schools is a Star: paired bus+charging sales are surging as buyers want one throat to choke; Lion reported a high attach rate in 2024 (≈60%) boosting project margins as scale rises and contributing to a backlog above US$1.3bn. Marketing emphasizes whole-project outcomes over specs, and growth tracks school-bus electrification—keep feeding the pipeline.
Vertical integration of in-house battery packs at Lion Electric reduces cost volatility and shortens lead times, a benefit fleet buyers began citing in 2024 procurement reviews. The strategy is capital hungry today but becomes defensible once factory utilization remains high and amortizes fixed costs. Emphasize reliability data and warranty performance to persuade fleet CFOs, as better in-house failure rates directly lower TCO. The greater the share of packs shipped inside Lion vehicles, the stronger the competitive moat.
Regulatory pressure and city ESG mandates are accelerating electrification in classes 5–7, making urban medium-duty e-trucks a Stars category for Lion Electric given strong brand recognition and credible municipal and fleet deployments in dense routes.
Bundling charging, driver training, and grants navigation drives higher sales velocity and adoption; continue prioritizing high-density routes where total cost of ownership already favors electric adoption.
Government-backed fleet programs drive large, visible volumes for Lion Electric, as seen with the US Clean School Bus Program (US$5 billion) and provincial Canadian fleet funding that accelerated 2024 purchases; large awards and framework agreements crowd out smaller competitors during funding waves. Prioritize flawless delivery and granular reporting to stay first in line for renewals; execution compounds into referrals and repeat buys.
Lion’s electric school buses and depot charging are Stars: 2024 attach rate ≈60%, backlog >US$1.3bn, and US Clean School Bus program US$5bn fuelling orders; in-house battery packs cut lead times and TCO but raise capex needs; urban class 5–7 e-trucks show strong municipal uptake; prioritize capacity, delivery excellence, and bundled services to convert growth into durable cash flow.
| Metric | 2024 |
|---|---|
| Attach rate | ≈60% |
| Backlog | >US$1.3bn |
| Clean School Bus | US$5bn |
 Detailed Word Document
Concise BCG Matrix review of Lion Electric, identifying Stars, Cash Cows, Question Marks and Dogs with strategic moves.

 Customizable Excel Spreadsheet
One-page BCG matrix placing Lion Electric units in quadrants for clear strategic focus and investor-ready slides
Installed base for Lion Electric keeps expanding, driving predictable aftermarket parts and service margins (industry aftermarket margins commonly range 40–60%), with steadier growth and lower cost-to-sell than new vehicle sales. Locking multi-year service bundles at vehicle sale smooths cash flow and increases recurring revenue. Improving field-operations efficiency typically boosts margins more than adding new logos.
Standardized curricula and repeatable cohorts let Lion productize driver and technician training, achieving attach rates around 75% with outcome-based pricing tied to uptime guarantees. Minimal incremental cost per vehicle (under USD 500 annually) makes training a high-margin cash cow customers view as risk insurance. It quietly funds ongoing support and reduces capex pressure by keeping training spend operational rather than capitalized.
Basic analytics, health monitoring, and energy reporting modules sell easily post-deployment and become embedded in fleet ops, producing low churn once dashboards are adopted. Upsell paths include compliance and grant-reporting modules that fleets buy to capture incentives and meet regulations. Managed by a small team, these telematics and software subscriptions deliver stable, recurring revenue and fit the classic BCG cash-cow profile.
Charging O&M contracts convert installed infrastructure into steady cash flows as 99% uptime SLAs and planned truck rolls preserve service margins; remote monitoring and pooled spare parts drive scale, aligning with McKinsey 2024 findings that predictive maintenance can cut downtime by up to 30%.
Project management fees (grants/site) are cash cows for Lion Electric because clients consistently pay to have permitting and paperwork handled, with a reusable playbook across districts and depots. Low marketing cost and strong attachment to vehicle deals make these fees sticky and high-margin. They continue to generate cash even when unit deliveries slow.
Installed-base services, training (75% attach) and telematics deliver high-margin recurring cash (industry aftermarket margins 40–60%), with training incremental cost
Metric
Value (2024)
Aftermarket margins
40–60%
Training attach
75%
Training cost/veh-yr
Charging SLA
99% uptime
Downtime reduction
-30% (McKinsey 2024)
The preview you're seeing is the exact Lion Electric BCG Matrix file you'll receive after purchase. No watermarks, no demo text—just the final, fully formatted report built for strategic clarity. It’s crafted with market-backed analysis and ready to edit, print, or present. Once bought you get the full document instantly in your inbox with no surprises. Use it straight away in planning, decks, or client meetings.
Standalone charger hardware resale competes on price, not integrated value, creating ongoing support headaches and service costs. Hardware margins were thin in 2024, often under 15% in the commercial charger segment, while the global EV charging market was estimated around USD 15.6 billion in 2024. Third-party failures amplify brand risk and warranty exposure; inventory ties up working capital if not sold as part of turnkey fleet deals. Recommend exit or severe limitation to protect margins and reputation.
Bespoke one-off vehicle customizations at Lion Electric are tiny orders that demand heavy engineering and invite endless change requests, directly eating capacity and distracting the main production line. Profitability often looks acceptable on order papers until costly rework and line stoppages materialize, eroding margins and throughput. Standardize options or decline one-offs to protect factory efficiency and predictable unit economics.
Transit specs are brutal and incumbents like New Flyer, Gillig and BYD dominate procurement, making legacy RFPs highly competitive. Bid cycles often run 12–24 months, unit margins are compressed and growth is lumpy, turning marginal wins into cash traps. Unless Lion shows a clear turnkey edge (service, charging, financing), de-prioritize generic RFPs without upside.
Selling EV fleets in geographies with weak incentives in 2024 produces slow sales and a higher TCO versus subsidized markets, with subsidized regions capturing over 70% of global fleet orders; support costs remain fixed and don’t scale with tiny footprints, leaving capital idle as deals stall. Pull back investment until policy shifts restore viable order pipelines.
Ultra-low volume vocational variants are great stories but poor economics for Lion Electric; certification, tooling and training commonly exceed $1M and require >100 units to break even, while many runs deliver <50 units and never return cash, becoming museum pieces in the catalog; trim the SKU tree.
Low-margin standalone chargers and bespoke one-offs drained margins and capacity in 2024; hardware margins were under 15% and third-party failures increased warranty risk. Transit RFPs remain crowded with incumbents, bid cycles 12–24 months, growth lumpy. Low-incentive markets stalled sales; subsidized regions captured >70% of fleet orders.
| Metric | 2024 Value |
|---|---|
| Charger market | USD 15.6B |
| Hardware margin | <15% |
| Subsidized market share | >70% |
| Cert/tooling breakeven | >$1M / >100 units |
Heavy vocational trucks (utility, refuse) show high growth as U.S. and Canadian municipal fleets accelerate electrification; Lion’s share remains low—estimated in the low single digits of North American municipal heavy vocational deliveries in 2024. Duty cycles look favorable for total cost of ownership once specs align with routes and charging, supported by lower energy/maintenance costs. Targeted pilots with top operators and body‑builder alliances are required to prove scale. Decide fast: scale or shelve.
Regulatory tailwinds are tangible—California's Innovative Clean Transit mandates zero-emission bus purchases starting 2029 and federal programs under the Inflation Reduction Act boost EV fleet electrification—yet V2G and energy-services revenues for Lion remain nascent. If monetization models solidify (peer pilots show MW-scale aggregations), V2G could flip to a high-margin revenue engine. Success requires utility partnerships and ironclad uptime (industry SLAs target ~99.9%), so prioritize focused bets in a few anchor markets.
Battery sales to third parties can be an attractive volume filler for Lion Electric’s plant, but channel conflict and warranty exposure remain material risks; BloombergNEF reported average EV pack prices around 120 USD/kWh in 2024, so if integration costs stay low margins could be viable. Start with controlled partners and strict specs, and scale only after field data proves reliability.
International expansion beyond North America represents a large TAM but Lion faces unknown brand recognition and limited support networks; certification hurdles and sparse service footprints are the main choke points, so prioritize tightly scoped pilots with select distributors rather than a broad rollout and exit quickly if unit economics fail to meet targets.
Customer interest in advanced ADAS/autonomy-ready Lion platforms is strong but commercial budgets lag; 2024 ADAS market estimates near USD 47B highlight demand while fleet CAPEX cycles delay buys. Partnerships de-risk sensor/stack delivery but integration consumes engineering FTEs; tie development to paid pilots and explicit safety cases to monetize early. Preserve optionality via modular architectures to avoid R&D bloat.
Lion’s heavy vocational trucks are question marks: 2024 North American municipal share in low single digits, BNEF EV pack price ~120 USD/kWh, CA Innovative Clean Transit mandates ZEB purchases from 2029 and federal EV fleet incentives boost demand; pilots, utility/V2G partnerships, and strict service SLAs (~99.9%) determine scale-or-kill decisions.
| Metric | 2024 |
|---|---|
| Municipal share | low single digits% |
| EV pack price | ~120 USD/kWh |
| Key policy | CA ICT 2029 |


