
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Cover political, economic, social, technology, legal and environmental change.
Separate market signals from their business impact.
Create a structured view of opportunities and exposure.
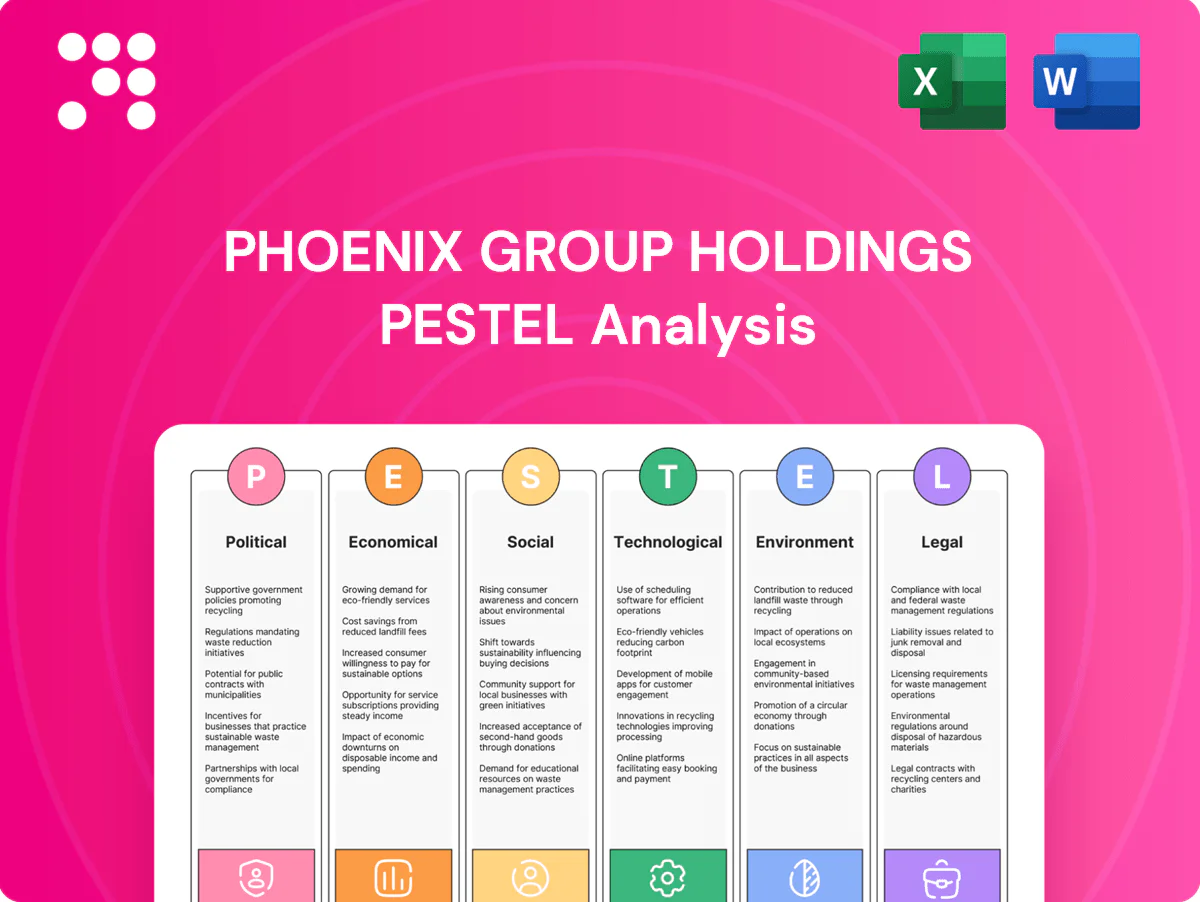
Stay ahead with our concise PESTLE analysis of Phoenix Group Holdings, revealing how regulation, demographics, and tech shifts affect its lifecycle business. We map risks and opportunities investors and strategists need to know. Ready-made and actionable, it saves research time. Purchase the full PESTLE for deep, exportable insights.
UK government focus on retirement adequacy, expansion of auto-enrolment (covering c.10m+ active savers) and State Pension rises (new State Pension £221.20/week in 2024/25) directly shape product demand; Phoenix must track consultations and adapt Standard Life offerings. Abolition of the lifetime allowance from Apr 2024 and ongoing tax-relief reviews can shift flows; policy stability aids long-duration planning, volatility raises execution risk.
Political backing for Solvency UK reforms in 2024–25 shapes capital flexibility and matching adjustment eligibility, directly influencing closed-book economics and BPA/annuity growth trajectories. Phoenix's engagement with HM Treasury and the PRA is strategic to optimise capital release and execution of M&A. Delays or reversals would constrain dividend distributions and reduce M&A headroom.
Mansion House capital markets reforms to channel pension capital into UK productive assets could prompt Phoenix Group, the UKs largest retirement business, to reassess strategic asset allocation and consider new asset classes if they deliver suitable risk-adjusted returns; Phoenix reported around £300bn of assets under management and administration in 2024. Political impetus must be balanced against fiduciary duty and PRA/BoE prudential limits. Clear stewardship positioning will mitigate reputational risk.
Debates over social care financing and retirement support reshape demand for Phoenix Group's annuities, decumulation and equity release products; ONS reports 12.7 million UK residents aged 65+ (mid‑2023), intensifying policy focus. Greater state provision could suppress private demand, while gaps increase reliance on insurers to fill funding shortfalls. Clear policy frameworks enable Phoenix to target equity release and decumulation offers and form advice partnerships.
Post-Brexit regulatory divergence since 2020 and shifting foreign policy have altered investment market access and talent mobility, with Phoenix—managing over £300bn in assets under administration—needing to factor increased cross-border frictions into portfolio and ALM decisions.
Stability in trade and geopolitics attracts capital and narrows spreads; uncertainty widens credit spreads and market volatility, as seen after 2022 sanctions episodes that constrained Russian exposure and EU market access.
Phoenix must embed sanctions screening, restricted market-access scenarios and policy advocacy for predictable rules to sustain long-term liabilities and investor commitments.
UK push on retirement adequacy, auto‑enrolment (c.10m+ active savers) and State Pension £221.20/week (2024/25) boosts demand for decumulation and annuities; abolition of the lifetime allowance (Apr 2024) shifts flows and planning. Solvency UK reforms (2024–25) and PRA engagement affect capital, matching adjustment and M&A headroom for Phoenix (assets c.£300bn). Social care debates (ONS 65+ = 12.7m mid‑2023) alter private demand and product mix.
| Factor | Metric | Implication |
|---|---|---|
| Retirement policy | State Pension £221.20/wk; auto‑enrolment ~10m | Higher decumulation demand |
 Detailed Word Document
Provides a concise PESTLE review of Phoenix Group Holdings, examining Political, Economic, Social, Technological, Environmental and Legal forces and their impact on strategy, operations and capital allocation. Each section uses current data and forward-looking insights to inform risk mitigation and growth opportunities for executives and investors.

 Customizable Excel Spreadsheet
Clean, visually segmented PESTLE summary of Phoenix Group Holdings that’s easily droppable into presentations or strategy packs, enabling quick stakeholder alignment and focused discussion on external risks and market positioning.
Discount rates and reinvestment yields drive Phoenix’s annuity pricing, reserve valuations and surplus generation; with Bank of England base rate around 5.25% and the UK 10‑year gilt near 4.0% (mid‑2025), higher rates have improved new business margins while pressuring bond and property valuations. The yield curve shape alters hedging and duration‑matching costs, and Phoenix’s cash generation depends on disciplined ALM to navigate rate shifts and reinvestment risk.
Sustained inflation above the Bank of England 2% target raises Phoenix’s expense base, inflation-linked liabilities and pressures on customers’ real incomes, requiring higher provisioning. ONS 2021–23 data showed life expectancy growth stalling, forcing adjustments to best-estimate mortality assumptions and capital buffers. Phoenix must calibrate prudently to protect solvency and dividend capacity and clearly communicate assumption changes to maintain investor confidence.
Closed-book returns for Phoenix rely on stable credit spreads and orderly markets for illiquid assets; a 100bp spread widening can materially boost annuity pricing yet increases default risk and capital strain. Spread moves in 2022–24 saw episodes above 150bp, underscoring the need for robust credit underwriting and quarterly stress testing. Liquidity buffers and with-profits backing are essential to support policyholder outcomes in stress.
Economic conditions drive sellers’ willingness to dispose of closed books; in 2024 weak markets increased motivated divestments while valuation multiples and funding costs—with UK gilt yields around 4.5% in mid-2024—dictate accretive opportunities. Phoenix’s scale (c.22m policies, ~£330bn AUA in 2024) enables administration synergies and capital optimisation, but financing becomes harder in downturns even as pipeline widens.
Income growth, employment levels and consumer confidence drive pension and ISA contributions; UK employment was ~75.8% in 2024 (ONS) and auto-enrolment membership reached ~10.9m (The Pensions Regulator, 2024), supporting Standard Life’s workplace pipeline. Cost-of-living pressures risk lower net inflows and higher lapses; Phoenix can counter with flexible products and targeted retention initiatives.
Higher Bank Rate (~5.25% mid‑2025) and UK 10y gilt (~4.0%) lift annuity margins but raise reinvestment, hedging and financing costs; credit spreads volatility (100–150bp moves 2022–24) affects closed‑book returns and capital. Employment (~75.8% 2024) and auto‑enrolment (~10.9m) support inflows; inflation and longevity trends pressure reserves.
| Metric | Value |
|---|---|
| Bank Rate | 5.25% |
| UK 10y gilt | 4.0% |
| Employment | 75.8% |
| Auto‑enrolment | 10.9m |
This PESTLE analysis of Phoenix Group Holdings evaluates political, economic, social, technological, legal, and environmental factors impacting the company and informs strategic and investment decisions. The content and structure shown in the preview is the same document you’ll download after payment. It’s fully formatted and ready to use.
An expanding retiree cohort—ONS projects UK residents aged 65+ to reach about 23% by 2038—increases demand for decumulation and longevity protection; Phoenix can tailor annuities, drawdown and equity release to diverse needs, offer clear guidance on sustainable withdrawal rates to build trust, and use segmentation by health and wealth to enhance targeted value propositions.
Consumer confidence drives persistency and cross-sell at Phoenix Group; the FCA’s Consumer Duty, effective July 2023, heightens the need for simple, transparent communications aligned to positive customer outcomes. Tools and education from organisations such as the Money and Pensions Service boost engagement with long-term products and support retention. A strong service culture reduces complaints and churn, improving lifetime value.
Customers expect seamless, mobile-first journeys with human support; Phoenix, owner of Standard Life since its 2018 acquisition, must meet that demand. Accessible design is vital given the UK had 12.3 million people aged 65+ (ONS mid-2023), a key retirement market. Platforms need robust self-service, advice triage and personalization. Consistent omni-channel experiences strengthen the Standard Life brand.
Rising demand for ESG and values-driven investing—with global sustainable assets topping $41 trillion in 2023 according to industry estimates—pushes Phoenix to offer sustainability-focused default funds and self-select options and to weave climate and stewardship narratives into member propositions. Authentic, measurable impact metrics and robust stewardship reporting are essential to counter greenwashing and meet member and employer expectations.
Ageing population: ONS projects 65+ to ~23% by 2038 (12.3m aged 65+ mid‑2023), raising demand for annuities, drawdown and later‑life advice.
Consumer protection: FCA Consumer Duty (Jul 2023) and Money and Pensions Service drive need for clear communications to boost persistency and reduce churn.
ESG & estates: global sustainable assets ~$41tn (2023); UK intergenerational wealth transfer ~£5.5tn (2020–2045) push ESG defaults and inheritance‑efficient products.
| Metric | Value |
|---|---|
| UK 65+ (mid‑2023) | 12.3m |
| 65+ share by 2038 | ~23% |
| Sustainable assets (2023) | $41tn |
| UK wealth transfer | £5.5tn (2020–2045) |
Acquisition-led growth has left Phoenix with a complex systems landscape as it manages around £300bn of assets (2024), driving urgent legacy modernization needs. Consolidating administration onto scalable platforms can unlock measurable unit cost savings, with industry pilots showing 10–25% reductions. High-quality data migration is vital for accurate valuations and PRA/FCA reporting. Phased decommissioning over 3–5 years reduces operational and regulatory risk.
Machine learning can enhance claims triage, lapse prediction and customer servicing at Phoenix Group, which manages over 16 million policies, improving targeting and reducing leakage. RPA deployments have cut operational backlog and shortened turnaround times in insurers by reported industry benchmarks; Phoenix cites automation to lift efficiency and support its cash generation targets. Explainability controls are required for model risk management and regulatory compliance.
Hybrid advice tools can broaden access while controlling distribution costs—industry studies show digital-first models cut advice delivery costs by up to 30%, supporting Phoenix Group’s c.£350bn assets under administration (2024). Personalization using behavioral and financial data improves engagement and outcomes, with targeted interventions lifting engagement by ~20%. Suitability and bias controls must be embedded and APIs enable employer and partner integrations at scale.
Life insurers hold extensive PII and financial data, making them prime targets; IBM reported the 2024 average breach cost for financial services at $5.97M. Zero‑trust architectures, end‑to‑end encryption and mature SOC capabilities are essential to reduce dwell time and loss. Outsourcer and cloud third‑party risk management must be tightened. Strong resilience underpins FCA Consumer Duty obligations introduced in 2023.
High-quality data underpins pricing, capital modelling and regulatory returns; IFRS 17 (effective 1 Jan 2023) and Solvency reporting demand granular, auditable data for cashflow and liability measurement.
Master data management and lineage tracking reduce valuation and reporting errors across systems; Phoenix Group manages over £200bn of policies and assets, amplifying the need for robust governance.
Analytics unlock targeted cross-sell and retention opportunities, improving customer lifetime value and capital efficiency.
Acquisition-driven legacy landscape across ~£300–350bn AUA (2024) requires 3–5 year modernization to cut unit costs 10–25% and meet IFRS17/Solvency data needs. ML/RPA can boost retention and efficiency across ~16m policies but need explainability and model governance. Cyber risk is material: 2024 avg breach cost $5.97M—zero-trust and third‑party controls essential.
| Metric | Value | Impact |
|---|---|---|
| AUA | £300–350bn (2024) | Scale/backlog |
FCA Consumer Duty final rules were published July 2022 and required firms to implement new standards from 31 July 2023 with full compliance by 31 July 2024; outcomes-focused requirements demand fair value, clear communication and robust customer support. Phoenix must evidence board-level oversight across both closed and open books and maintain remediation and management information frameworks. Non-compliance risks regulatory action, fines and reputational damage.
Capital reform in the UK alters matching adjustment eligibility, recalibrates the risk margin and narrows permitted asset classes, so Phoenix’s balance sheet management and hedging depend on the final PRA calibration. Robust model governance and ORSA are mandatory under PRA expectations to demonstrate capital adequacy and run-off plans. Ongoing dialogue with the PRA materially influences approvals and implementation timelines.
Processing c.16m policies and c.£300bn AUM at Phoenix Group demands strict consent mechanisms and strong security controls to manage customer data. Cross-border flows require lawful bases and UK SCCs or equivalent safeguards. Breach reporting timelines (72 hours under UK GDPR alignment) must be tested through incident drills. With fines up to 4% of global turnover and rising class actions, compliance is non-negotiable.
IFRS 17, effective 1 January 2023, reshapes profit emergence and KPIs, forcing Phoenix to revise investor communications and performance metrics. Climate disclosures under TCFD and ISSB demand scenario analysis and quantitative metrics such as GHG, transition risk and resilience testing. Phoenix must align systems, data controls and governance to sustain audit readiness. Transparent reporting underpins market confidence.
FCA Sustainability Disclosure Requirements (finalised July 2023) tighten marketing and anti-greenwashing rules: sustainability labels and guidance now require evidence-backed methodologies, clear metrics and documented KPIs; fund and mandate governance must demonstrably match stated ESG objectives; mislabeling risks enforcement, consumer redress and multi-million pound settlements.
Regulatory reforms (FCA Consumer Duty, PRA capital reforms, IFRS17, SDR) increase compliance costs and require board oversight, model governance and audit-ready controls; breaches risk fines (GDPR up to 4% global turnover) and reputational damage. Phoenix’s c.16m policies and c.£300bn AUM amplify operational and data-protection exposure, demanding robust remediation and PRA engagement.
| Metric | Value |
|---|---|
| Policies | c.16m |
| AUM | c.£300bn |
| GDPR fine cap | 4% global turnover |
| IFRS17 effective | 01-01-2023 |
Decarbonization policies, including the UKs legally binding net zero by 2050 and the Climate Change Committees 68% emissions reduction target for 2030, force repricing in carbon‑intensive sectors, increasing spreads and default probabilities.
Phoenix must integrate climate scenarios into ALM and credit selection to quantify transition-driven spread widening, duration mismatch and capital impacts.
Tilt strategies toward lower‑carbon corporates and green bonds can help preserve yield while reducing transition exposure, and active engagement alongside targeted exclusions supports balanced stewardship.
Extreme weather events—global insured losses reached about $120bn in 2023 (Munich Re)—can disrupt Phoenix Group's operations and issuers within its credit book. As a UK-focused life insurer, geographic concentration and sector sensitivities require close monitoring. Robust BCP and site resilience safeguard service continuity, while systematic supplier resilience assessments mitigate third-party gaps.
Phoenix Group has committed to net-zero by 2050 and stakeholders expect credible interim milestones and governance to bridge today and that target.
Phoenix can align investment glidepaths with insurance liability profiles to reduce transition risk and meet fiduciary duties.
Data gaps mean proxy metrics and continuous improvement are needed, and clear, regular updates ahead of 2025 reporting cycles build trust with regulators and customers.
Phoenix can use infrastructure debt, renewables and sustainable real assets to match long‑dated liabilities while meeting Solvency II matching adjustment eligibility through proper contract and cashflow structuring, keeping assets illiquidity and credit profile aligned with liabilities. Risk‑adjusted returns must satisfy PRA prudential standards and internal capital metrics, and partnerships can scale origination while limiting concentration risk.
Phoenix Group drives operational sustainability through energy efficiency, travel policies and waste reduction that have helped reduce its operational carbon emissions by c.45% versus a 2019 baseline, supporting its net-zero by 2050 commitment and lowering operating costs. Supplier codes extend this impact across the value chain, while transparent metrics improve ESG ratings and the company’s 2030 interim targets. Cultural integration embeds sustainability into investment and procurement decisions, increasing resilience and stakeholder trust.
UK decarbonisation (net zero by 2050; CCC 68% reduction target by 2030) forces repricing and higher credit spreads for carbon‑intensive issuers, requiring scenario-based ALM and credit stress testing.
Phoenix should tilt to green bonds, infrastructure debt and renewables to match long‑dated liabilities while its operational emissions are down c.45% vs 2019.
Extreme weather (global insured losses ~ $120bn in 2023) demands robust BCP, supplier resilience and credible interim targets ahead of 2025 reporting.
| Metric | Value |
|---|---|
| UK net‑zero | 2050 |
| CCC 2030 target | ~68% reduction |
| Phoenix operational emissions | -c.45% vs 2019 |
| Global insured losses 2023 | ~$120bn (Munich Re) |


