
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
THOR Industries faces intense buyer power and moderate supplier influence as scale and brand loyalty shape bargaining dynamics, while new entrants and substitutes present manageable threats due to capital intensity and product differentiation. Competitive rivalry remains high among established OEMs. Unlock the full Porter's Five Forces Analysis to explore THOR Industries’s competitive dynamics in detail.
THOR depends on a concentrated set of chassis and critical-component suppliers (Ford, Mercedes-Benz, Stellantis, Lippert, Dometic), exposing it to supplier leverage on pricing, lead times and allocations; THOR reported roughly $11.5 billion in 2024 revenue, amplifying the impact of supplier constraints. Switching costs are high due to engineering integration and certification, so THOR pursues multi-sourcing where feasible and uses scale-driven negotiations to mitigate risk and secure allocations.
Steel, aluminum, lumber, resins and foam face pronounced price swings, with suppliers able to pass through increases and compress THOR Industries' margins during upcycles; THOR reported margin pressure from commodity inflation in 2022–24. Long-term contracts and hedging reduced but did not eliminate volatility. THOR's scale purchasing partially offsets supplier bargaining power, yet input cost pass-through remains a recurring margin risk.
RV systems (HVAC, electrical, safety, emissions) require certified parts and vendor expertise, and THOR faced this supplier specialization amid its reported roughly $12.3 billion 2024 revenue, limiting volume-driven leverage.
Regulatory and warranty requirements legally restrict substitution, so unique component suppliers command premium pricing and lead-time control, raising their bargaining power.
THOR’s engineering depth and in-house testing reduce but do not eliminate dependency on certified vendors for critical assemblies.
Capacity tightness and shipping bottlenecks during demand spikes shift pricing power to suppliers, with component lead times often stretching 8–12 weeks, forcing THOR to carry higher inventory or pay rush premiums to meet production.
THOR relies on concentrated chassis and critical-component suppliers (Ford, Mercedes-Benz, Stellantis, Lippert, Dometic), giving suppliers pricing and allocation leverage; with 2024 revenue $12.3B this exposure can materially affect margins. High switching costs, certification needs and branded components increase supplier power despite THOR's scale, hedging and long-term contracts. Commodity volatility (steel, aluminum, lumber) and 8–12 week lead times sustain supplier pressure and inventory/rush-cost risk.
| Metric | 2024 | Impact |
|---|---|---|
| Revenue | $12.3B | Amplifies supplier risk |
| Lead times | 8–12 weeks | Raises inventory/rush costs |
| Commodity pressure | 2022–24 margin impact | Pass-through limits |
 Detailed Word Document
Uncovers key drivers of competition, customer influence, and market entry risks tailored exclusively to THOR Industries, analyzing its position within the RV and leisure-vehicle competitive landscape. Evaluates supplier and buyer power, substitutes, and disruptive threats that influence THOR’s pricing, margins, and strategic resilience.

 Customizable Excel Spreadsheet
A clear, one-sheet Porter's Five Forces summary for THOR Industries—perfect for quick decision-making, easily customize pressure levels for shifting RV market trends and copy into pitch decks or boardroom slides.
Independent dealers aggregate local demand and materially influence THOR’s model mix and pricing, with large dealer groups capturing over 50% of retail RV sales in 2024 and using scale to negotiate better margins and floorplan support. Dealer inventory health (shortages or bloated lots) directly alters THOR’s production cadence and working capital needs. THOR mitigates concentration risk through broad dealer coverage across North America and Europe.
RV purchases are discretionary and cyclical, making demand highly price elastic; 2024 retail unit sales remained roughly 30% below the 2018–2021 peak, amplifying buyer sensitivity. Consumers extensively cross-shop brands and models online, raising pricing transparency, while promotions and financing (increasingly central to conversions) sway purchase timing. THOR mitigates this by offering tiered portfolios across price points to capture different segments.
Buyers demand ready parts availability and responsive warranties; service quality directly drives repeat purchases and dealer leverage. Strong aftermarket programs and certified service networks reduce switching power by increasing lock-in. THOR’s scale — supported by over 1,700 dealer locations in 2024 — underpins broad parts distribution and warranty support.
Reviews, forums, and social media amplify consumer voice, and in 2024 about 88% of buyers consult online reviews, making specifications and pricing highly comparable; this transparency lowers switching costs and strengthens buyer power. THOR offsets this by investing in product differentiation and brand equity, maintaining premium positioning and dealer networks to retain margins.
Financing dependence: retail and dealer floorplan financing conditions directly shape affordability and ordering for THOR; in 2024 dealer credit tightening contributed to softer retail demand and deferred purchases, increasing buyer leverage. THOR saw incentive spending rise to preserve volume, while lender partnerships helped sustain throughput and used-vehicle trade activity.
Independent dealers (large groups >50% of retail sales in 2024) heavily influence THOR’s pricing, model mix and production; dealer inventory swings and floorplan tightening in 2024 tightened orders. Retail demand remained ~30% below the 2018–21 peak in 2024, raising price sensitivity while 88% of buyers consult online reviews. THOR’s 1,700+ dealers and elevated incentive/finance support in 2024 mitigate buyer leverage.
| Metric | 2024 |
|---|---|
| Dealer concentration | >50% |
| Retail sales vs peak | -30% |
| Buyers consulting reviews | 88% |
| Dealer locations | 1,700+ |
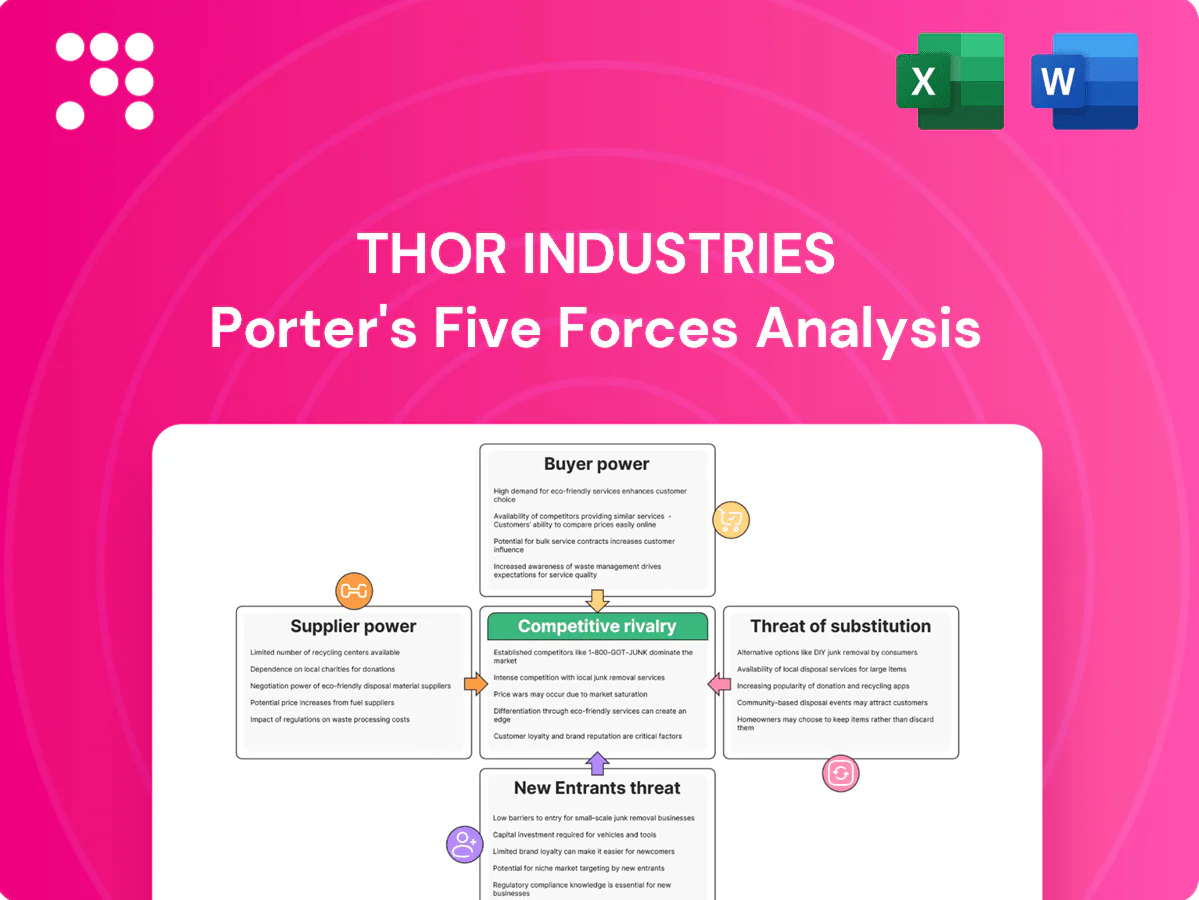
This preview displays the full THOR Industries Porter’s Five Forces analysis you’ll receive—no placeholders or excerpts. The document is professionally formatted, immediately downloadable upon purchase. It covers competitive rivalry, supplier and buyer power, threats of entry and substitutes. What you see is exactly what you’ll get.
Competition from Forest River (Berkshire Hathaway) and Winnebago is intense, with THOR facing rivals across both towable and motorized segments; U.S. RV wholesale shipments totaled about 491,000 units in 2024, keeping channel pressure high. Capacity and price moves quickly ripple through dealers and suppliers, affecting margins industry-wide. THOR’s 2024 net sales near $11.8 billion and its broad portfolio and scale support share defense against nimble peers.
High fixed costs from THOR Industries large manufacturing footprint and labor force create strong utilization pressure; FY2024 net sales were $9.6 billion, so during downturns firms discount to keep plants running, intensifying price competition and rivalry, while investments in flexible production lines help align output with demand and reduce margin erosion.
Many features converge across brands, enabling easy comparisons; THOR's portfolio spans over 20 brands, amplifying intra-industry parity. Differentiation rests on build quality, floorplans, weight and tech integrations, with model refreshes occurring on roughly annual cycles. Rapid incremental innovation compresses margins for novel features, but THOR uses design variety and layered brand architecture to preserve pricing power.
Market share contests at dealers play out through spiffs, rebates and floorplan support, with incentives in 2024 rising to as much as 6% of MSRP in peak promotions, compressing industry margins. Inventory cycles force tactical pricing, while THOR countered with disciplined allocation and mix management to protect profitability.
Rivalry extends into Europe where stricter safety and emissions rules and different consumer preferences raise product adaptation costs. Local brands and import duties push THOR to balance pricing against margin pressure. Currency moves change competitiveness—EUR averaged about 1.09 USD in 2024. THOR’s European subsidiaries, notably Erwin Hymer Group (acquired 2019), tailor models to regional needs.
Competition is intense from Forest River and Winnebago across towable and motorized segments; U.S. RV wholesale shipments were about 491,000 units in 2024, keeping dealer pressure high. THOR’s broad portfolio and scale (net sales ~ $11.8B in 2024) help defend share, but peak dealer incentives (~6% of MSRP) and high fixed costs force tactical pricing. European operations face regulatory adaptation costs and EUR/USD ~1.09 (2024 avg).
| Metric | 2024 |
|---|---|
| U.S. wholesale shipments | 491,000 units |
| THOR net sales | $11.8B |
| Peak dealer incentives | ~6% of MSRP |
| EUR/USD average | 1.09 |
Airbnb, hotels, cruises and packaged tours provide clear non-RV substitutes; Airbnb reported roughly 6 million listings in 2024, expanding short-stay options. When fares and package prices fall or convenience rises, substitution into fly-and-stay or cruises strengthens. Younger cohorts increasingly favor point-to-point travel and curated experiences. THOR counters by stressing RV flexibility and ownership economics.
Pre-owned RVs, typically priced 30-50% below new units, provide a lower-cost alternative that can materially divert demand from new Thor models. A sizable used inventory in 2024 depressed new-unit orders as buyers opted for value and immediate availability. Warranty and customization gaps constrain substitution but do not eliminate it, especially for budget-conscious buyers. Certified pre-owned programs help recapture buyers into the Thor ecosystem.
Custom van conversions and upfitters compete on uniqueness and lower upfront cost, fueled by social media—#vanlife exceeded 10 million Instagram posts in 2024—drawing adventure seekers. Regulatory compliance, safety standards, and OEM warranties favor established builders on liability and resale. THOR addresses this niche with factory-built campervans like Sequence and Tellaro plus dealer-backed warranties.
Rooftop tents, towable tiny homes and overlanding rigs increasingly substitute entry-level RVs; rooftop tent market activity rose notably into 2024, while many towable tiny homes list for under $30,000 versus average new small travel trailers at $25k–$40k. Lower acquisition cost boosts appeal, but comfort/practicality trade-offs limit long-trip adoption; THOR’s lightweight towables target that middle ground.
Peer-to-peer RV rentals let consumers access RVs without ownership, which can defer purchases but also introduce users to the lifestyle and seed future ownership; platforms expanded notably by 2024 per industry reports. Higher fleet utilization from sharing compresses traditional dealer sales cycles, yet THOR can benefit if rental fleets refresh with new units and place wholesale orders.
Substitutes (Airbnb, rentals, used RVs, vans, rooftop tents) meaningfully pressure THOR; Airbnb ~6M listings in 2024 and P2P RV platforms grew ~20% YOY. Pre-owned units 30–50% cheaper depressed new orders in 2024. Alternatives <$30k expand entry demand while rentals defer purchases but seed future ownership.
| Substitute | 2024 metric | Impact |
|---|---|---|
| Airbnb/Hotels | ~6M listings | Lower short-trip RV demand |
| Pre-owned RVs | 30–50% cheaper | Diverts new sales |
| Rooftop tents/vanlife | <$30k options | Entry-level substitution |
Establishing plants, supply chains, and a nationwide dealer network demands substantial capital, creating a high fixed-cost hurdle for new RV entrants. Economies of scale in procurement and production allow THOR to lower per-unit costs and negotiate supplier terms incumbent firms cannot match. These scale advantages produce persistent cost disadvantages for newcomers, widening the competitive gap.
Complex US FMVSS, EPA emissions and electrical standards plus EU WLTP and UNECE rules mean RV design must meet multiple regimes, increasing engineering burden. Certification and specialized testing commonly exceed $1 million and add 12–18 months to product cycles, while liability insurance and warranty reserves raise upfront capital needs. These barriers deter new entrants; Thor’s accumulated compliance know-how and supplier relationships act as a durable moat.
Dealers prioritize proven sell-through and after-sales serviceability, favoring established lines over unproven entrants. New brands struggle to secure prime floor space and allocation from dealers focused on turnover and parts support. Building brand trust and service networks typically takes years. As of 2024 THOR’s multi-brand portfolio — including Airstream, Jayco, Heartland and Dutchmen — occupies key dealer slots.
Supply chain relationships sharply limit new entrants: in 2024 chassis and key-component availability remained tight, with preferred allocations flowing to established OEMs, leaving newcomers exposed to rationing and volatile lead times; long-standing supplier ties and allocation agreements protect incumbents and raise entry costs.
RV assembly combines complex fit-and-finish with heavy warranty exposure, so early quality issues can quickly hit reputation and margins; THOR’s scale and multiyear feedback loops raise the learning-curve hurdle for entrants.
High capital and dealer-network needs, plus THOR’s 2024 ~35% US market share, create steep entry costs. Certification/testing often exceed $1 million and add 12–18 months to launches. 2024 chassis rationing and supplier allocations favor incumbents, raising lead-time and warranty risks that deter newcomers.
| Barrier | 2024 Data |
|---|---|
| Market share | THOR ~35% |
| Certification cost/time | $1M+, 12–18 months |
| Supply | Chassis rationing, preference to incumbents |


