
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
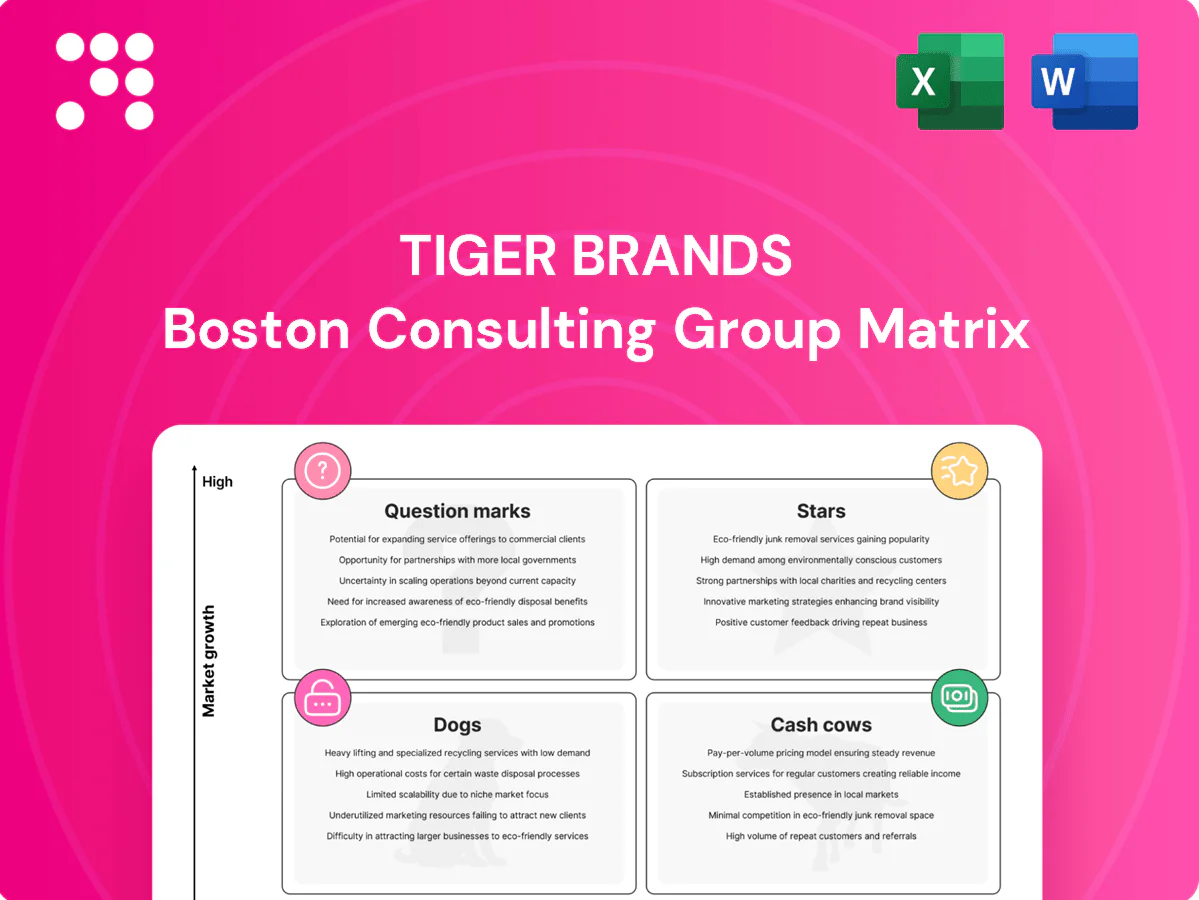
Tiger Brands’ BCG Matrix preview shows which product lines are driving growth and which are quietly bleeding cash — a quick snapshot, but there’s more under the hood. Buy the full BCG Matrix to get quadrant-by-quadrant placements, data-backed recommendations, and a clear plan for where to invest, divest, or double down. Delivered in Word and Excel, it’s ready to present and act on—no extra digging. Purchase now and turn this strategic map into your next set of confident decisions.
Baby & toddler nutrition is a high-share Tiger Brands growth engine as parents keep trading up, with the global infant formula and baby food market estimated at about $87bn in 2024 and premium segments outpacing core demand. These lines lead the basket and deserve outsized shelf, sampling, and trust-building spends to protect velocity. Keep the brand halo strong and innovation tight on formats and textures; hold share now and it matures into a cash cow.
Snack category is expanding within Tiger Brands and better-for-you segments (protein, low-sugar, portion-controlled packs) are outpacing core snacks, showing higher retail velocities in 2023–24 channel scans.
To sustain share, constant promotions, NPD cadence and influencer-led awareness are required to maintain trial and velocity.
Protect price-pack architecture as competitors increase entry, preserving margin tiers and value/portion balance.
Convenience keeps winning in busy South African households (≈19 million households in 2024), driving demand for ready-to-cook meal solutions. Tiger Brands, with established leadership across sauces, mixes and bases, leverages high shelf presence and strong retailer listings. Continue to fuel distribution, in-store theatre and quick-turn innovation to sustain momentum. If category growth cools, it can transition neatly into cash cow status for the portfolio.
Premium sauces and condiments remain Stars for Tiger Brands as trading-up persisted in 2024, with premium variants outpacing mainstream (global premium condiment growth c.6% in 2024). Leadership is urban, retail-led with strong gross margins but elevated A&P intensity; chef-led SKUs and limited runs sustain distinctiveness. Invest now to secure distribution before crowding compresses returns.
Fruit cordials and family beverages are Stars: household staples with strong repeat purchase behavior in a growing sub-segment, driven by taste and multi-serve value.
Big brand memory supports share but trade promotions and paid shelf placement remain key to volume; maintain distribution while category expansion continues.
Stars: baby & toddler nutrition (global infant formula ~$87bn 2024) and premium sauces (premium condiments ~6% growth 2024) drive high share growth; snacks better-for-you and fruit beverages show above-category velocity in SA (≈19m households 2024). Invest distribution, NPD cadence and promo to lock share, protect price-pack architecture and convert to cash cows as growth normalises.
| Category | 2024 growth | Share | Margin | Priority action |
|---|---|---|---|---|
| Baby & toddler nutrition | — | High | High | Shelf, sampling, trust spend |
| Better-for-you snacks | >category | Growing | Mid | NPD + influencer |
| Premium sauces | ~6% | Leader | High | Lock distribution |
| Fruit beverages | Stable+ | Strong | Mid | Promotion ROI |
 Detailed Word Document
In-depth BCG Matrix review of Tiger Brands' portfolio, outlining Stars, Cash Cows, Question Marks and Dogs with strategic actions.

 Customizable Excel Spreadsheet
One-page Tiger Brands BCG Matrix highlighting pain points and action priorities for quick C-suite decisions.
Mature, massive and efficient—Tiger Brands grains and breakfast cereals remain cash cows with steady volumes in 2024 delivering predictable cash generation. Scale advantages in milling, oats and cereals sustain healthy margins via procurement and production efficiencies. Minimal A&P spend keeps focus on factory yields and route‑to‑market; milk it to fund the next wave.
Canned foods and pantry staples show high household penetration in South Africa and deliver low-single-digit category growth in 2024, making volume gains modest but consistent. Distribution is entrenched, trade and promo playbooks are established, so margin uplift comes from optimizing pack sizes, trade terms and sourcing rather than splashy advertising. The segment remains a reliable cash generator for Tiger Brands in 2024.
Core spreads and table sauces are mainstream, price-fighter lines that still move tonnage and sit in a low single-digit growth category; scale and strong brand recognition drive efficient cash conversion for Tiger Brands. Guard share with smart price-pack ladders rather than big ad budgets to protect margin. Recycle surplus cash to fund Stars and selective strategic bets.
Flour, baking aids and dry goods are core staples for Tiger Brands, delivering stable consumer demand and predictable margins; in 2024 the staples cluster remained a significant cash contributor to the group.
Operational leverage is realised through procurement scale, waste reduction initiatives and improved plant uptime, driving steady EBITDA conversion month after month.
Maintain shelf presence and a disciplined promo cadence rather than innovation-heavy spend; the portfolio quietly generates recurring cash for the business.
Classic confectionery are Tiger Brands cash cows: iconic treats with loyal repeat buyers, modest category growth and predictable seasonal peaks that deliver high throughput and attractive margins; production must stay tight and efficient, bank the cash and avoid SKU creep.
Mature staples and confectionery were Tiger Brands cash cows in 2024, delivering steady volumes and predictable cash generation. Scale in milling, pantry and confectionery drove margin resilience via procurement and plant efficiencies. Focus remained on shelf presence and disciplined promos to protect cash conversion. Surplus cash prioritised funding Stars and strategic bets.
| Category | 2024 trend | Margin driver | Role |
|---|---|---|---|
| Grains & cereals | Stable volumes | Scale procurement | Primary cash |
| Pantry & canned | High penetration | Distribution | Reliable cash |
| Confectionery | Seasonal peaks | Throughput | Supplemental cash |
The Tiger Brands BCG Matrix you're previewing is the exact file you'll receive after purchase—no watermarks, no drafts, just the finished analysis. It maps Tiger Brands' portfolio across stars, cash cows, question marks and dogs with clear visuals and actionable insight. Ready to edit, print or present, the report is crafted for strategic clarity and immediate use. Buy once and get the professional, fully formatted document delivered straight to your inbox.
Low-share niche beverages are small sub-categories with little growth and tough price points, tying up working capital and chilling in the warehouse. Turnarounds are costly and seldom pay back, making these lines prime candidates for pruning to free up cash and shelf space.
Dogs: Legacy home and personal care tails are non-core, slow-growth items that dilute focus and resources and neither earn nor burn much but clog the system. They are hard to premiumize and hard to scale, yielding low margins and limited share gains. Consider exit or license-out to free capital for core food brands and higher-return initiatives. Divestiture would streamline operations and improve ROIC.
Over-fragmented pack/variant SKUs that don’t turn fast enough drag on complexity, increasing planning time, line changeovers, and inventory carrying costs. Low share, low momentum variants act as cash traps and erode margins. Rationalize aggressively by pruning slow-moving SKUs and reallocating shelf space to core winners to restore operational efficiency.
Seasonal novelty confectionery is fun but delivers low repeat purchase and is confined to short windows, driving inventory risk and heavy markdowns that erode margins and cash conversion.
Underperforming export SKUs: thin 2024 volumes spread across too many markets leave unit economics weak; logistics and compliance costs (freight, tariffs, customs) erode already slim margins, and low share plus low market growth make the math unattractive for Tiger Brands.
Dogs: legacy home & personal-care tails delivered low growth and weak margins in 2024, tying up working capital and raising inventory days; recommend exit or license-out to redeploy capital to core food brands. Prune slow SKUs, consolidate markets, and cut seasonal novelties to improve ROIC and reduce complexity.
| Metric | 2024 |
|---|---|
| Sales | R350m |
| Margin | 4% |
| SKU count | 180 |
| Inventory days | 120 |
Plant-based and alternative proteins sit as a Question Mark for Tiger Brands: consumer interest is rising globally (plant-based meat market ~US$7–8 billion in 2023) but the company currently holds only an early share. Landing products will require heavy R&D, extensive tastings and precise pricing to compete in value-sensitive South African channels. If traction builds quickly it can climb to Star status; if not, the play should be exited fast.
Health trend is strong but Tiger Brands' functional and low-sugar beverages remain a Question Mark with limited share; global low- and no-sugar soft drinks grew about 6% in 2023, signaling upside for credible entrants.
Success requires targeted launches, verifiable health claims and cold-chain or formulation expertise; upfront marketing and R&D burn will be high before velocities stabilize.
Allocate capex and marketing to back winners aggressively and discontinue low-velocity SKUs to avoid prolonged cash drain.
Direct-to-consumer and e-grocery packs are a Question Mark: the channel is growing rapidly (South African e-grocery volumes rose ~20% in 2024) but Tiger Brands’ direct share remains nascent, under 5% of group sales.
Success requires new pack architecture, subscription models and stronger data capabilities to drive repeat purchase and personalization. Unit economics are delicate at low scale, with acquisition costs outpacing margin unless cohorts are tightly targeted. Test-and-learn pilots with narrow cohorts and clear LTV/CAC thresholds are essential.
Premium baby snacks and on-the-go is a question mark: category growth is real but incumbents in South Africa and key export markets remain fierce, requiring strong trust cues, clean labels and pediatric endorsements to convert. Win in chemists and top-tier grocers first, then widen distribution. Double down only if repeat purchase rates and retention metrics sustain post-trial.
African regional adjacencies are Question Marks: attractive consumer growth (sub-Saharan GDP ~3.5% in 2024, IMF) but Tiger Brands holds low share in many markets, requiring heavy route-to-market and regulatory lift. Portfolio fit is good, yet capital discipline is critical; invest behind a few beachheads rather than broad roll‑out.
Plant-based (~US$7–8bn global 2023) and functional beverages, DTC (<5% sales), premium baby snacks and African adjacencies (sub‑Saharan GDP ~3.5% 2024) are Question Marks for Tiger Brands; current shares mostly <10%. Success needs heavy R&D/marketing, selective capex and strict LTV/CAC thresholds; exit low-velocity plays fast.
| Category | 2023/24 metric | TB position | Action |
|---|---|---|---|
| Plant-based | US$7–8bn (2023) | Early share | R&D, pricing test |
| DTC/e-grocery | +20% vol (SA 2024) | <5% sales | Pilot cohorts, LTV/CAC |
| Africa | GDP ~3.5% (2024) | <10% share | Selective beachheads |


