
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
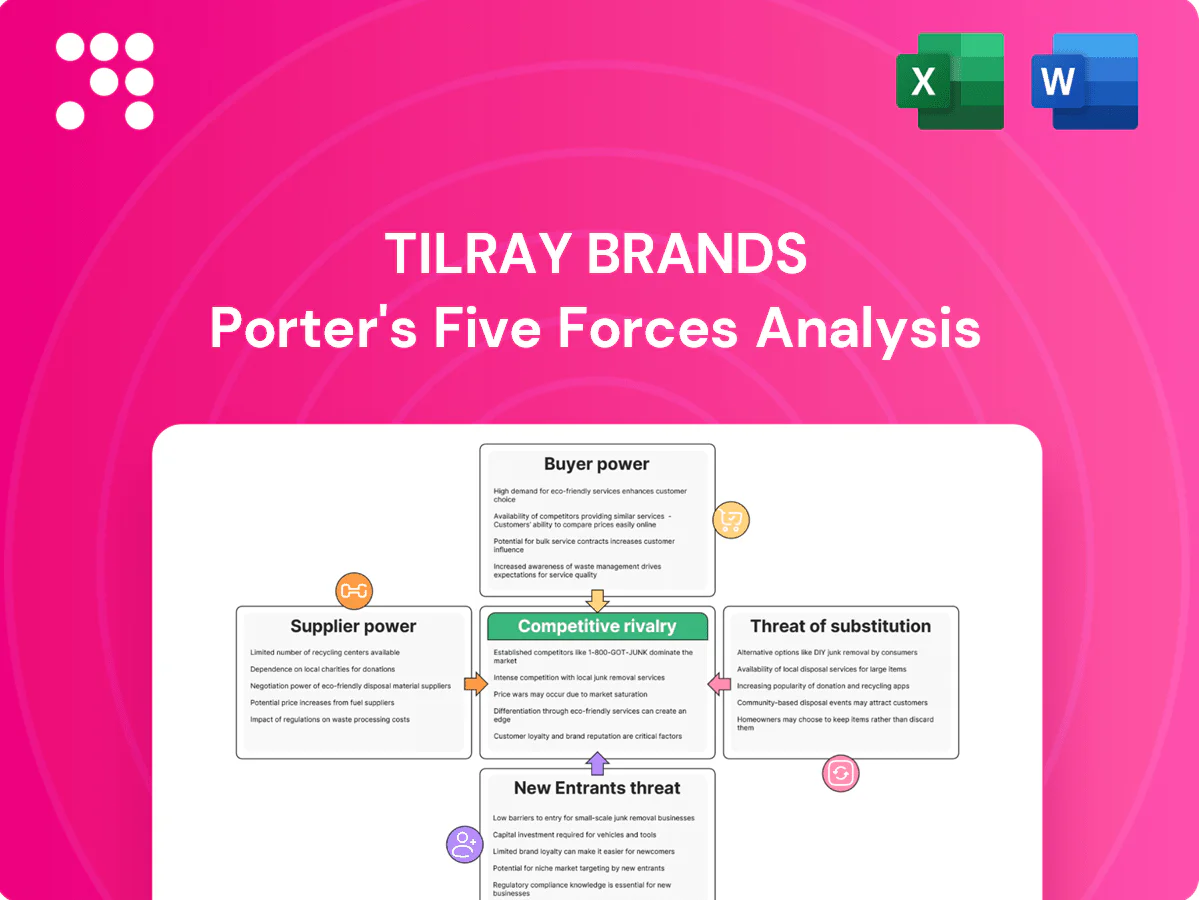
Tilray Brands faces high competitive rivalry and evolving substitute threats as cannabis commoditization and regulatory shifts pressure margins; supplier and buyer power vary across medical, adult-use, and international markets while barriers to entry hinge on compliance and capital intensity. This snapshot hints at strategic weak points and growth levers. Unlock the full Porter's Five Forces Analysis for force-by-force ratings, visuals, and actionable strategy.
Medical-grade cannabis inputs, pharmaceutical excipients and EU-GMP compliant materials sharply narrow approved suppliers, concentrating sourcing for Tilray and raising audit-driven switching costs that modestly boost supplier leverage. Tilray’s scale and comprehensive quality systems and multiple vendor qualifications mitigate single-supplier risk. Any compliance breach, however, can abruptly eliminate alternatives and tighten supply rapidly.
Packaging and commodity bottlenecks—glass bottles, aluminum cans, labels, CO2 and specialty packaging—face cyclical shortages and concentrated supplier bases that raise price pass-through risk; Tilray Brands benefits from multi-brand volume improving contract leverage but reliance on spot procurement can produce sharp cost spikes, while long-term agreements partially hedge volatility.
Seeds, clones, nutrients and specialized genetics are differentiators with limited substitutability, giving upstream breeders pricing power when strains show superior yield or cannabinoid profiles. Proprietary high-performance genetics can grant breeders leverage in negotiations, while Tilray’s vertical cultivation and in-house R&D materially reduce supplier dependence. IP agreements and breeding programs expand genetic sources and mitigate single-supplier risk.
In beverage alcohol and wellness select co-packers control scarce QA-certified capacity, so tight windows can temporarily shift bargaining power to suppliers; Tilray mitigates this by mixing in-house brewing with third-party partners to smooth peaks and protect margins. Multi-year volume commitments and a diversified plant footprint reduce single-supplier exposure and limit price pressure.
Logistics and EU narcotics import agents act as critical gatekeepers with licensed lanes that are hard to replicate, increasing supplier bargaining power. Tilray Brands reported fiscal 2024 net revenue of about US$1.1 billion, using its global footprint to benchmark and multi-home across lanes. Performance-based SLAs and dual-sourcing reduce single-supplier dependence and blunt that power.
Concentrated, compliance-driven suppliers (EU-GMP, QA co-packers, licensed logistics) raise switching costs and episodic price power against Tilray; scale and vertical cultivation plus multi-vendor qualification blunt this. Commodity and packaging shortages create short-term pass-through risk; long-term contracts and dual-sourcing reduce volatility. A compliance breach can instantly tighten supply and pricing.
| Metric | 2024 | Impact |
|---|---|---|
| Net revenue | ~US$1.1B | Enhances contract leverage |
 Detailed Word Document
Tailored Porter's Five Forces analysis for Tilray Brands that uncovers key drivers of competitive rivalry, buyer and supplier power, threat of new entrants and substitutes, and highlights disruptive forces and strategic levers affecting pricing, margins, and market share.

 Customizable Excel Spreadsheet
A concise Porter's Five Forces snapshot for Tilray Brands—clear, copy-ready force ratings and a spider chart to instantly reveal competitive pressure; easily customize inputs for evolving regulations, new entrants, or M&A scenarios.
Canadian provincial wholesalers such as OCS and SQDC and Germany’s roughly 19,000 pharmacies/wholesalers aggregate buying power, using scale and listing control to dictate pricing and shelf access.
They enforce strong chargebacks, delistings and strict compliance requirements that compress supplier margins.
Tilray’s broad product breadth and distribution reach improve negotiation leverage but do not eliminate this concentrated buyer power.
Large U.S. and EU beverage retailers and three-tier distributors, present in all 50 U.S. states, can demand promotional spend and favorable margins, controlling access to cold box and tap handles that determine shelf and draft presence. Consolidation among retailers and distributors increases their leverage over suppliers, forcing brands to concede placement and trade spend. Tilray often trades portfolio breadth for these placements to secure distribution and visibility.
End-consumer price sensitivity is high as recreational cannabis and beer buyers face low switching costs and abundant choice; Canada’s retail cannabis footprint reached about 3,800 stores in 2024, intensifying price competition. Price compression in Canada has driven deal-seeking and promotion-heavy strategies, while Tilray leverages brand equity, differentiated formats and loyalty programs to soften elasticity and reduce churn.
Medical payers and prescribers heavily shape product selection through reimbursement policies, formularies and documentation requirements that can divert demand toward covered dose forms; this gives prescribers and payers strong leverage over pricing and preferred formulations. Tilray’s ~USD 1.0 billion FY2024 revenue scale, investments in clinical programs and GMP/ISO quality certifications strengthen its negotiating position by supporting formulary inclusion and premium pricing.
Retailers' push for private-label SKUs (private label reached about 18.6% of US grocery sales in 2024) compresses branded margins and raises substitution risk, increasing buyer power; Tilray can win volume by manufacturing house brands but faces brand dilution and lower margin mix; disciplined portfolio segmentation protects premium tiers and preserves brand equity.
Concentrated buyers (Canadian provincials, ~3,800 Canadian stores in 2024, ~19,000 German pharmacies) exert strong price/shelf control, driving chargebacks and delistings.
Retail/distributor consolidation and private-label growth (US grocery private label 18.6% 2024) compress supplier margins despite Tilray’s ~USD 1.0B FY2024 scale.
Medical payers/formularies further steer demand; Tilray’s GMP/clinical investments mitigate but do not eliminate pressure.
| Metric | 2024 |
|---|---|
| Tilray revenue | ~USD 1.0B |
| Canada retail stores | ~3,800 |
| German pharmacies | ~19,000 |
| US private label share | 18.6% |
This Porter’s Five Forces analysis for Tilray Brands evaluates competitive rivalry, supplier and buyer power, and threats from new entrants and substitutes, with actionable implications for strategy and valuation. This preview shows the exact document you'll receive immediately after purchase—no surprises, no placeholders. The file is professionally formatted and ready for immediate use.
Crowded Canadian cannabis market fuels intense rivalry as overcapacity and over 1,000 licensed producers drive price wars and margin compression.
Frequent SKU rotation and heavy promotions across retail channels amplify competition, while consolidation—notably Tilray’s 2021 merger with Aphria—aims for scale efficiencies.
Despite M&A, rivalry stays high due to low product differentiation and uniform federal regulation limiting competitive levers.
Craft and macro brewers battle for share amid flat volumes (US beer volumes down ~0.5% in 2023) and shifting tastes; craft holds roughly 14% by volume while the top four brewers control about 70% of the market. Tap handle, shelf and cooler space are zero-sum contests and giants wield massive marketing and distributor clout. Tilray competes via regional brands, innovation and portfolio breadth.
Untaxed channels undercut legal pricing by up to 30% and sustained an estimated ~30% market share in key markets in 2024, keeping downward pressure on Tilray Brands’ gross margins. Quality, testing and safety credentials allow Tilray to charge premiums but cannot fully close price gaps versus illicit supply. As markets mature, illicit share has trended down from ~50% pre-legalization toward ~30% in 2024, narrowing but not eliminating margin strain.
Rivals frequently launch new strains, formats, RTDs and wellness SKUs, compressing first-mover advantages as fast copycat cycles shorten time-to-market; Tilray reported FY2024 net revenue of about US$1.4 billion and counters with operational agility and data-driven assortment to protect margins. Tilray leverages multi-category R&D to refresh pipelines across cannabis, beverages and wellness.
Global expansion is a core battleground as companies vie for early positions in Germany, the EU and a potential U.S. federal market, with GMP capacity, licensed partnerships and distribution rights contested fiercely; Tilray reported fiscal 2024 net revenue of $1.02 billion and leverages GMP facilities in Europe while facing equally ambitious peers accelerating regulatory filings and M&A to win first-mover advantages.
Crowded Canadian market with over 1,000 licensed producers drives price wars and margin compression. Untaxed channels held ~30% share in 2024 and undercut legal pricing by up to 30%, keeping downward pressure on margins. Tilray reported FY2024 revenue ≈ US$1.4B and leverages scale, GMP Europe capacity and M&A to defend share.
| Metric | Value |
|---|---|
| Licensed producers (Canada) | >1,000 |
| Illicit market share (2024) | ~30% |
| Price undercut | Up to 30% |
| Tilray FY2024 revenue | US$1.4B |
Consumers fluidly switch between beer, spirits, RTDs and cannabis by occasion, with US legal cannabis sales exceeding $25 billion in 2023–24 and RTDs capturing growing share. Health and wellness trends (lower-ABV, CBD/THC alternatives) are shifting spend away from traditional alcohol. Tilray’s dual alcohol and cannabis footprint buffers cross-substitution but does not remove the risk. Portfolio synergies aim to capture consumer spend regardless of choice.
Pain, anxiety and sleep needs are often met by prescription and OTC remedies, with the global pharmaceutical market exceeding $1.5 trillion in 2023 (IQVIA), and widespread insurance and physician guidance reinforcing these substitutes. Superior randomized‑trial efficacy and safety data anchor patient and payer loyalty to pharma options. Medical‑grade cannabis must therefore demonstrate comparable outcomes and safety profiles to erode this advantage.
Nutraceuticals, adaptogens and functional beverages—a global nutraceuticals market that surpassed $400 billion in 2024 with roughly 7% CAGR—offer perceived natural relief and are widely available through mainstream retail and e‑commerce, lowering barriers to trial. Light regulation and lower price points versus cannabis enhance substitutability, while Tilray’s wellness SKUs provide counter-programming but face intense shelf and digital competition for consumer attention and margin pressure.
Hemp-derived delta-8/THC variants sold in many U.S. jurisdictions have bypassed state cannabis frameworks, increasing substitution pressure on Tilray by offering cheaper, legal-ambiguous alternatives; FDA issued multiple consumer-safety alerts in 2023–24 and regulatory risk is rising. Convenience and online storefronts amplify switching; CDC data show 4.5% adult e-cigarette use (2022), highlighting nicotine vapes/pouches as competing mood-spend options. Tightening state and federal rules in 2024 could rapidly compress these substitute channels.
Untaxed cannabis remains a ready substitute for legal Tilray offerings: Statistics Canada estimated roughly 40% of consumer cannabis purchases stayed in the illicit market in 2023–24, sustaining price-sensitive demand.
Illicit sellers often offer wider SKU variety and lower prices, drawing consumers despite quality and safety trade-offs that deter higher-income or health-conscious segments; enforcement intensity (seizures and prosecutions) directly reduces substitution pressure.
Substitutes (alcohol, pharma, nutraceuticals, hemp THC, illicit) materially pressure Tilray: US legal cannabis >25B (2023–24), pharma >1.5T (2023), nutraceuticals >400B (2024); illicit ~40% share (StatsCan 2023–24). Dual alcohol/cannabis footprint mitigates but does not eliminate cross‑substitution risk.
| Substitute | 2023–24 metric |
|---|---|
| US legal cannabis | >25B |
| Pharma global | >1.5T (2023) |
| Nutraceuticals | >400B (2024) |
| Illicit cannabis (CA) | ~40% |
Cannabis cultivation, processing and EU-GMP distribution demand formal approvals and recurring audits; EU-GMP certification is mandatory for EU medicinal supply and audits often occur annually. Licensing timelines commonly run 12–24 months and upfront compliance, security and facility upgrades frequently exceed $1m annually, deterring casual entrants while well-capitalized pharma or CPG players with established quality systems can absorb these costs and enter the market.
Building cultivation, brewing, QA labs and brands demands heavy investment, and Tilray reported consolidated net revenue of about US$1.1 billion in fiscal 2024, underscoring the scale needed to compete. Price compression across cannabis and beverage categories elongates payback periods and raises capital risk for new entrants. Scale drives unit-cost competitiveness in cultivation and brewing, and Tilray’s existing production footprint and multi-brand portfolio create meaningful deterrence.
Winning shelf, tap and provincial listings requires deep retailer relationships and proven velocity; distributors prioritize established portfolios, making new entrants pay slotting fees often in the low five figures and accept limited cold-box access. In 2024 Tilray reported roughly US$1.0 billion in net revenue, and its multi-category cannabis, beverage and wellness portfolio gives it gatekeeping advantage across retail and provincial channels.
GMP, stability data, and validated processes are nontrivial to replicate; failures can trigger product recalls and jeopardize licenses, raising both initial and ongoing fixed costs for entrants and increasing regulatory scrutiny in medical channels.
Tilray’s established compliance track record and existing validated facilities act as a moat in medical segments, making market entry costlier and slower for new competitors.
High regulatory barriers (EU-GMP, stability data, licensing 12–24 months) and >$1m annual compliance costs deter casual entrants while pharma/CPG can absorb them. Tilray’s fiscal 2024 net revenue ~US$1.1B and existing production/brand scale create cost and distribution moats; US legal cannabis sales were ~US$29B in 2023, keeping incumbents attractive for M&A.
| Metric | Value |
|---|---|
| Tilray FY2024 revenue | US$1.1B |
| US legal cannabis sales (2023) | US$29B |
| Typical licensing timeline | 12–24 months |


