
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Uncover the strategic positioning of TransAlta's diverse business units with our comprehensive BCG Matrix analysis. See which segments are driving growth and which require careful management.
This preview highlights key insights, but to truly understand TransAlta's competitive landscape and make informed decisions, you need the full picture. Purchase the complete BCG Matrix for a detailed breakdown of Stars, Cash Cows, Dogs, and Question Marks, along with actionable strategic recommendations.
Don't miss out on the opportunity to gain a competitive edge. Get the full BCG Matrix report today and unlock the strategic roadmap to optimize TransAlta's portfolio.
TransAlta's new wind and solar facilities represent a significant investment in the company's future. In 2024, they completed major projects like White Rock and Horizon Hill in Oklahoma, adding over 500 MW of clean energy capacity.
These developments are crucial for TransAlta's growth strategy, especially given the increasing demand for renewable energy. The company secured long-term power purchase agreements with entities like Amazon Energy for these facilities, ensuring predictable revenue streams.
TransAlta's grid-scale battery storage projects, like the 180 MW WaterCharger, are firmly in the 'Question Mark' quadrant of the BCG Matrix. These initiatives are crucial for grid stability as renewable energy sources grow, with WaterCharger expected to be operational by late 2025.
This strategic investment positions TransAlta as an early adopter in a high-growth market, aiming to capture significant future market share in energy storage solutions.
TransAlta is actively developing customer-centric renewable and storage solutions, with a particular emphasis on serving large industrial clients. This strategic direction taps into a rapidly expanding market as businesses increasingly prioritize meeting their Environmental, Social, and Governance (ESG) goals and ensuring dependable, sustainable energy supplies. By customizing these offerings to meet the unique requirements of each client, TransAlta is well-positioned to capture a significant and growing market share, leveraging a distinct competitive edge.
TransAlta's strategic partnership with Nova Clean Energy, LLC, is a significant move in its US renewable development strategy. This alliance grants TransAlta exclusive options to acquire late-stage renewable energy projects across the Western United States. This access to over four gigawatts of development projects underscores a clear intent to expand its presence in key, high-growth American markets.
This collaboration is designed to fuel TransAlta's future expansion and solidify its position as a leader in the renewable energy sector. The pipeline secured through this partnership is crucial for achieving its long-term growth objectives and enhancing its market share.
TransAlta is strategically positioning itself in Alberta's burgeoning data center market, shifting towards commercializing its power solutions. This move capitalizes on the significant demand for dependable and green electricity driven by the rapid growth of the data center sector.
Alberta's projected infrastructure expansion creates a fertile ground for TransAlta's data center ambitions. The company is leveraging its established infrastructure and growing clean energy assets to meet the energy needs of this critical digital economy enabler.
TransAlta's new wind and solar facilities, like White Rock and Horizon Hill completed in 2024, are positioned as Stars. These projects, adding over 500 MW of clean energy, represent high-growth markets where TransAlta has invested significantly. The company's secured long-term power purchase agreements, such as with Amazon Energy, provide strong revenue visibility, reinforcing their Star status.
| Project Type | Capacity (MW) | Location | Key Agreements | Status |
| Wind | 300+ | Oklahoma | Amazon Energy PPA | Operational (2024) |
| Solar | 200+ | Oklahoma | Amazon Energy PPA | Operational (2024) |
| Wind/Solar Pipeline | 4,000+ | Western US | Strategic Partnership (Nova Clean Energy) | Development Stage |
 Detailed Word Document
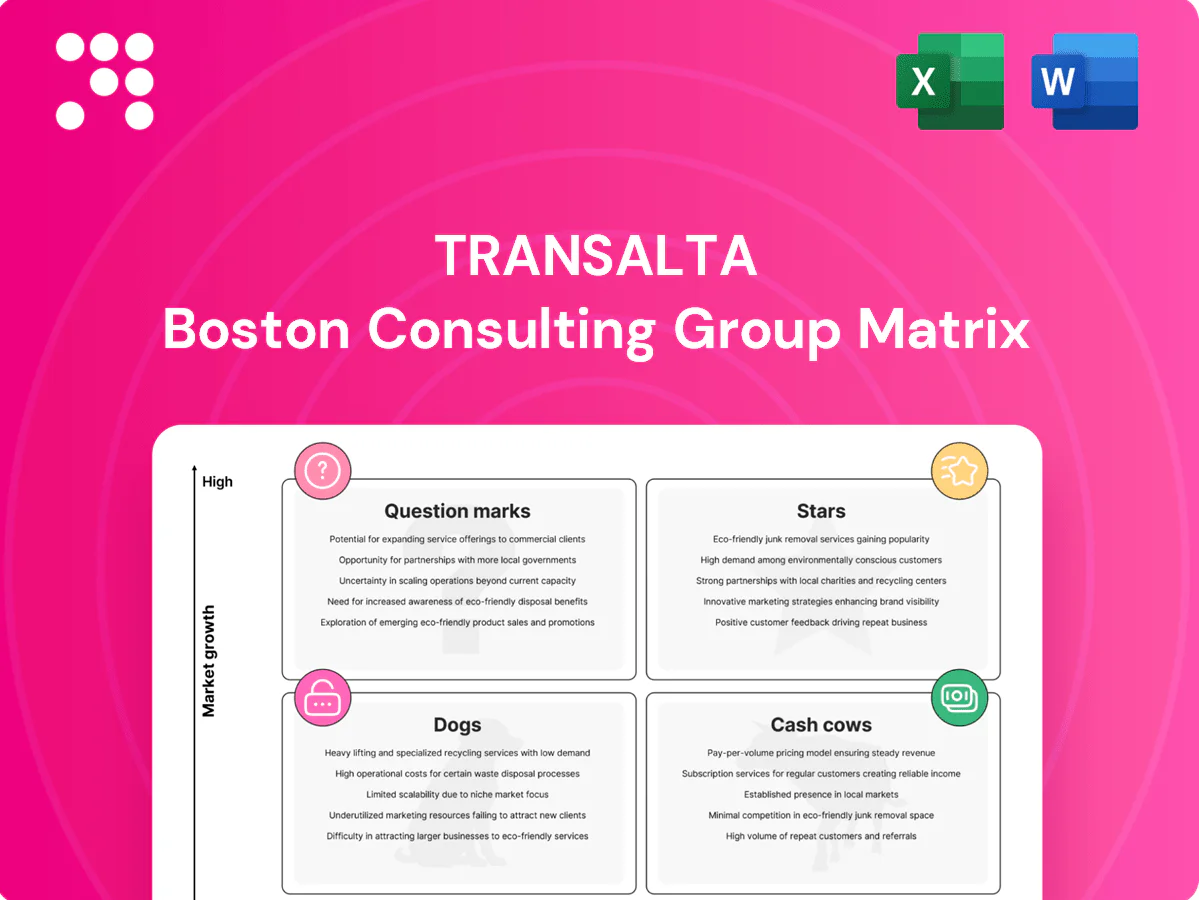
The TransAlta BCG Matrix offers a strategic overview of its business units, categorizing them as Stars, Cash Cows, Question Marks, or Dogs to guide investment decisions.

 Customizable Excel Spreadsheet
TransAlta's BCG Matrix offers a clear, visual representation of its business units, easing the pain of complex portfolio analysis.
TransAlta's established hydroelectric fleet, particularly its significant presence in Alberta where it stands as the largest producer, exemplifies a prime cash cow in its portfolio. These mature assets are characterized by their high reliability and consistent generation of low-cost power, supported by minimal operating expenses.
In 2024, TransAlta's hydroelectric facilities continue to be a bedrock of stable, predictable cash flow. For instance, their Alberta hydro assets have historically provided a substantial portion of the company's energy generation, often exceeding 1,000 MW of capacity, contributing significantly to earnings before interest, taxes, depreciation, and amortization (EBITDA).
The long operational lifespans of these hydroelectric plants, coupled with their established market positions, ensure a steady stream of revenue. These reliable cash flows are crucial for funding TransAlta's strategic investments in new growth areas, such as renewable energy projects and modernizing its existing infrastructure.
TransAlta's acquisition of Heartland Generation in December 2024, adding 1.7 GW of flexible natural gas capacity, significantly strengthens its position as a cash cow. These assets, including contracted cogeneration, are crucial for providing reliable base-load and peaking power in an essential energy market. The deal, valued at approximately $700 million plus debt, is expected to be immediately accretive to TransAlta's distributable cash flow per share.
TransAlta's mature onshore wind portfolio, boasting around 3,600 MW of renewable capacity as of 2024, represents a significant cash cow. These established wind farms operate in mature markets, benefiting from stable, long-term power purchase agreements that ensure predictable revenue streams.
The operational efficiency of these sites, coupled with the relatively low ongoing capital expenditure required for maintenance, allows them to generate consistent and high-margin cash flows. This reliable income generation solidifies their position as a core strength within TransAlta's business model.
TransAlta's Alberta portfolio operates as a significant cash cow, largely due to its sophisticated energy marketing and hedging strategies. These tactics allow the company to secure revenues that are often considerably higher than fluctuating spot market prices, providing a stable and predictable income stream.
This active management, applied across a diverse generation fleet within a competitive market, effectively mitigates risk while simultaneously boosting profitability. The result is a robust financial foundation for TransAlta, characterized by consistent returns and enhanced resilience.
Long-term contracted transmission assets, such as those operated by TransAlta, represent classic cash cows within the BCG Matrix. The commercial operation of infrastructure projects, like the Mount Keith Transmission Expansion which began in 2024, generates a stable and predictable revenue stream. These assets are typically situated in regulated markets with low growth potential, but this stability translates into highly secure and reliable cash flows for the company. This predictability makes them dependable sources of cash, bolstering TransAlta's financial health with minimal exposure to market fluctuations.
These assets are characterized by their operational longevity and the contracted nature of their revenue, offering a consistent return on investment. For instance, TransAlta's portfolio includes assets with long-term power purchase agreements that lock in revenue for years, providing a solid foundation for financial planning. The regulated environment often limits upside potential but significantly reduces downside risk, making them ideal for generating consistent cash generation.
TransAlta's established hydroelectric fleet, particularly its significant presence in Alberta where it stands as the largest producer, exemplifies a prime cash cow in its portfolio. These mature assets are characterized by their high reliability and consistent generation of low-cost power, supported by minimal operating expenses.
In 2024, TransAlta's hydroelectric facilities continue to be a bedrock of stable, predictable cash flow. For instance, their Alberta hydro assets have historically provided a substantial portion of the company's energy generation, often exceeding 1,000 MW of capacity, contributing significantly to earnings before interest, taxes, depreciation, and amortization (EBITDA).
The long operational lifespans of these hydroelectric plants, coupled with their established market positions, ensure a steady stream of revenue. These reliable cash flows are crucial for funding TransAlta's strategic investments in new growth areas, such as renewable energy projects and modernizing its existing infrastructure.
TransAlta's mature onshore wind portfolio, boasting around 3,600 MW of renewable capacity as of 2024, represents a significant cash cow. These established wind farms operate in mature markets, benefiting from stable, long-term power purchase agreements that ensure predictable revenue streams.
The operational efficiency of these sites, coupled with the relatively low ongoing capital expenditure required for maintenance, allows them to generate consistent and high-margin cash flows. This reliable income generation solidifies their position as a core strength within TransAlta's business model.
TransAlta's Alberta portfolio operates as a significant cash cow, largely due to its sophisticated energy marketing and hedging strategies. These tactics allow the company to secure revenues that are often considerably higher than fluctuating spot market prices, providing a stable and predictable income stream.
This active management, applied across a diverse generation fleet within a competitive market, effectively mitigates risk while simultaneously boosting profitability. The result is a robust financial foundation for TransAlta, characterized by consistent returns and enhanced resilience.
Long-term contracted transmission assets, such as those operated by TransAlta, represent classic cash cows within the BCG Matrix. The commercial operation of infrastructure projects, like the Mount Keith Transmission Expansion which began in 2024, generates a stable and predictable revenue stream. These assets are typically situated in regulated markets with low growth potential, but this stability translates into highly secure and reliable cash flows for the company. This predictability makes them dependable sources of cash, bolstering TransAlta's financial health with minimal exposure to market fluctuations.
These assets are characterized by their operational longevity and the contracted nature of their revenue, offering a consistent return on investment. For instance, TransAlta's portfolio includes assets with long-term power purchase agreements that lock in revenue for years, providing a solid foundation for financial planning. The regulated environment often limits upside potential but significantly reduces downside risk, making them ideal for generating consistent cash generation.
| Asset Type | Capacity (MW) | Key Characteristic | 2024 Contribution | BCG Status |
| Hydroelectric (Alberta) | >1,000 | Low operating costs, high reliability | Significant EBITDA contributor | Cash Cow |
| Onshore Wind | ~3,600 | Stable PPAs, low maintenance capex | Consistent, high-margin cash flow | Cash Cow |
| Transmission Assets | Varies | Contracted revenue, regulated markets | Stable, predictable revenue | Cash Cow |
The TransAlta BCG Matrix preview you're viewing is the exact, unwatermarked document you will receive upon purchase. This comprehensive analysis, meticulously crafted to provide strategic insights into TransAlta's business units, will be yours to download and utilize immediately. You can confidently expect the full, professionally formatted report, ready for integration into your strategic planning or presentations, without any alterations or demo content.
TransAlta's Centralia Unit 2 coal-fired plant is slated for retirement by December 31, 2025, signifying the company's complete exit from coal-fired electricity generation. This move aligns with broader environmental goals and increasing regulatory scrutiny on fossil fuels.
Operating in a market characterized by declining demand and rising compliance costs, Centralia Unit 2 is a prime example of a 'dog' asset. Its future is limited due to its impending closure and the associated expenses for decommissioning and environmental remediation, which are projected to be substantial.
Mothballed Sundance Unit 6 fits squarely into the 'dog' category within TransAlta's BCG Matrix. This unit was taken offline on April 1, 2025, a decision driven by an oversupply of power and declining prices in Alberta's energy market. Consequently, it's currently a non-revenue-generating asset, tying up capital without yielding meaningful returns.
Although TransAlta has the option to reactivate Sundance Unit 6, its current inactive state and the prevailing market conditions firmly place it as a dog. It represents a drain on resources, consuming capital and maintenance without contributing to the company's immediate financial performance or market share.
TransAlta's legacy coal assets without conversion plans are firmly in the Dogs quadrant of the BCG Matrix. These units face escalating operational expenses driven by rising carbon prices and stricter environmental regulations. For instance, in 2024, the Canadian federal carbon tax on coal-fired power generation continues to add significant cost pressure.
These assets likely possess a low market share and diminishing profitability as the energy market shifts towards cleaner alternatives. Their continued operation without a clear transition strategy represents a significant drag on TransAlta's overall clean energy transition goals, potentially impacting the company's sustainability ratings and investor appeal.
Given these challenges, TransAlta is likely evaluating options such as divestiture or decommissioning for these non-converting coal units. This strategic move would allow the company to reallocate capital and focus resources on its growing portfolio of renewable energy projects.
While TransAlta has been acquiring flexible gas capacity, some older, less efficient gas peaking plants might be considered dogs in their portfolio. These assets, particularly those not part of broader optimization plans or lacking long-term agreements, could face profitability challenges. For instance, if these plants have high operating expenses and are infrequently utilized due to market conditions, their contribution could be minimal.
Divested or fully decommissioned assets, such as TransAlta's Keephills Unit 1 and Sundance Unit 4 coal plants, along with Sundance 3, represent past 'dogs' that have been strategically removed from the company's active portfolio. These actions reflect a clear commitment to shedding underperforming or environmentally challenged assets that no longer fit the evolving clean energy landscape and market demands. For example, in 2023, TransAlta continued its transition away from coal, with plans to retire its remaining coal units by 2025, underscoring this divestment strategy.
This category highlights TransAlta's proactive approach to portfolio management, focusing on optimizing its asset base for future growth and sustainability. By decommissioning or divesting these older, less efficient assets, the company frees up capital and resources to invest in cleaner, more profitable ventures. This strategic pruning is crucial for maintaining a competitive edge and adapting to regulatory and market shifts towards decarbonization.
TransAlta's legacy coal assets, such as the Centralia Unit 2 slated for closure by December 31, 2025, and mothballed Sundance Unit 6, exemplify 'dogs' in its BCG Matrix. These units face declining demand, rising compliance costs, and are non-revenue generating, tying up capital without returns.
Older, less efficient gas peaking plants that are infrequently utilized and have high operating expenses also fall into this category. Assets without long-term agreements or integration into broader optimization plans are particularly vulnerable to profitability challenges.
TransAlta is actively managing these 'dog' assets through divestiture or decommissioning, as seen with Keephills Unit 1 and Sundance Units 3 and 4. This strategy allows for capital reallocation towards cleaner, more profitable ventures, aligning with the company's clean energy transition goals.
| Asset | Status | BCG Category | Reasoning | 2024 Impact |
|---|---|---|---|---|
| Centralia Unit 2 | Retiring Dec 31, 2025 | Dog | Declining demand, rising compliance costs, impending closure | Increased decommissioning provisions |
| Sundance Unit 6 | Mothballed Apr 1, 2025 | Dog | Oversupply, declining prices, non-revenue generating | No contribution to revenue, ongoing maintenance costs |
| Legacy Coal (Unconverted) | Various (to be retired) | Dog | High operational expenses (carbon tax), diminishing profitability | Continued cost pressure from federal carbon tax |
| Inefficient Gas Peaking Plants | Operational (variable) | Potential Dog | High maintenance, low dispatch frequency, lack of contracts | Minimal contribution to financial performance if infrequently utilized |
TransAlta's early-stage green hydrogen initiatives, such as the proposed Tent Mountain Renewable Energy Complex featuring an electrolyzer, position the company in a high-growth sector. This segment is characterized by significant technological development and substantial upfront investment, reflecting its nascent stage.
While the green hydrogen market holds considerable future potential, TransAlta's current market share within this emerging industry is minimal. This aligns with the characteristics of a 'question mark' in a BCG matrix, indicating high potential growth but also high uncertainty regarding future profitability and market dominance.
The global green hydrogen market is projected to expand significantly, with some forecasts suggesting it could reach hundreds of billions of dollars by 2030. However, the technology's cost-effectiveness and widespread adoption are still being determined, making these early ventures a strategic gamble for companies like TransAlta.
TransAlta's strategic push into new renewable markets, particularly in emerging international territories beyond its established Canadian and US footprints, positions these ventures as question marks within its portfolio. These markets, like select regions in Australia experiencing rapid renewable energy growth but also intense competition, demand substantial upfront investment to establish a foothold.
The challenge lies in building market share from a nascent position while simultaneously demonstrating a clear competitive edge and securing vital long-term power purchase agreements. For instance, while Australia's renewable energy capacity grew significantly, with solar and wind contributing over 35% of its electricity generation in 2023, entering new sub-markets requires navigating unique regulatory landscapes and local dynamics.
TransAlta's exploration into advanced energy storage beyond batteries, such as pumped hydro and compressed air energy storage (CAES), represents a strategic move into the question mark quadrant of the BCG matrix. These technologies, while offering significant long-term growth potential, currently exhibit low market penetration and necessitate considerable research and development investment, carrying inherent commercial viability risks.
For instance, pumped hydro storage, a mature technology, still presents opportunities for expansion and optimization, especially in regions with suitable geography. CAES, on the other hand, is still in its nascent stages of commercial deployment, with projects like the proposed Advancion Energy Storage Center in New York aiming to demonstrate its scalability. These ventures require substantial upfront capital, often in the hundreds of millions of dollars, and their economic feasibility is still being proven in diverse market conditions.
The repowering and redevelopment of the Centralia site, particularly the exploration of converting to natural gas or developing new renewable energy capacity, positions this initiative as a potential star in TransAlta's BCG matrix. This is due to its high-growth potential, leveraging an existing site for new energy generation.
However, these projects are currently in the early stages of planning and negotiation, meaning they have a low market share in their new energy forms. Significant capital investment is required before these ventures can realize their full potential and contribute substantially to TransAlta's portfolio.
TransAlta's forward-looking strategy, aiming to define the next generation of power solutions, indicates a keen interest in emerging clean energy technologies. This technology-agnostic approach means they are likely evaluating options beyond current mainstream renewables.
These nascent technologies, while holding significant long-term growth potential, currently represent a smaller portion of the market and carry higher investment risks. Examples include small modular reactors (SMRs), which promise enhanced safety and flexibility in nuclear power generation, and advanced geothermal systems that tap into deeper, hotter resources.
Furthermore, carbon capture utilization and storage (CCUS) integrated with existing or new gas infrastructure is another area of potential exploration. In 2024, the global CCUS market is projected to see substantial growth, with investments in new projects accelerating, driven by policy incentives and corporate decarbonization goals.
TransAlta's ventures into emerging clean energy technologies like green hydrogen and advanced energy storage are classic examples of 'question marks' in the BCG matrix. These initiatives operate in high-growth potential markets but currently possess low market share and face significant uncertainty regarding future profitability and widespread adoption. The substantial upfront investment required, coupled with evolving technological landscapes and regulatory frameworks, underscores the inherent risks associated with these early-stage endeavors.
| Initiative | Market Growth Potential | Current Market Share | Investment Required | Risk Level |
|---|---|---|---|---|
| Green Hydrogen (e.g., Tent Mountain) | Very High | Low | High | High |
| Advanced Energy Storage (Pumped Hydro, CAES) | High | Low | High | Medium to High |
| Emerging Clean Tech (SMRs, Advanced Geothermal, CCUS) | Very High | Negligible | Very High | Very High |


