
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Cover political, economic, social, technology, legal and environmental change.
Separate market signals from their business impact.
Create a structured view of opportunities and exposure.
Unlock how political, economic, social, technological, legal and environmental forces are shaping Trifork’s trajectory with our concise PESTLE overview—perfect for investors and strategists. Dive deeper into risks and opportunities with the full, fully editable analysis. Purchase now for instant, actionable intelligence.
Governments drive funding for e-government, health IT and digital justice; EU Digital Europe Programme (€7.5bn for 2021–2027) and national recovery plans channel multi-year procurement. Trifork’s public-client exposure links its pipeline to policy cycles and budgets, making revenues sensitive to electoral shifts that can reallocate spending and alter project scopes. Proactive alignment with national and EU digital strategies can secure framework agreements lasting 3–5 years.
Geopolitical supply-chain risk threatens cloud hardware, specialized talent pools and vendor dependencies—top-3 cloud providers hold roughly 65-70% of market share, concentrating exposure. Export controls since 2022 have sharply limited advanced GPU and encryption component flows to some regions, while Taiwan and South Korea supply >70% of advanced foundry capacity. Trifork must diversify suppliers and regions and run scenario planning to protect 99.9% SLA commitments.
EU programs such as Horizon Europe (budget ~95.5bn EUR 2021–27) and Digital Europe (budget ~7.5bn EUR 2021–27) catalyze demand for innovation projects and platform adoption across member states. Participation can co-finance Trifork R&D and accelerate public-sector deployments, though consortium management and compliance increase overhead and project lead times. Targeted bids unlock cross-border public-sector engagements and procurement pathways.
National mandates for data residency drive cloud architecture decisions, notably under GDPR across 27 EU states and strict regimes such as China and Russia. Trifork’s multi-cloud and sovereign-cloud patterns position it to win regulated tenders in healthcare and finance. Misalignment risks disqualification or costly rework during procurement. Clear data governance blueprints reduce political scrutiny and accelerate approvals.
States now classify healthcare, finance and public services as critical infrastructure, driving stricter national rules such as the EU NIS2 affecting about 42,000 entities and 24-hour incident reporting; higher threat levels boost demand for zero-trust, SOC and IR capabilities, creating an opportunity for Trifork to sell policy-aligned managed security services.
Governments fund e‑government via Digital Europe (€7.5bn) and Horizon Europe (€95.5bn), tying Trifork revenues to policy cycles and 3–5yr framework agreements. GDPR/data‑residency and NIS2 (~42,000 entities) boost sovereign‑cloud and compliance demand. Cloud market concentration (65–70%) and export controls raise supplier/geopolitical risk.
| Metric | Value |
|---|---|
| Digital Europe | €7.5bn (2021–27) |
| Horizon Europe | €95.5bn (2021–27) |
| Cloud concentration | 65–70% |
| NIS2 scope | ~42,000 entities |
 Detailed Word Document
Explores how external macro-environmental factors uniquely affect Trifork across six dimensions—Political, Economic, Social, Technological, Environmental, and Legal—each backed by current data and trends to highlight risks and opportunities. Designed for executives and investors, the analysis offers detailed sub-points, forward-looking insights, and clean formatting ready for reports, decks, or scenario planning.

 Customizable Excel Spreadsheet
A concise, visually segmented PESTLE summary that can be dropped into presentations, edited with region- or business-specific notes, and quickly shared across teams to streamline external risk assessment and market-position discussions.
Macro slowdowns often push back discretionary transformation programs, even as Gartner estimated global IT spending at about $4.7 trillion in 2024 and forecast growth into 2025, keeping resilience and productivity projects prioritized. Trifork’s blend of consulting, development and operations smooths revenue volatility by shifting clients from one-off projects to continuous delivery. Multi-year managed services drive recurring cash flow and reduced churn. Flexible pricing and outcome-based models improve win rates when budgets tighten.
Wage inflation for engineers (around 6–8% YoY in 2024–25) is pressuring Trifork margins, forcing tighter project pricing and utilization targets. Nearshore hubs and delivery pyramids can lower labour cost-to-value by roughly 25–40% versus onshore delivery, preserving competitiveness. Rate card updates must reflect these market moves—insufficient increases erode margins, excessive ones hit demand. Investment in automation and reusable accelerators (raising utilization 5–10%) preserves gross margin by a few percentage points.
A global Trifork footprint exposes revenue and costs to FX swings across EUR, USD and SEK markets. The Danish krone's peg to the euro narrows EUR/DKK volatility, while local delivery and multi‑currency contracts provide natural hedges. Formal hedging policies stabilise cash flows for capex and M&A. Transparent FX reporting supports investor confidence on Nasdaq Copenhagen.
Clients now demand measurable ROI from cloud modernization and AI; FinOps Foundation (2024) reports roughly 30% average wasted cloud spend, making clear business cases and KPI baselines critical to approvals. Outcome-based, phased engagements and case-backed playbooks reduce adoption risk and, per vendor reports, can shorten sales cycles materially.
Industry consolidation reshapes Trifork competitive positioning and capability breadth, with European software deal activity remaining robust into 2024. Selective acquisitions can close gaps in AI, cybersecurity and regulated sectors; hyperscaler market shares (2024 est: AWS ~33%, Azure ~23%, GCP ~11%) and ISV alliances materially drive deal flow. Rigorous integration discipline is critical to preserve culture and delivery quality.
Macro IT spend ~$4.7T (2024) keeps resilience programs prioritized; wage inflation 6–8% (2024–25) pressures margins while nearshore can cut labour cost-to-value ~25–40%. FinOps finds ~30% cloud waste (2024) making ROI-driven, outcome-based deals essential; hyperscaler share (2024 est) AWS 33% / Azure 23% / GCP 11% shapes partnerships and pipeline.
| Metric | Value |
|---|---|
| Global IT spend (2024) | $4.7T |
| Engineer wage inflation (2024–25) | 6–8% |
| Cloud waste (FinOps 2024) | ~30% |
| Hyperscaler share (2024) | AWS33%/Azure23%/GCP11% |
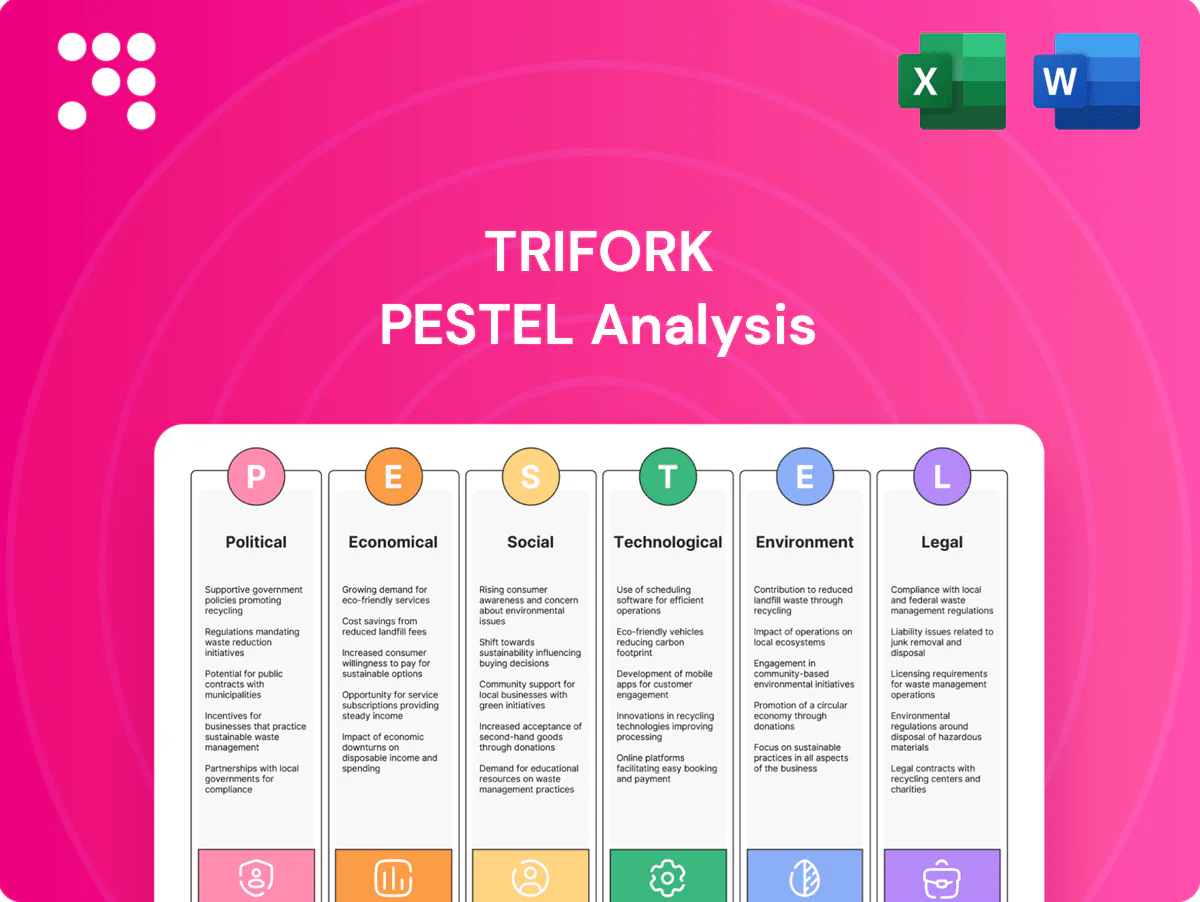
The Trifork PESTLE Analysis preview shown here is the exact document you’ll receive after purchase—fully formatted and professionally structured. It contains the complete political, economic, social, technological, legal, and environmental assessments as displayed. No placeholders or teasers—this is the final, ready-to-use file available for immediate download.
Users now expect privacy, fairness and explainability in software; GDPR enforces privacy-by-design with fines up to 4% of global turnover and the EU AI Act (finalized 2024) mandates risk-based AI governance. Trifork must embed responsible AI and privacy-by-design to win procurement in regulated sectors. Transparent governance increases adoption in healthcare and finance, and ethical stances differentiate in crowded bids.
Engineers increasingly demand flexible work, purposeful projects and continuous learning; Stack Overflow 2024 reports about 54% of developers prefer hybrid arrangements, boosting retention when firms offer strong learning cultures and modern toolchains. Hybrid models let Trifork tap talent beyond HQs, lowering local hiring costs and accelerating time-to-fill. Employer branding now directly affects bid credibility with clients that value continuity and low turnover.
Public and healthcare users require accessible, inclusive digital services—about 15% of the global population lives with some form of disability (WHO). Human-centered design reduces friction and increases engagement by focusing on real user tasks and barriers. Co-creation with clinicians and citizens improves clinical adoption and outcomes through contextual validation. Measurable UX gains support renewal and expansion by demonstrating ROI to buyers and funders.
Aging populations (WHO forecasts 2.1 billion aged 60+ by 2050) are increasing care demand and clinician shortages (WHO estimated ~10m health worker shortfall by 2030), driving need for digital triage, remote care and interoperable data. Trifork can tailor platforms to capacity constraints; solutions that cut clinician burden scale fast, but proven security and uptime are mandatory.
Fintech must balance rapid innovation with clarity and access so Trifork products reach diverse users; 3.6 billion used digital payments in 2024 while about 1.4 billion remained unbanked (World Bank 2021), highlighting gaps. Simple, transparent interfaces build trust; secure onboarding and fraud prevention protect vulnerable users. Analytics personalize services but must respect privacy and consent.
Users demand privacy, explainability and accessible design; GDPR fines up to 4% turnover and EU AI Act (2024) force privacy-by-design and responsible AI. 54% of developers prefer hybrid work (Stack Overflow 2024), enabling distributed hiring but raising employer-branding stakes. Aging (2.1B aged 60+ by 2050) and 1.4B unbanked drive demand for inclusive, secure digital services.
| Metric | Value |
|---|---|
| GDPR fine | Up to 4% global turnover |
| Hybrid preference | 54% (Stack Overflow 2024) |
| Aging | 2.1B aged 60+ by 2050 (WHO) |
| Unbanked | 1.4B (World Bank 2021) |
Advances in LLMs now commonly exceed 100 billion parameters, while MLOps and vector databases enable sub-second retrieval and faster iteration, reshaping Trifork product roadmaps. Trifork can embed AI copilots and predictive models across sectors to boost customer outcomes and revenues. Robust guardrails, monitoring and third-party evaluation are essential for reliability. High-quality data and lineage remain the foundation for measurable real-world impact.
Kubernetes, serverless and edge patterns deliver scalability and sub-50 ms latency for real-time workloads, enabling Trifork to target healthcare and public-safety use cases. CNCF survey indicators show widespread Kubernetes adoption (high single‑digit to low‑double‑digit percentage growth through 2024). Multi‑cloud reference architectures attract regulated clients, while observability and FinOps keep cloud costs predictable.
Ransomware and supply-chain attacks are driving higher controls and budgets, with IBM 2024 reporting an average breach cost of $4.45M and global security spend near $188B in 2024. Zero-trust, IAM and secure SDLC are now table stakes. Trifork’s managed detection and response extends post-go-live value, while continuous security testing measurably lowers residual risk.
Interoperability is core for Trifork: PSD2 (2018) and US ONC/CMS API rules (2020) anchor open banking and HL7 FHIR as mandatory standards for finance, healthcare and government APIs, making standards mastery a regulatory must by 2025.
DevEx and platform engineering—via internal developer platforms—streamline delivery, security and compliance, enabling Trifork teams to adopt golden paths that raise productivity and reduce variance; DORA-style studies show elite teams deploy orders of magnitude more frequently and recover far faster. Reusable templates and scaffolding cut lead time and context-switching; improved DevEx correlates with higher employee satisfaction and better client outcomes.
Advances in LLMs (>100B params), MLOps and vector DBs enable AI copilots and predictive services; high‑quality data, lineage and guardrails are critical. Kubernetes/serverless/edge deliver sub‑50 ms targets for healthcare/public safety; CNCF indicators show ~8–12% Kubernetes adoption growth through 2024. Rising cyber costs (avg breach $4.45M; security spend ~$188B in 2024) make zero‑trust, IAM and secure SDLC mandatory.
| Metric | 2024 stat |
|---|---|
| LLM scale | >100B params |
| Avg breach cost | $4.45M |
| Global security spend | $188B |
| Kubernetes growth | ~8–12% (2024) |
Strict consent, data minimization and mandatory DPIAs for high‑risk processing force Trifork to embed privacy-by-design into product architecture. Trifork must document lawful bases and maintain robust data subject request workflows meeting GDPR’s one‑month response limit. Privacy engineering lowers exposure in analytics and AI; IBM’s 2024 Cost of a Data Breach averaged $4.45M. Non‑compliance risks fines up to 4% of global turnover or €20M.
Sector regulations—HIPAA-like rules in healthcare (covering ~330 million US patients), PSD2/AML-KYC in finance (EU/EEA ~450 million consumers) and public procurement (≈12% of OECD GDP) impose strict controls. Compliance-by-design shortens approval cycles and eases audits. Immutable audit trails and traceability are critical. Domain expertise materially increases win probability in regulated tenders.
Emerging AI acts, notably the EU AI Act, impose risk classification, transparency and human oversight requirements and carry fines up to €35 million or 7% of global turnover for breaches.
Model documentation, impact assessments and continuous monitoring will become contractual obligations for vendors and clients.
Trifork can package compliance toolkits and implementation services to accelerate client adoption; early alignment reduces costly retrofits and go‑to‑market delays.
Balancing proprietary platforms with open-source components requires strict licensing control; Synopsys 2024 found 99% of codebases include OSS and 84% contain known vulnerabilities. SBOMs and automated license scans, driven by NTIA/CISA guidance for federal suppliers by 2025, reduce legal exposure. Clear IP ownership in co-creation preserves revenue, and standardized contracts can cut negotiation time up to 40%.
Contracting and liability at Trifork hinge on complex SLAs, cybersecurity clauses and indemnities that shape the firm’s risk profile; caps, exclusions and governance forums (eg. steering committees) are used to reduce disputes and allocate exposure. Insurance complements technical controls — the IBM 2024 Cost of a Data Breach average was $4.45M, underscoring transfer value. Post-incident playbooks enable rapid, compliant response.
GDPR forces privacy-by-design with fines up to 4% of global turnover or €20M; DPIAs and 1-month DSARs are mandatory. EU AI Act adds risk-classification and fines up to €35M or 7% turnover; model documentation and monitoring become contractual. OSS/license hygiene (Synopsys 2024: 99% codebases OSS, 84% contain known vulns) and SBOMs reduce legal exposure; cyber insurance offsets ~IBM 2024 breach cost $4.45M.
| Regulation | Max fine | Key stat |
|---|---|---|
| GDPR | 4% turnover / €20M | DPIA, 1‑month DSAR |
| EU AI Act | €35M / 7% | Risk classes, transparency |
| OSS risk | — | 99% OSS, 84% vulns (Synopsys 2024) |
Clients increasingly demand carbon-aware architectures and efficient workloads; the 2024 Flexera State of the Cloud report found 82% of enterprises prioritize cloud cost and optimization, driving FinOps plus sustainability metrics to guide platform choice. Trifork can benchmark and optimize emissions per transaction and show measurable reductions, and partnerships with low-carbon regions (Europe, Nordics) strengthen proposals and procurement cases.
Regulatory disclosure rules like EU CSRD (bringing ~50,000 firms under scope from 2024) force enterprises to track IT-related emissions; Scope 2/3 commonly represent over 70% of IT carbon footprints, boosting demand for solutions that capture that data. Automated reporting can cut manual reporting time up to 50%, and alignment with GHG Protocol and peer‑reviewed methodologies increases credibility of outcomes.
Data center sustainability for Trifork hinges on energy sourcing, PUE and cooling footprint: global data centres use ~1% of electricity with median PUE ~1.59 (Uptime Institute 2023), and cooling drives a large share of emissions. Selecting hyperscalers with 100% renewable targets (Google matched 100% in 2023; Microsoft/AWS targeting 2025–2030) helps decarbonize, while edge siting alters local impacts and vendor sustainability transparency supports client compliance.
Procurement policies prioritise repairable, recyclable hardware to curb the global e-waste surge (about 60 million tonnes in 2022). Trifork can advise clients on asset lifecycle optimisation and e-waste reduction, deploying device management and thin clients that cut endpoint energy use and related emissions by up to 70%. Partnerships with certified recyclers enable recovery of critical materials (>90% recovery by professional processors) and close the loop.
Climate-driven extreme weather threatens data center uptime and field operations, with Swiss Re reporting ~140 billion USD insured losses from natural catastrophes in 2023, underlining rising disruption risk; multi-region architectures and robust DR plans reduce outage impact and recovery times.
Hardware supply chains remain vulnerable to delays, pushing firms to stock strategic spares; audited business continuity readiness is thus a measurable competitive differentiator.
Clients demand carbon-aware cloud; 82% prioritize cloud cost/optimization (Flexera 2024) and CSRD brings ~50,000 firms under scope from 2024, boosting IT emissions tracking. Data centres use ~1% global electricity with median PUE 1.59 (Uptime 2023); hyperscalers aim 100% renewables. E‑waste ~60 Mt (2022); certified recycling recovers >90% materials.
| Metric | Value | Source |
|---|---|---|
| Cloud priority | 82% | Flexera 2024 |
| Firms CSRD | ~50,000 | EU 2024 |
| PUE | 1.59 | Uptime 2023 |
| E‑waste | 60 Mt | UN 2022 |


