
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
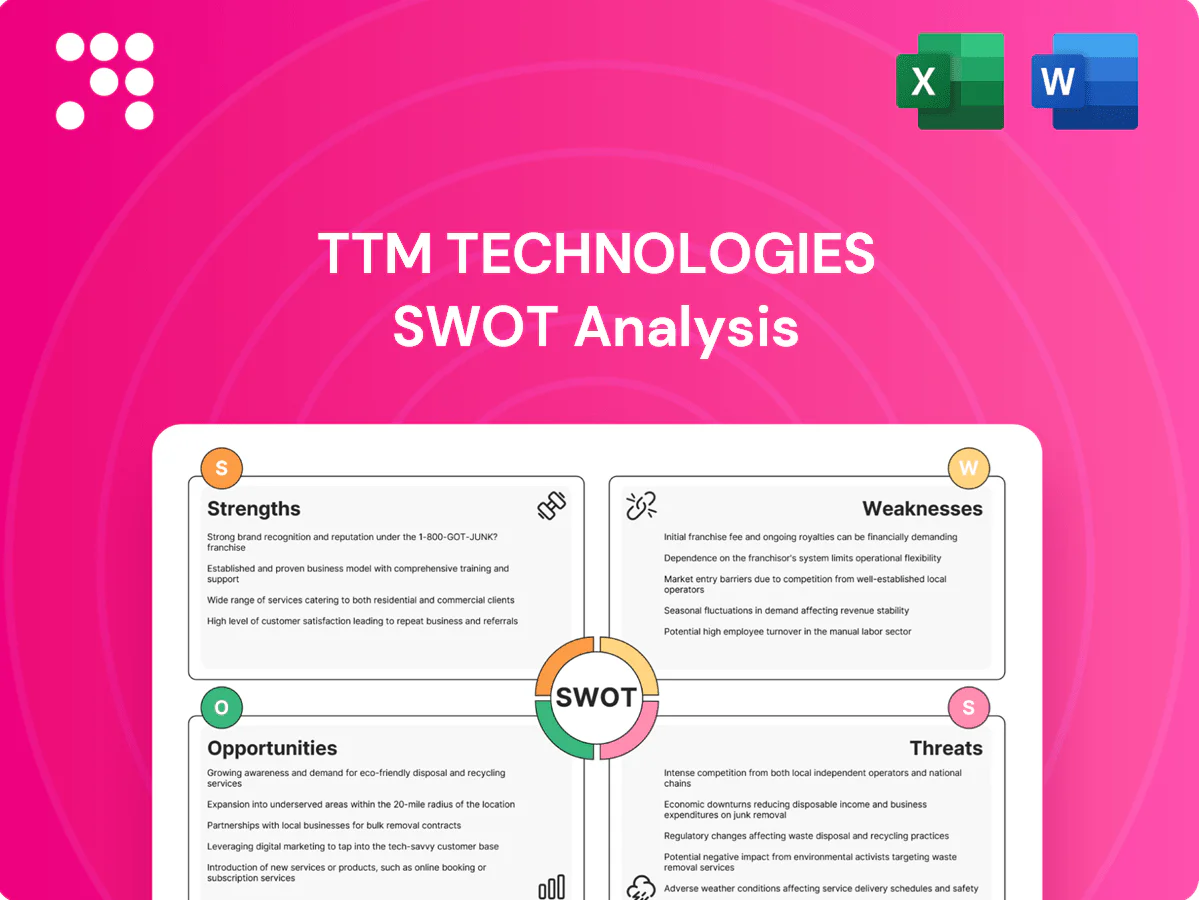
TTM Technologies’ SWOT highlights strong manufacturing scale and diversified OEM relationships, countered by supply-chain sensitivity and margin pressure. Growth opportunities include 5G, automotive electrification and advanced packaging, while competition and component shortages pose risks. Purchase the full SWOT for a detailed, editable Word+Excel report with strategic recommendations to support investment or planning.
Deep expertise in high-density interconnect and RF/microwave lets TTM meet stringent performance, size and signal-integrity needs for aerospace, defense and 5G customers; TTM reported FY2024 net sales of $1.9 billion. These advanced capabilities command premium pricing and drive high customer stickiness, supporting stronger margins. They create significant barriers to entry versus commodity PCB producers, positioning TTM for complex, mission-critical applications.
TTM serves aerospace and defense, data center computing, automotive, medical, industrial and instrumentation, spreading demand across multiple cycles. This diversification helps balance sector volatility; TTM reported $2.23 billion in FY2024 revenue, reducing single-market concentration. It broadens the innovation pipeline and revenue opportunities, while cross-sector learnings enhance solution quality and speed to market.
TTM’s integrated design-to-production model delivers design support, prototyping, NPI and scaled production, leveraging full-stack PCB and RF assembly capabilities to shorten customer time-to-market and lower program risk. TTM reported fiscal 2024 revenue of $2.13 billion, reflecting strength in bundled engineering and manufacturing services that expand wallet share and raise switching costs. This end-to-end approach supports a shift toward higher-margin, value-add engagements and deeper customer partnerships.
TTM's extensive certifications—ISO 9001, AS9100, ITAR registration and DFARS compliance—plus documented reliability testing and defense-grade traceability underpin customer trust in regulated aerospace and defense supply chains. These embedded capabilities enable participation in long-cycle, high-value programs and differentiate TTM from lower-tier PCB vendors by supporting rigorous qualification and source-inspection requirements.
Deep expertise in high-density interconnect and RF/microwave drives premium pricing and customer stickiness; FY2024 net sales $1.9B. Diversified end markets and integrated design-to-production shorten time-to-market and raise switching costs. Global footprint (25 sites, 10 countries) plus AS9100/ISO9001/ITAR/DFARS enable supply assurance for defense and aerospace.
| Metric | Value |
|---|---|
| FY2024 net sales | $1.9B |
| Manufacturing sites | 25 |
| Countries | 10 |
| Key certifications | AS9100, ISO9001, ITAR, DFARS |
 Detailed Word Document
Delivers a strategic overview of TTM Technologies’s internal and external business factors, outlining strengths, weaknesses, opportunities, and threats to assess competitive position and guide strategic decisions.

 Customizable Excel Spreadsheet
Provides a concise, TTM Technologies–focused SWOT matrix for rapid strategy alignment and clear stakeholder briefing. Ideal for executives and teams needing a quick, visual snapshot to relieve decision-making bottlenecks.
Demand in computing, industrial and automotive is cyclical and TTM’s exposure leaves utilization swings that impacted its operating leverage when industry volumes fell ~15% in late 2023; TTM reported roughly $2.0 billion in net sales in FY2024, amplifying margin pressure during downturns. Volatility compresses pricing and gross margins in slower quarters, while limited forecast visibility for quick-turn and project work raises late-stage order cancellations. Managing labor and inventory around these swings increases execution risk and can drive short-term cash flow strain.
Advanced PCB and RF manufacturing requires continual capital expenditure for new equipment and process upgrades, driving sustained cash outflows. Small yield fluctuations on complex multi-layer and RF builds can materially compress gross margins. High depreciation and maintenance costs increase fixed-cost burden in downturns. Return on invested capital can lag significantly when specialized capacity is underutilized.
Large defense and data center programs can represent a meaningful share of TTM Technologies’ revenue (TTM reported roughly $1.8B in 2024), so delays, cancellations or design shifts can materially disrupt volumes and margins. Ramp profiles are often uneven, stressing production planning and cash flow when capital and inventory are committed early. Negotiating leverage frequently favors key customers, pressuring pricing and terms.
Material and supply-chain dependencies expose TTM to concentration risk: specialty laminates, copper, chemicals and RF substrates are critical inputs whose shortages or price spikes have historically compressed margins and extended lead times.
Qualifying alternative materials is time-consuming and costly, often requiring new process validation and customer requalification, slowing response to disruptions.
Geopolitical events and export controls complicate cross-border sourcing and can abruptly restrict access to key suppliers.
Standard boards face intense price competition from high-volume Asian producers that control a majority of global capacity, pushing commodity PCB prices down and diluting mix as customers shift to lower-complexity work. TTM must sustain a complex, high-value mix and keep sales from engaging in margin-eroding commodity contracts.
TTM’s cyclical end-markets and ~15% 2023 volume drop strained operating leverage despite roughly $2.0B FY2024 sales; reliance on large programs (~$1.8B exposure in 2024) and specialized inputs (laminates, RF substrates) raises margin and execution risk, while capex and qualification costs weigh ROIC and cash flow.
| Metric | 2024 | Impact |
|---|---|---|
| Net sales | $2.0B | Margin pressure |
| Large programs | $1.8B | Concentration risk |
This is an actual excerpt from the TTM Technologies SWOT Analysis you'll receive upon purchase—no surprises, just professional quality and structured insights. The preview shown is pulled directly from the complete, editable report. Purchase unlocks the full, detailed document for download. Use it as-is or adapt for presentations and strategy work.
AI accelerators and advanced servers demand high-layer-count HDI, low-loss laminates and superior signal integrity, aligning with TTM’s capabilities as AI data center spend topped >$200B globally in 2024. Thermal and power-delivery challenges favor established partners able to deliver robust PCBs; NVIDIA reported $26B in data center revenue in FY2024, underscoring sustained multi-year capex cycles that can boost content per system through co-design.
Electrification and autonomy are boosting electronic content per vehicle as the global automotive electronics market topped $300 billion in 2024, expanding demand for HDI and RF boards critical to safety and connectivity. High-reliability HDI/RF production aligns with stringent automotive qualifications and supply-chain barriers. Vehicle platform lifecycles of 7–10 years and recurring volumes mean early design wins can secure locked-in, multi-year revenue streams for TTM.
Radar, EW, secure comms and space systems require high-frequency, high-reliability RF/microwave solutions, aligning with rising defense procurement (global military spending topped about 2.2 trillion USD in 2023 while US defense outlays were roughly 858 billion USD in 2024). Prioritization of advanced sensing and networked capabilities drives demand for specialty PCBs and RF modules. Long qualification cycles create durable, multi-year revenue streams. ITAR-compliant capacity acts as a strong competitive moat.
2.5D/3D integration and substrate-like PCBs increasingly blur lines between PCB and semiconductor packaging, enabling TTM to move up the stack by offering finer trace/line widths and advanced dielectric/laminate materials to capture higher-value substrate content in next-gen modules.
Customers increasingly demand geographically diverse, secure supply for critical electronics; North American and allied capacity is being prioritized across defense, aerospace, 5G and EV supply chains. The US CHIPS and Science Act allocates about 52 billion dollars for domestic semiconductor incentives, and allied subsidies are rising, creating opportunities to shift share from offshore commodity suppliers to qualified players such as TTM.
AI/data center capex >$200B (2024) and NVIDIA DC rev $26B (FY24) boost demand for high-layer HDI and low-loss laminates. Automotive electronics >$300B (2024) expands HDI/RF content with multi-year platform revenue. CHIPS Act ~$52B and allied subsidies favor reshoring to qualified suppliers like TTM.
| Opportunity | 2024/25 data | Impact |
|---|---|---|
| AI/DC | >$200B; NVIDIA $26B | Higher content per system |
| Automotive | >$300B | Long-term design wins |
| Reshoring | CHIPS ~$52B | Domestic share gain |
Asia-based PCB giants, which account for over 80% of global production, leverage scale, lower cost structures and rapid capacity additions to undercut rivals; the global PCB market is estimated near $60B in 2023 and headed toward ~$68B by 2025. Price competition is squeezing margins, notably in mid-complexity work, while competitors are increasing HDI and advanced-materials investment. TTM must sustain technology and service differentiation to defend margin and share.
Export controls, tariffs, and sanctions can disrupt TTM's supply chains and customer access, contributing to volatility amid slow trade (world merchandise trade volume grew just 0.5% in 2023, WTO). Defense-related compliance—relevant given the US $858 billion FY2024 defense budget—increases cost and complexity for defense-qualified PCB suppliers. Cross-border flows face delays or rerouting and political shifts can abruptly alter market access.
Advanced packaging and substrate shifts can reduce layer counts or move value off traditional PCBs, pressuring TTM’s $1.86 billion 2024 revenue base to adapt. Silicon photonics and co‑packaged optics rearchitect boards, altering demand mix and supplier capture. Miniaturization concentrates spend with semiconductor ecosystem vendors, so TTM must invest in new capabilities to capture the migrating value pool.
Volatility in copper, resins and specialty laminates drove COGS pressure for TTM in 2024, with LME copper averaging about $9,400/ton in 2024 and resin spot premiums remaining elevated, compressing gross margins as pass-through to customers lagged.
Defects or security breaches in aerospace and defense programs can cause catastrophic safety, program delays and contract termination; IBM Security 2024 reports the global average data‑breach cost was $4.45M and manufacturing averaged $4.74M, underscoring high remediation expenses and reputational damage for TTM.
Asia PCB scale/price pressure (global market ~$60B 2023 → ~$68B 2025) and advanced packaging shifts threaten TTM’s $1.86B 2024 revenue; export controls and FY2024 $858B US defense rules raise compliance costs; commodity volatility (LME copper ~ $9,400/ton 2024) and cyber/quality breaches (avg $4.45M breach cost, IBM 2024) compress margins and risk contracts.
| Threat | Key Data |
|---|---|
| Market/price | $60B→$68B (2023–25) |
| Revenue | $1.86B (2024) |
| Commodities | Copper ~$9,400/ton (2024) |
| Security | $4.45M avg breach (2024) |


