
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Cover political, economic, social, technology, legal and environmental change.
Separate market signals from their business impact.
Create a structured view of opportunities and exposure.
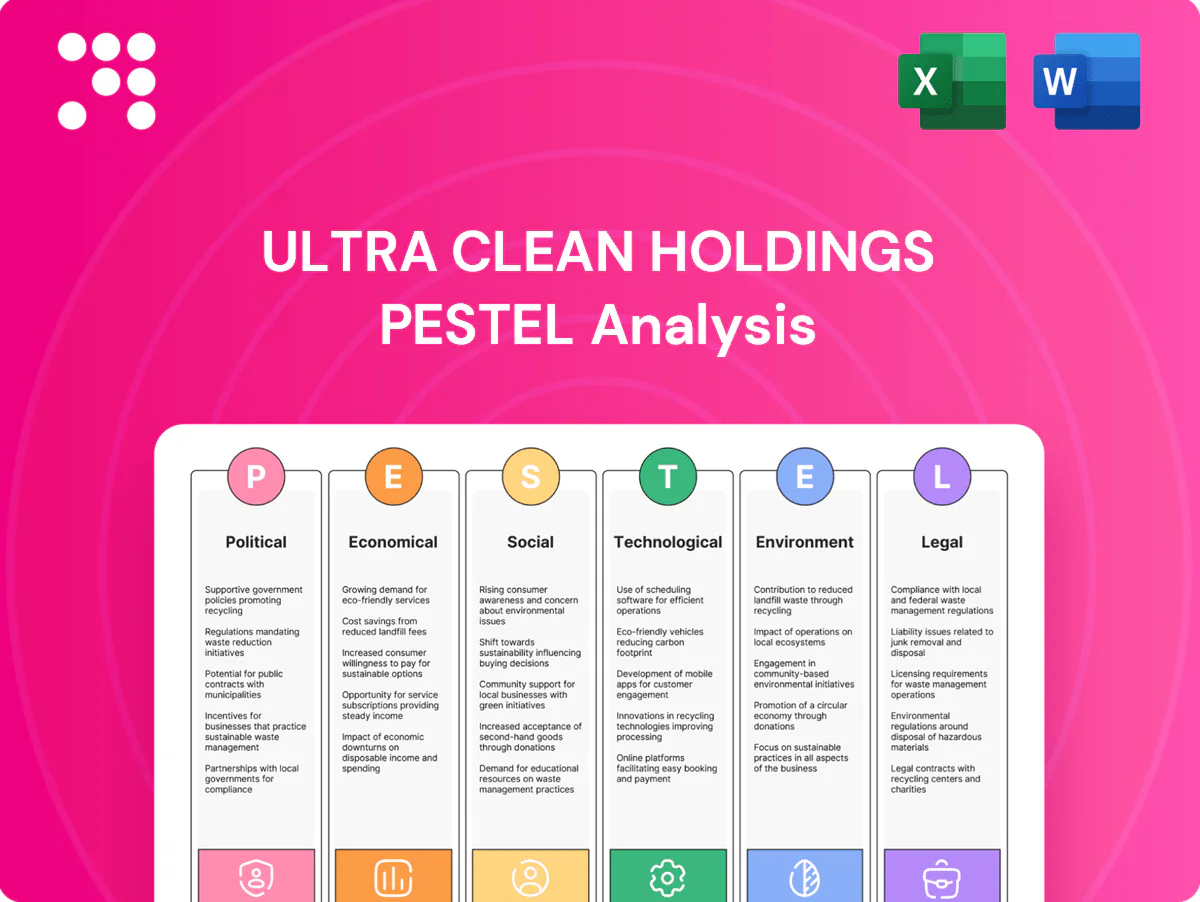
Explore how regulatory shifts, supply-chain dynamics, and rapid semiconductor cleaning innovations are shaping Ultra Clean Holdings' strategic outlook in our concise PESTLE snapshot. Ideal for investors and strategists, this analysis highlights key external risks and growth levers. Purchase the full PESTLE to access detailed, actionable insights and ready-to-use charts for decision-making.
Tightening US export controls on advanced chip tools have disrupted UCT’s semicap customers by delaying orders, forcing reroutes, or requiring subsystem redesigns; China accounted for about 30% of global semiconductor equipment spending in 2024 (SEMI), magnifying impact. UCT must manage licensing, end-use screening, and shifting demand across regions. Policy shifts have produced material quarterly swings in backlog and product mix.
CHIPS Act funding of $52.7 billion in the US and the EU Chips Act targeting roughly €43 billion are accelerating global fab construction, with Japan and South Korea launching multi-billion support programs; this boosts demand for gas/chemical delivery and vacuum subsystems. Funds are disbursed unevenly, creating timing and ramp risk for suppliers. Localization mandates often require local content or partners, complicating supply chains and contract timing.
Tariffs on metals (US Section 232: 25% steel, 10% aluminum) and Section 301 duties of up to 25% on many China-origin electronics raise Ultra Clean's input costs and sourcing complexity. China+1 reshoring drives higher freight, inventory and compliance overhead as suppliers diversify. Fragmentation increases documentation and customs risk, adding handling and inspection points. Pricing and lead times must be adjusted to absorb these frictions.
Policy focus on hazardous chemicals and workplace safety is intensifying; the CHIPS and Science Act mobilized roughly 52 billion USD for domestic fabs, bringing strict EHS, reporting and community commitments. Ultra Clean Holdings cleaning/coating operations face routine inspections and permit reviews, and political pressure can force tighter emissions or chemical thresholds on short notice. Regulators increased enforcement actions across manufacturing in 2023–24.
US export controls and licensing disruptions hit semicap demand; China was ~30% of global equipment spend in 2024 (SEMI), amplifying exposure. CHIPS Act USD 52.7B and EU ~€43B boost fab builds but create local-content/timing risk. Tariffs (US 25% steel, 10% Al; Section 301 up to 25%) and geopolitical chokepoints raise input, logistics and insurance costs; TSMC ~54% foundry revenue share in 2024.
| Factor | Metric | 2024–25 Impact |
|---|---|---|
| CHIPS funding | USD 52.7B (US), €43B (EU) | Higher capex demand, uneven disbursement |
| China market | ~30% equip spend | Concentrated demand risk |
| Tariffs | 25% steel, 10% Al, up to 25% Section 301 | Higher input costs |
| Geopolitics | TSMC 54% foundry rev | Supply-security premiums up |
 Detailed Word Document
Explores how macro-environmental forces—Political, Economic, Social, Technological, Environmental, and Legal—specifically impact Ultra Clean Holdings, combining data-backed trends and regional industry dynamics to identify risks and growth opportunities for executives and investors; includes forward-looking insights to support scenario planning and strategic decision-making.

 Customizable Excel Spreadsheet
A concise, PESTLE‑segmented summary tailored to Ultra Clean Holdings for quick sharing in meetings or presentations, enabling rapid alignment on external risks and strategic implications.
Ultra Clean’s revenue closely tracks wafer fab equipment cycles; fiscal 2024 revenue was about $1.42B, reflecting semiconductor capex swings tied to memory and logic ramps. AI-driven compute and advanced packaging lifted demand in 2024 but did not eliminate volatility, with industry tool bookings swinging roughly 30% year-over-year. Ultra Clean’s backlog is concentrated—top 3 OEMs account for about 70%—magnifying swings, so flexible cost structure and strict inventory discipline remain essential.
With the US federal funds rate at about 5.25–5.50% in 2024–25, higher rates raise borrowing costs for Ultra Clean Holdings and its fab-building customers, increasing financing expense and risk of delayed projects. Elevated rates can push customers to defer capex or opt for cheaper tool mixes; a future rate cut could unlock previously deferred spend. Treasury strategy and hedging choices materially affect EPS sensitivity to rate moves.
USD strength (trade-weighted index up roughly 7% YTD mid-2025) reduces translated revenue and limits pricing power for Ultra Clean’s largely Asia-sourced sales, forcing tighter reported margins. Inflation in precision machining, specialty gases and skilled labor—running in the mid-single to low-double digits—compresses gross margins. Surcharges and index-linked contracts help recover costs but typically lag by 3–6 months. Active FX hedging and increased regional sourcing have materially reduced volatility.
Large OEMs and IDMs drive a majority of Ultra Clean orders, with platform-level win/loss decisions producing multi-year demand swings; qualification cycles typically span 18–36 months, creating sticky revenue but concentrated negotiating power for major customers. Diversification into display, medical and energy helps smooth exposure and reduce reliance on any single OEM or IDM.
Consolidation in subsystems and services boosts purchasing power and facility footprint, enabling Ultra Clean Holdings to pursue tuck-in deals for niche coatings, analytics, or regional fab services to expand gross margins and geographic reach.
Ultra Clean’s fiscal 2024 revenue was $1.42B and remains cyclical with tool bookings swinging ~30% YoY; top‑3 OEMs drive ~70% of backlog. Higher US rates (5.25–5.50% in 2024–25) and USD strength (~+7% YTD mid‑2025) raise financing and margin pressure; inflation in inputs runs mid‑single to low‑double digits.
| Metric | Value |
|---|---|
| Revenue (FY2024) | $1.42B |
| Top‑3 backlog | ~70% |
| Tool bookings swing | ~30% YoY |
| Fed funds | 5.25–5.50% |
| USD TWI | +7% YTD (mid‑2025) |
The Ultra Clean Holdings PESTLE Analysis shown here is the exact document you’ll receive after purchase—fully formatted and ready to use. The preview is the real, finished file with complete content and professional structure. No placeholders or teasers; you’ll download this same document immediately after buying.
Engineers with gas-handling, vacuum and contamination-science expertise are scarce, creating hiring and retention pressure for Ultra Clean as chipmakers and tool OEMs compete for the same talent; the US CHIPS and Science Act allocates roughly 52 billion USD to boost domestic semiconductor capacity and labor demand. Apprenticeships and university pipelines partially mitigate shortages, while remote collaboration enables global design centers to tap dispersed specialists.
Handling hazardous gases, acids and high‑vacuum systems forces Ultra Clean to maintain a rigorous EHS culture to prevent incidents and protect uptime. Robust training, near‑miss reporting and strict PPE compliance are core controls that suppliers and OEMs require during qualification. Customers audit safety rigor and culture influences employer brand and can materially affect insurance premiums and supplier selection.
Community expectations around cleaning and coating operations challenge Ultra Clean Holdings (NASDAQ: UCTT), especially at sites in California and Texas where emissions, odors and truck traffic draw local scrutiny. Transparent environmental reporting and proactive engagement have been shown to reduce permit opposition and litigation risk. Community benefits agreements can streamline permitting, while poor relations risk costly delays and enforcement fines.
Ultra Clean Holdings' ultra-high purity performance is a core reputational asset for fabs and OEMs in semiconductors and advanced packaging; consistent particle and metallic contamination metrics underpin repeat business and long-term contracts. Holding ISO 9001 and ISO 14001 certifications and providing lot-level data transparency strengthens customer trust. Contamination failures can trigger line-down events that industry estimates place as high as $1M per hour, risking customer exits and warranty costs.
Global customers increasingly require DEI progress and supplier scorecards, and suppliers that demonstrate measurable DEI gains gain procurement advantage; McKinsey found companies in the top quartile for ethnic and cultural diversity are 36% more likely to outperform on profitability. Inclusive hiring widens the skilled talent pool, ERGs and improved leadership representation boost retention, and over 90% of large US corporates now publish DEI/ESG data to meet customer procurement rules.
Talent scarcity in gas, vacuum and contamination skills raises hiring costs as the US CHIPS Act injects ~52 billion USD boosting demand. EHS culture and community relations drive supplier selection and permit risk; line-downs can cost ~1M USD/hour. DEI and ESG scorecards influence procurement; top quartile diverse firms deliver +36% profitability and >90% large corporates report ESG.
| Metric | Value |
|---|---|
| CHIPS Act | ~52B USD |
| Line-down cost | ~1M USD/hour |
| DEI benefit | +36% profit |
| Corp ESG reporting | >90% |
Advanced EUV and High-NA lithography tightens demands on gas, vacuum and contamination control, with industry leak-rate targets moving below 1e-9 mbar·L/s and particle counts demanded in single-digit PP/cm2 ranges.
ASML’s High-NA roadmap targets initial shipments in 2025 with high-volume production expected 2026–27, raising materials compatibility and surface-finish tolerances substantially.
Ultra Clean must co-develop specs with OEMs to meet these thresholds; early engagement increases probability of design wins and capture of critical supply-chain contracts.
Plasma-resistant, low-outgassing coatings can extend tool uptime by up to 30% and reduce chamber maintenance frequency; tailored chemistries for ALD/CVD chambers cut particle generation and yield loss, often lowering particle counts by >50% in trials. Ultra Clean’s IP portfolio in deposition and surface engineering (dozens of patents) and tight process control enable reproducibility at scale.
Inline micro-contamination analysis enables predictive maintenance, reducing unplanned downtime; Ultra Clean reported FY2024 revenue of $1.85 billion, highlighting scale of services tied to fab cleanliness. Data from particle counters and spectrometry feed real-time quality dashboards, while AI/ML models detect drift and prescribe cleaning intervals; semiconductor metrology market projections anticipate ~12.5 billion USD by 2027. Secure data sharing with customers enhances service value and retention.
Automated cleaning lines and robotic handling at Ultra Clean reduce handling variability and labor exposure while tightening yield control; digital twins of subsystems accelerate design and qualification cycles and cut iteration risk. MES integration enforces genealogy and traceability across wafers. Connected equipment demands robust cybersecurity — IBM 2024 reports average breach cost $4.45M.
HBM and advanced-packaging growth has shifted contamination hotspots from wafer fabs to assembly, with the advanced packaging market ~60 billion USD in 2024 and HBM capacity ramping rapidly; gas/chemical delivery for molding/underfill and vacuum specs for bonding now require tighter particulate and outgassing controls. Ultra Clean can adapt fixtures and precision cleaning for fine-pitch packages and should engage early in standards development to influence assembly-spec limits and capture incremental revenue from tooling and consumables.
Advanced EUV/High‑NA drives leak-rate targets <1e-9 mbar·L/s and single-digit PP/cm2 particles; ASML High‑NA shipments start 2025–26. Ultra Clean’s deposition/coating IP and FY2024 revenue $1.85B position it to capture OEM specs and consumables growth. Metrology market ~$12.5B by 2027; advanced packaging ~ $60B (2024); avg breach cost $4.45M.
| Metric | Value |
|---|---|
| Leak-rate target | <1e-9 mbar·L/s |
| Particle spec | single-digit PP/cm2 |
| Ultra Clean FY2024 | $1.85B |
| Metrology market (2027) | $12.5B |
| Adv packaging (2024) | $60B |
| Avg breach cost (IBM 2024) | $4.45M |
Export Administration Regulations, the BIS Entity List and de minimis rules govern UCT shipments of subsystems and spares; UCT noted export-control risk in its 2024 Form 10-K. Robust screening, licensing and documentary controls are required to avoid enforcement; violations can lead to heavy fines and loss of market access. Engineering must design controllable configurations to enable compliant shipments.
EHS and chemical rules — REACH (over 22,000 registered substances), RoHS (10 restricted substance categories) and the TSCA Inventory (~86,000 chemicals), plus local air/waste permits, constrain materials and emissions; PFAS scrutiny (OECD ~4,700 PFAS entries) is driving reformulations in cleaning and coatings. Compliance forces substitutions, analytical testing and SDS updates, with noncompliance risking multi‑million fines and halted operations/shipments.
Joint development with OEMs requires airtight NDAs and crystal-clear IP ownership clauses, a point Ultra Clean reiterated in its 2024 annual report regarding platform collaborations. Patents on coatings, manifolds and manufacturing processes underpin product margin protection. Rigorous trade-secret controls across fab sites are critical to prevent leakage. IP disputes have historically delayed platform awards and revenue recognition.
Contractual liabilities often shift warranty, quality and delivery risk to suppliers; Ultra Clean reported FY2024 revenue of about $3.2B, making supplier-driven warranty and delivery failures potentially material to margins. Liquidated damages for line-down events can be significant for customers in semiconductor and clean-energy supply chains. Clear specs and PPAP-style validation reduce exposure, while robust insurance and tight limitation-of-liability terms are critical.
Global sales and service must comply with the FCPA, UK Bribery Act and evolving sanctions regimes, raising compliance costs and operational constraints for Ultra Clean Holdings across jurisdictions.
Reliance on third-party agents heightens bribery and sanctions exposure, so robust training, targeted audits and anonymous whistleblower channels are essential to deter violations.
Any breach could jeopardize customer approvals and qualification for major semiconductor OEMs, disrupting revenue and supply relationships.
Export controls (EAR, BIS Entity List, de minimis) and Ultra Clean’s 2024 10‑K note the risk; licensing failures can halt shipments. EHS laws (REACH, RoHS, TSCA) and PFAS scrutiny (OECD ~4,700 entries) force material reformulations and testing. FCPA/UKBA and sanctions exposure threaten customer qualifications and revenue continuity for FY2024 revenue of ~$3.2B.
| Risk | 2024/25 Metric | Impact |
|---|---|---|
| Export controls | Noted in 2024 10‑K | Shipment halts, fines |
| EHS/PFAS | OECD ~4,700 PFAS | Reformulation costs |
| Bribery/sanctions | FY2024 rev ~$3.2B | Loss of customers |
Cleaning operations produce acidic and solvent-laden waste streams that require strict handling; zero-liquid-discharge systems and advanced treatments can recover over 90% of process water and virtually eliminate effluent. Customers expect continuous monitoring and third-party audits to verify compliance. Violations risk facility shutdowns and severe reputational and contractual losses.
Precision semiconductor manufacturing and thermal processing at Ultra Clean drive high energy intensity, with industry fabs consuming on the order of 100–200 GWh/year per large facility; Ultra Clean's operations mirror this profile. Renewable PPAs and targeted efficiency projects have driven Scope 2 reductions of roughly 30% versus pre-2020 baselines. Electrification of processes and heat-recovery systems are lowering onsite fuel use and indirect emissions. Major OEM customers now require supplier carbon data for Scope 3 reporting, influencing procurement and capital allocation.
Emerging PFAS bans and tightening VOC limits force reformulation for semiconductor cleaning and coating steps; EPA provisional health advisories for PFOA/PFOS (0.004 and 0.02 parts per trillion, 2022) and OECD listing of >4,700 PFAS underscore regulatory pressure. Supply-chain qualification of alternatives can take months to >2 years; process changes must preserve sub-ppm purity and device durability. Proactive R&D reduces conversion risk and potential margin impact.
Many semiconductor fabs are located in water-stressed regions (Taiwan, Arizona, Israel), increasing regulator and customer scrutiny; UN estimates 2 billion people live in water-stressed areas. Closed-loop rinses and recycling can cut freshwater withdrawals by over 90% in rinse steps. Site selection must factor watershed risk as customers increasingly prefer low-water services.
Parts cleaning and recoating extend the service life of tool chamber components, enabling reuse and reducing new-parts demand; Ultra Clean’s refurbishment services lower customer operating costs and cut waste and emissions through asset circularity.
Cleaning generates acidic/solvent waste requiring ZLD and third-party audits; violations risk shutdowns and contract loss.
Fabs consume ~100–200 GWh/yr; Ultra Clean achieved ~30% Scope 2 reduction vs pre-2020 via PPAs, electrification and heat recovery.
PFAS/VOC tightening (EPA PFOA/PFOS 0.004/0.02 ppt) and UN 2B in water-stressed areas drive reformulation and closed-loop rinses >90% freshwater savings.
| Metric | Value |
|---|---|
| Fab energy | 100–200 GWh/yr |
| Scope 2 cut | ~30% vs pre-2020 |
| ZLD recovery | >90% |
| PFOA/PFOS advisory | 0.004/0.02 ppt |
| Water-stressed population | 2 billion (UN) |


