
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
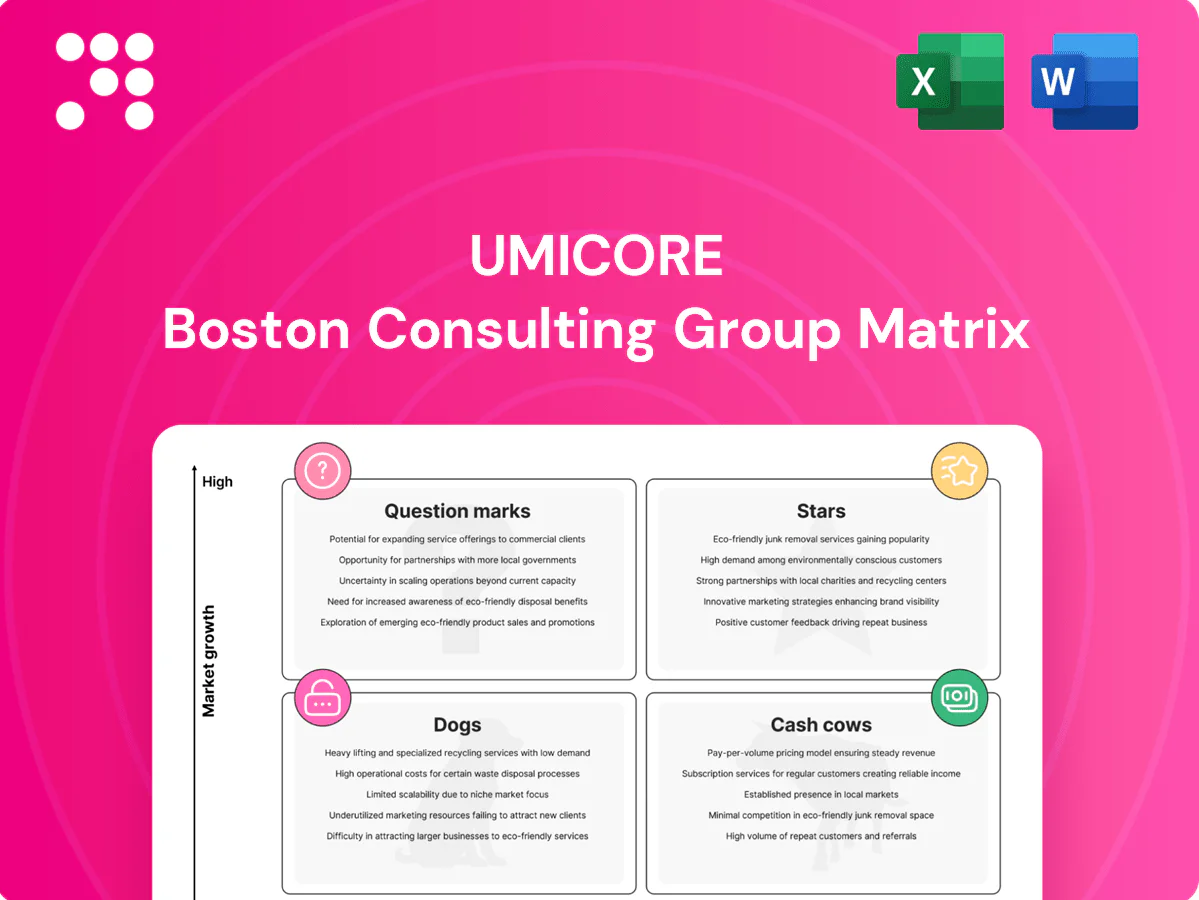
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Umicore’s BCG Matrix shows which materials and tech are fueling growth, which generate steady cash, and which need tough choices—this snapshot helps you see where value really sits. Want the full picture? Buy the complete BCG Matrix for quadrant-by-quadrant placements, data-backed moves, and Word + Excel files you can use to act fast and confidently.
High-growth EV demand (global EV sales ~14 million in 2023 per IEA, continuing into 2024) places Umicore’s cathode active materials in the Stars quadrant; the company already holds meaningful share via OEM tie-ups and qualification wins. Capital intensive to scale, but scale drives cost advantage and stickier contracts. Keep feeding capacity and convert today’s growth into tomorrow’s cash; if share holds as market normalizes, this becomes the engine.
Circular-economy tailwinds have kept feedstock rising, supporting Umicore’s precious-metals recycling growth; its integrated smelting–refining footprint yields higher recovery rates and favourable metal mix versus peers. The recycling arm is cash-generative but requires steady throughput and ongoing compliance capital. Stay invested to protect market share and broaden feed sources.
OEMs want one-chain take-back to cathode and Umicore uniquely operates both cathode active material and battery recycling plants, enabling true closed-loop supply. High switching costs and trust create durable customer ties while the lithium-ion battery recycling market reached about USD 3.1 billion in 2024 and is expanding rapidly. These loops absorb capital early but typically pay back on contracted volumes; secure logistics and long-term contracts now, defend pricing later.
Qualification moats with top OEMs create platform-level stickiness for Umicore in cathode active materials; once qualified, contracts and process certifications sustain years of supply. The EU push for local, lower-carbon battery supply under the Critical Raw Materials framework favors Umicore’s European footprint and recycling capabilities. Growth visibility is improving through multi-year offtakes and on-time ramping is critical to lock share before new entrants scale.
High-nickel and manganese-rich next-gen CAM are Stars: they command premium slots in long-range EVs and sit in a high-growth, high-margin segment; BNEF cited a global battery pack average of ~132 USD/kWh in 2023, pushing suppliers to cut $/kWh. Umicore’s process IP and strong safety record help win demanding specs and heavy QA from OEMs. To remain first call, double down on cost per kWh and traceable sustainable sourcing.
High-growth EV demand makes Umicore’s cathode active materials and recycling Stars; scale and OEM qualifications drive stickiness and margin upside. Recycling market was ~USD 3.1B in 2024, supporting feedstock and cash generation. Focus: ramp capacity, secure multi‑year offtakes and cut $/kWh to protect premium CAM positions.
| Metric | Value | Year |
|---|---|---|
| Battery pack avg | ~132 USD/kWh | 2023 |
| Recycling market | 3.1B USD | 2024 |
 Detailed Word Document
Concise BCG review of Umicore's units: Stars, Cash Cows, Question Marks, Dogs with clear invest, hold or divest guidance.

 Customizable Excel Spreadsheet
One-page BCG Matrix for Umicore, clarifying unit positions and easing strategic decisions.
Gasoline automotive catalysts (TWC) are a mature, high-share cash cow for Umicore: 2024 volumes showed low single-digit growth while operational efficiency and metal management preserved robust margins (EBIT margins in the mid-teens reported across catalysts in 2024). Low incremental marketing spend is needed; focus is on milking cash flows and maintaining near-perfect plant reliability and supply continuity.
Diesel aftertreatment aftermarket is a cash cow: the market is steady-to-drifting down, with global diesel vehicle parc contraction ~1% CAGR 2020–2024 but an installed base still driving recurring service demand; aftermarket parts accounted for roughly 60% of segment volumes in 2024. Strong channels and proven formulas yield predictable orders and ASP stability. Optimize SKUs to target 8–10 inventory turns and tighten working capital to preserve cash conversion; capex limited to efficiency and compliance upgrades in 2024.
Precious metals management and hedging services are a cash cow for Umicore: trusted handling of PGM streams generates sticky, fee-rich revenues that show low organic growth but sustain cross-selling across catalyst, recycling and materials businesses. Robust systems, treasury controls and counterparty risk frameworks form the operational moat. Maintain the platform’s CAPEX and compliance spend; let its steady cash fund growth bets in batteries and recycling expansion.
Umicore’s electroplating chemicals for connectors and PCB components occupy niche positions in a mature electronics supply chain, yielding stable volumes, repeat customers and a favorable product mix; pricing power is modest while service and quality drive retention. Lean operations and selective automation sustain healthy margins despite competitive pressure.
Specialty cobalt/metal compounds for ceramics and catalysts are not flashy but dependable, with long-standing formulations and customer retention that drove a steady contribution within Umicore’s materials portfolio in 2024; the business showed low churn and acted as a reliable cash generator despite commodity swings.
Modest capex needs and tight working-capital management preserved cash flow in 2024; avoid large-scale capacity expansion and prioritize cost discipline to protect margins and ROI.
Gasoline catalysts: low-single-digit volume growth in 2024, EBIT margins mid-teens; Diesel aftermarket: ~1% CAGR decline 2020–2024, 2024 aftermarket ~60% volumes; Precious metals services: fee-rich, low growth; Electroplating/specialty metals: stable volumes, modest pricing power; 2024 theme: modest capex, tight working capital, prioritize cash generation.
| Segment | 2024 metric | EBIT% (2024) | Capex focus |
|---|---|---|---|
| Gasoline TWC | Low +single-digit vol | Mid-teens | Maintenance |
| Diesel AM | 60% vol, -1% CAGR | Mid-teens | Efficiency |
| PGM services | Sticky fee rev | High-single-digit | Platform upkeep |
The Umicore BCG Matrix you’re previewing is the exact file you’ll get after purchase. No watermarks, no placeholders—just the finalized, fully editable matrix built for strategic decisions. It arrives ready to print, present, or drop straight into your planning decks. Buy once and use immediately, no surprises.
Regulatory and consumer shifts have shrunk the addressable market for light-duty diesel catalysts, with EU diesel passenger-car share declining to about 28% in 2023 (ACEA) and tighter standards such as the Euro 7 proposal further reducing long-term demand.
Market share gains cannot reverse a shrinking pie, so continued investment to defend share risks low returns.
Costly turnarounds drain cash and delay redeployment of capacity.
Manage orderly runoff, redeploy people and tooling to growth areas like battery materials and emissions aftertreatment for hybrids.
Legacy thin-film PV materials are a niche segment, representing roughly 5% of global module shipments in 2023, with demand concentrated in specialized applications. Asian manufacturers dominate PV capacity (>80% of global module manufacturing), creating intense price and scale pressure. Uneven tech roadmaps and low market share plus low growth make this a classic BCG Dog. Avoid fresh capex; exit or quietly park the asset.
Low-margin generic metal refining streams: high processing complexity with low ticket sizes and minimal product differentiation, tying up working capital and compliance overhead while delivering weak returns. A 2024 portfolio review flagged these streams as structurally unattractive versus higher-return feeds elsewhere. Prune aggressively to redeploy capital into differentiated cathode, recycling and battery materials.
Older portable-battery materials SKUs for handhelds moved in 2024 to tighter, price-led supply chains; market share is thin and margins are materially compressed, leaving no strategic advantage and limited pricing power; recommended action is to sunset low-return SKUs and redeploy capacity to EV chemistries.
Non-core minor alloys and tiny bespoke orders are operational dogs: tiny lots, bespoke specs and endless changeovers create material operational drag with scant payoff; tail SKUs often consume disproportionate shopfloor time while customers decline to pay premia for the hassle.
Diesel catalysts: EU diesel PC share ~28% in 2023; shrinking market drives low ROI on defense spend.
Thin‑film PV ~5% of module shipments (2023); >80% module capacity in Asia; niche, price‑pressured, low growth.
Low‑margin metal refining and legacy battery SKUs flagged in 2024 review; recommend exit/sunset and redeploy to EV cathode/recycling.
| Segment | Share/Growth | 2024 Status | Action |
|---|---|---|---|
| Diesel catalysts | 28% EU (2023)↓ | Shrinking | Runoff |
| Thin‑film PV | ~5% (2023) | Niche | Exit |
Industrial battery recycling is a Question Mark: huge runway as global EV parc and battery waste surge (global lithium‑ion recycling market projected to grow >30% CAGR from 2024), but unit economics hinge on yield, collection logistics and volatile metal prices (Ni, Co, Li). Early scale brings cash burn and uncertain feed quality plus policy risk (extended producer responsibility evolving across EU/US in 2024). If process KPIs (recovery rates, throughput, OPEX) trend favorably, scale aggressively to lock OEM loops; if not, pursue partnerships or pivot to tolling/service models.
Capacity wins orders but execution wins profit: North America and EU CAM greenfield ramps must hit nameplate to convert strong 2024 demand—global EV sales ~15 million in 2024—into revenue. Market is hot, yet share isn’t guaranteed until lines qualify; ramp flawlessly and secure multi‑year offtakes to protect margins. Miss timelines and high fixed costs push these projects rapidly toward dog territory.
Policy tailwinds are promising—EU RePowerEU targets 10 million tonnes of renewable hydrogen by 2030—yet adoption slope remains unclear across sectors. Tech is adjacent to Umicore’s strengths, but automotive and heavy-duty cycles are lumpy, causing demand volatility. Recommend place-focused bets with lighthouse customers and defer broad scaling until unit economics and repeatable cost per kW/kg prove robust.
High-manganese/LFP-adjacent tech sits in Question Marks: if cell cost targets approach BNEF 2024 pack baseline of $132/kWh, mid-range EV volumes could open rapidly, but competition is intensely price-led. Pilot and co-develop with OEMs, monitor real-world cycle and calendar durability data closely, and only commit scale when specs and degradation curves stabilize.
Advanced e-scrap urban mining sits as a Question Mark: regulatory tailwinds (EU Battery Regulation, 2024 updates to waste rules) boost demand but messy feedstock and collection friction raise costs, and process complexity can erode margins early. Build upstream partnerships to secure steady feed; invest only if recovery rates exceed industry benchmarks (eg above ~85–90% for target metals), otherwise license or pause.
Umicore Question Marks face big upside but execution risk: lithium‑ion recycling market >30% CAGR from 2024, EV parc ~15M units in 2024, but margins hinge on recovery, feed quality and metal prices. Target cell tech must hit BNEF 2024 pack baseline $132/kWh to scale. Pilot with OEMs; invest only if recovery >85–90% and nameplate ramps reliably.
| Segment | 2024 signal | KPI | Decision |
|---|---|---|---|
| Recycling | >30% CAGR | Recovery % / throughput | Invest if >85% |


