
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
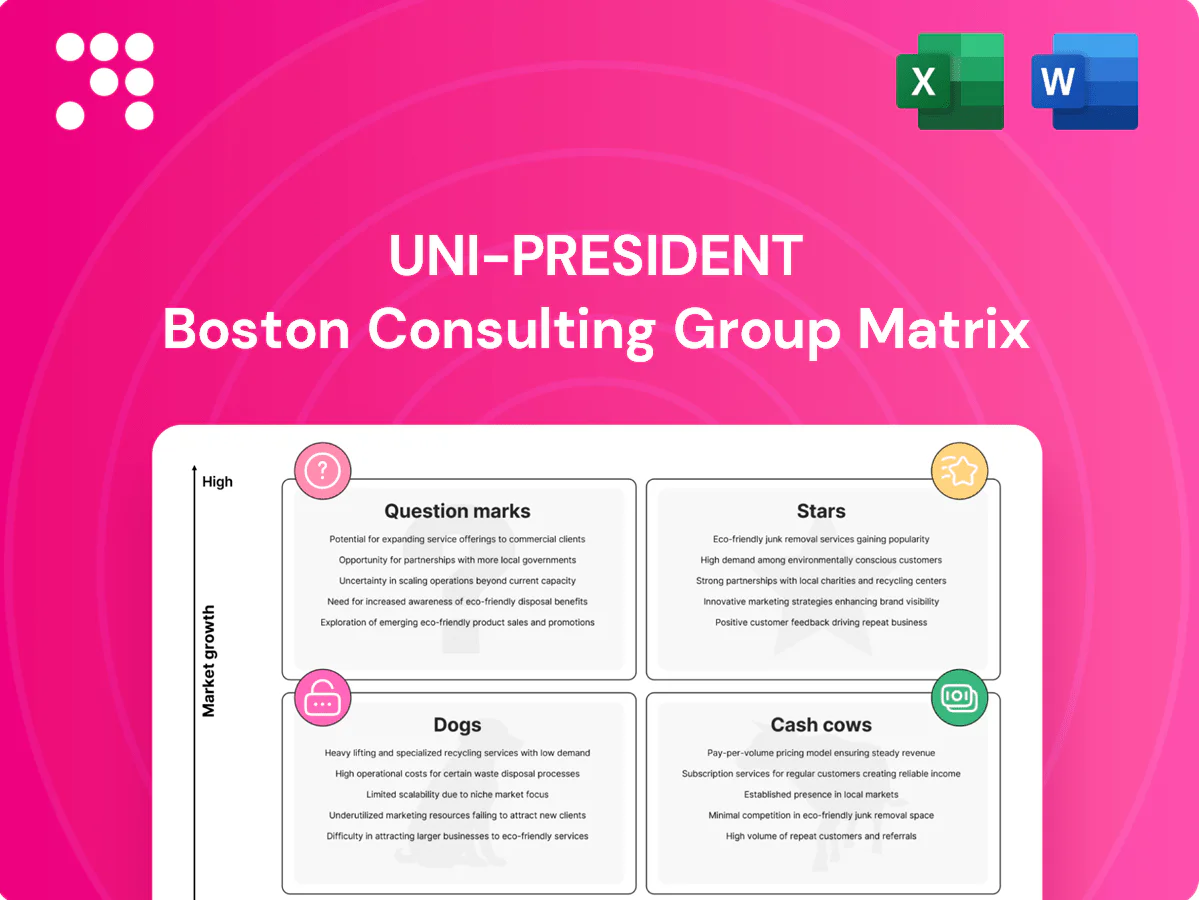
Uni-President’s BCG Matrix preview shows where key brands sit—fast-growing Stars, reliable Cash Cows, risky Question Marks, and underperforming Dogs—so you can see the broad strokes at a glance. Want the playbook? Buy the full BCG Matrix for quadrant-by-quadrant placement, data-backed recommendations, and strategic moves tailored to this company. You’ll get a ready-to-use Word report plus an Excel summary to present and act on immediately—skip the guesswork and make smarter allocation decisions today.
RTD tea and flavored beverages are a fast-growing category—global RTD tea market ~USD 50 billion in 2024 with roughly 6% CAGR projected to 2029. Uni-President already occupies extensive shelf space across core markets, backed by a strong flywheel of distribution, cold-chain logistics and promotional muscle. To remain top-of-mind they need continued heavy investment in innovation and premium placement. Keep the pace and these SKUs stay market leaders as the category scales.
Health-forward dairy drinks (yogurt, probiotic, milk tea) show strong uptake, with Uni-President covering multiple price points and reported category sales growth around 5–7% in 2024. High repeat purchase and cooler visibility drive volume, but promo spend runs high (estimated ~15% of category revenue). Defending cooler space and launching line extensions is critical; done right, this pipeline can convert into future cash cows.
Consumers are trading up into premium instant noodles, and Uni-President can command premiums via proprietary flavor IP and celebrity/chef collabs; global premium noodle value grew about 11% in 2024 versus ~2–3% for classic noodles. The segment is expanding faster than core SKUs, driving real share gains even as marketing and rapid innovation cycles keep it cash-burning. Hold share while the category rides its growth curve.
Convenience-led ready-to-eat sandwiches, bentos and on-the-go meals are Stars for Uni-President, fueled by urban grab-and-go habits and Taiwan’s dense retail network (7-Eleven ~5,900+ outlets across 2023–24). Strong retail tie-in gives fast velocity but requires meticulous cold-chain and SKU refresh; keep investing in assortment and speed-to-shelf to sustain double-digit margin potential.
Selective Southeast Asia beverage plays are showing early wins in fast-growing markets with room to scale, posting double-digit revenue growth in 2024 as distribution partnerships gain traction while marketing spend remains high. Pushing route-to-market and localized flavors can cement leadership pockets in urban cores and secondary cities. If momentum holds, market share gains can compound rapidly across the region.
Stars: RTD tea (global USD 50bn in 2024, ~6% CAGR to 2029) and health dairy (category +5–7% in 2024) lead with distribution scale; premium noodles grew ~11% in 2024 and RTE meals show double-digit urban velocity via 7‑Eleven 5,900+ outlets. Maintain heavy promo, SKU refresh and cold-chain investment to lock market leadership and convert to cash cows.
| Segment | 2024 growth | Key KPI | Invest |
|---|---|---|---|
| RTD tea | ~6% CAGR | USD 50bn market | innovation, placement |
| Health dairy | 5–7% | repeat purchase | promo, coolers |
| Premium noodles | ~11% | price premium | R&D, marketing |
| RTE meals | double-digit | 7,900+ touchpoints | cold-chain, SKU refresh |
 Detailed Word Document
Uni-President BCG Matrix: maps Stars, Cash Cows, Question Marks and Dogs with clear invest, hold or divest recommendations.

 Customizable Excel Spreadsheet
One-page Uni-President BCG Matrix that instantly spots underperformers and focuses resources where growth matters most.
Uni-President’s convenience-store arm, with a network of over 5,000 stores as of 2024, delivers high share and steady footfall, producing predictable cash flow and consistent same-store sales growth in the low single digits. Margins are enhanced by private-label penetration and negotiated supplier terms, driving 150–200 basis points of gross-margin upside versus non-branded peers. Capex remains disciplined (around 2% of sales in 2024) while operational efficiencies—inventory turnover and labor scheduling—lift yield, a classic milk-it-while-optimizing-mix cash cow.
Core instant noodles (mainstream SKUs) sit on a large installed base and deliver habitual, repeat consumption within a stable category, keeping promotional needs modest relative to the scale they provide. Manufacturing and logistics are highly efficient with long-amortized assets and sunk supply-chain scale advantages. The cash generated from this low-variation, high-turnover business funds Uni-President’s newer growth bets and innovation investments.
Ambient teas and classic beverages remain cash cows for Uni-President (TWSE: 1216), moving steady volumes in mature channels with tepid growth but entrenched share. Strong trading terms and shelf equity deliver reliable margins that fund growth initiatives elsewhere. Maintain the base—protect distribution and in-store presence, don’t overspend on growth experiments.
Dairy staples (UHT milk, everyday lines) act as Uni-President cash cows: 2024 saw stable household demand, robust distribution through HORECA and retail channels, and minimal innovation risk; price architecture is already optimized so margin gains come from incremental efficiency and packaging tweaks, keeping the segment a steady cash contributor with limited growth drama.
Integrated logistics for Uni-President functions as a cash cow: backbone assets largely amortized by scale, utilization rates reported high in 2024 with predictable unit costs, and process tweaks (route optimization, slotting, cross-dock) incrementally lift EBIT while capex needs remain low; management continues to sweat the network to deliver steady cash flow.
Uni-President cash cows (convenience stores, instant noodles, ambient beverages, dairy, logistics) generated predictable cash flow in 2024: >5,000 stores, same-store sales growth low-single-digits, gross-margin uplift 150–200bps from private label, capex ~2% of sales; management prioritizes sweating assets and funding new bets.
| Segment | 2024 KPIs |
|---|---|
| Convenience | >5,000 stores; SSSG low-single-digits |
| Instant noodles | High turnover; low promo |
| Margins/Capex | +150–200bps; capex ~2% sales |
The Uni‑President BCG Matrix file you're previewing is the exact document you'll receive after purchase. No watermarks, no demo text—just a fully formatted, analysis-ready report tailored for strategic clarity. After buying, the full file is delivered instantly for editing, printing, or presenting to stakeholders. It's professionally designed and ready to plug into your planning process.
Department stores in Uni-President’s BCG Matrix sit in the Dogs quadrant: low growth amid intense competition from e‑commerce and specialty retailers, with global e‑commerce taking about 22.3% of retail sales in 2024, eroding foot traffic. Capital is tied up in real estate and slow-moving inventory, often showing inventory turns below 3x, and costly turnarounds rarely stick. These units are prime candidates for pruning or repositioning.
Legacy frozen SKUs suffer fragmented shelf presence, weak consumer pull and elevated cold-storage overheads; cold-chain logistics typically add roughly 20–30% to distribution costs versus ambient lines. With retail food waste around 30% globally (FAO), many of these SKUs only break even once wastage is included. Heavy marketing is hard to justify; rationalizing SKUs and redeploying freezer capacity yields better ROI.
Non-core bakery lines deliver nice products but limited throughput, contributing roughly 3% of Uni-President’s 2024 consolidated revenue (NT$861 billion) and underperforming core snack and beverage segments. Complexity from ~150 niche SKUs in 2024 taxes plants and logistics, raising per-unit costs by an estimated 5–7% versus mass lines. Little brand leverage exists beyond micro-segments, so trim SKUs and redeploy resources to proven winners.
Dogs: Small animal feed sub-lines without scale sit in the BCG Dogs quadrant — exposed to commodity-driven price swings, thin gross margins (industry pet/animal feed margins often low) and no clear competitive edge; working capital ties up cash in slow-moving inventory, and incremental upside rarely offsets management distraction, so exit or consolidation is warranted.
Underperforming regional beverage tails show low share, me-too flavors and limited shelf priority; trade-area scans in 2024 show these SKUs capture negligible velocity versus national brands and promo dollars don’t move the needle.
Keeping them clutters the portfolio and raises carrying and opportunity costs amid 2024 SKU-rationalization pressure across FMCG.
Time to delist low-velocity SKUs or bundle them into regional packs to recover shelf space and marketing ROI.
Dogs: low-growth, low-share units (dept stores, frozen, niche bakery, small animal feed) tie capital in real estate/inventory (inventory turns <3x), face e‑commerce pressure (22.3% retail sales in 2024) and high cold-chain/waste costs (food waste ~30%); bakery ~3% of Uni‑President 2024 revenue (NT$861bn). Exit, consolidate or redeploy resources.
| Metric | Value |
|---|---|
| Inventory turns | <3x |
| E‑commerce | 22.3% (2024) |
| Food waste | ~30% |
| Bakery share | 3% of NT$861bn (2024) |
Pet food and treats sit in Question Marks: global pet food market ~USD 115 billion in 2024 with premium segment growing ~8% CAGR, yet Uni‑President’s current share in pet care remains small. Brand permission is plausible given its food R&D and supply chain scale. Requires focused R&D and distinct premium positioning; invest to prove velocity or seek a strategic partner to accelerate market entry.
Plant-based dairy and protein drinks sit in a hot segment where the global plant-based dairy market exceeded $23 billion in 2024 and continues high-single-digit to low-double-digit growth, but competitors remain highly fragmented and regional. Early signs are promising yet inconsistent by market, so Uni-President needs taste leadership and aggressive cost-down to scale. Strategy: back a few hero SKUs with distribution and marketing or pull back fast to avoid margin drag.
Consumer interest in ready-to-heat premium frozen/chilled meals is rising alongside convenience trends; the global frozen food market was about $293 billion in 2024 (Statista). Execution hinges on taste, shelf life and competitive pricing. Retail tie-ins and promotions can accelerate trials; run pilots, measure repeat purchase rates and decide fast.
Digital retail media and data monetization sit as Question Marks for Uni-President: selling audiences, not just shelf space, can yield attractive margins often >50% for retail media platforms; global retail media ad spend is estimated at $160B in 2024, signaling demand. Capabilities are early and pricing power unclear; requires ad-tech stack and sales DNA. Recommend test-and-learn with tight KPIs (CAC, eCPM, ROAS).
New-market convenience formats target fast-urbanizing corridors (Taiwan/SE Asia urban growth ~1–2% p.a. in 2024) but scale is constrained by site scarcity, localized ops complexity and supply-chain buildout; typical new-store CAPEX runs TWD 3–6 million with payback often 18–36 months, making them capital hungry early — invest selectively where unit economics pencil.
Question Marks: pet food ~USD 115B (2024) needs premium R&D or partner; plant‑based dairy ~USD 23B (2024) demands taste + cost-down; frozen meals market ~USD 293B (2024) needs pilots to prove repeat; retail media ~USD 160B (2024) requires ad‑tech and sales build.
| Category | Market 2024 | Key metric | Action |
|---|---|---|---|
| Pet food | USD 115B | Premium CAGR ~8% | Invest/partner |
| Plant‑based | USD 23B | High‑single to low‑double % | Focus SKUs |
| Frozen meals | USD 293B | Repeat rate | Pilot |
| Retail media | USD 160B | Margin >50% | Test & KPIs |


