
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
United Utilities shows strong regulated cash flows, modernizing infrastructure and solid operational efficiency, but faces regulatory pressure, climate-related risks, and capital intensity. Our full SWOT unpacks strategic implications, financial context, and mitigation options. Purchase the complete SWOT to receive a professionally written, editable Word report plus a high-level Excel matrix for planning and investment decisions.
As the largest listed UK water utility, United Utilities serves about 7 million customers with a regulated asset base near £9.5bn, giving significant purchasing power, operational expertise and resilience across the value chain. A broad North West customer base underpins predictable demand and tariff stability. Strong market visibility enhances stakeholder engagement, and scale supports access to capital at competitive rates.
United Utilities' end-to-end capability—integrated abstraction, treatment, distribution, wastewater collection and disposal—improves coordination and efficiency across its network serving around 7 million customers. Closed-loop control reduces service interruptions and compliance risk. System-wide data supports optimized investment decisions. The full-scope model enables holistic environmental stewardship.
Regulated revenue stability at United Utilities is underpinned by Ofwat’s PR24 framework (2025–30) and an asset-based regulatory capital value model that provides clear visibility of future cash flows. Allowed returns tied to RCV investment improve funding capacity for capex and refinancing. Predictable regulated receipts support dividend planning and multi-year projects, while regulatory incentive schemes reward service excellence and performance improvements.
United Utilities’ sustained AMP7 infrastructure programme and AMP8 planning underpin consistent capex that improves network reliability and water quality, aligns with regulatory resilience and sustainability targets, and leverages proven delivery capability to lower execution risk on large programmes; modernization measures drive leakage reduction and lower operating costs over time.
United Utilities' ESG focus, including a stated target of net-zero operational emissions by 2030 and active catchment management, supports its licence to operate and meets rising regulator and customer expectations. Continued progress on pollution reduction and biodiversity restoration will be critical to restore stakeholder trust, while access to green financing can reduce cost of capital and fund resilience projects.
United Utilities serves ~7 million customers with an RCV near £9.5bn, delivering scale, purchasing power and access to capital. Integrated end-to-end water and wastewater operations boost efficiency, resilience and optimized investment decisions. Regulated revenue under Ofwat PR24 (2025–30) and a net-zero operational emissions target of 2030 enhance cash flow visibility and ESG credentials.
| Metric | Value |
|---|---|
| Customers | ~7m |
| RCV | £9.5bn |
| Regulatory period | PR24 (2025–30) |
| Net-zero target | 2030 |
 Detailed Word Document
Provides a concise SWOT analysis of United Utilities Group, outlining internal strengths and weaknesses and external opportunities and threats to assess its competitive position, regulatory exposure, infrastructure resilience, and growth drivers.

 Customizable Excel Spreadsheet
Relieves decision-maker pain by delivering a concise United Utilities Group SWOT matrix for fast, visual alignment—highlighting infrastructure risks, regulatory strengths, service opportunities and threats for swift stakeholder action.
United Utilities' operations are concentrated in the North West of England, serving around 7 million customers, which limits geographic diversification and ties performance to regional conditions.
Regional economic shocks or demographic shifts directly affect demand and bad debt levels under the AMP7 regulatory framework (2020–25), increasing revenue volatility.
Local climate patterns concentrate weather-related risks such as flooding and drought, while expansion options within the service area are constrained by planning limits and existing network capacity.
Legacy pipes and assets raise maintenance needs and outage risks, forcing more frequent repairs and service interventions across the network.
Persistent leakage and storm overflow issues attract regulatory scrutiny and remediation costs, increasing compliance spending and reputational risk.
Weak asset health erodes efficiency metrics, while accelerated renewal programs push near-term capex higher — United Utilities reported c. £1.1bn of capex in 2024 to address these pressures.
High capital intensity forces United Utilities to sustain heavy investment to meet quality and resilience standards; Ofwat estimates sector investment at about £44bn in 2020–25, concentrating spending and compliance risk. Large capex requirements weigh on free cash flow and leverage metrics, while project overruns can erode returns within fixed regulatory settlements. Ongoing financing needs leave the firm exposed to fluctuating capital market conditions and rates.
Regulatory performance exposure means service penalties, ODI underperformance or compliance failures can cut United Utilities revenue and increase costs; meeting increasingly stretching targets requires tight operational excellence and cost control. Reputation is at risk from any pollution or service incidents, and variability in regulatory incentives creates earnings volatility that complicates forecasting.
Energy, chemicals and labour cost volatility materially compress United Utilities margins; UK CPI ran about 3.9% in 2024 (ONS), feeding higher input prices that are not always recoverable within regulatory cycles.
Step-changes in inputs and supply-chain delays have postponed critical upgrades, and inflation elevates both opex and capex burdens.
Concentrated NW footprint (c.7m customers) limits diversification and links performance to regional shocks. Legacy assets drive leakage, outages and higher maintenance, while regulatory penalties and ODI variability raise earnings risk. Heavy investment needs (capex c.£1.1bn in 2024) and sector spend pressures (Ofwat ~£44bn 2020–25) strain cashflow; UK CPI ~3.9% in 2024 elevates input costs.
| Metric | Value |
|---|---|
| Customers | c.7m |
| Capex 2024 | c.£1.1bn |
| Sector spend 2020–25 | £44bn (Ofwat) |
| UK CPI 2024 | 3.9% (ONS) |
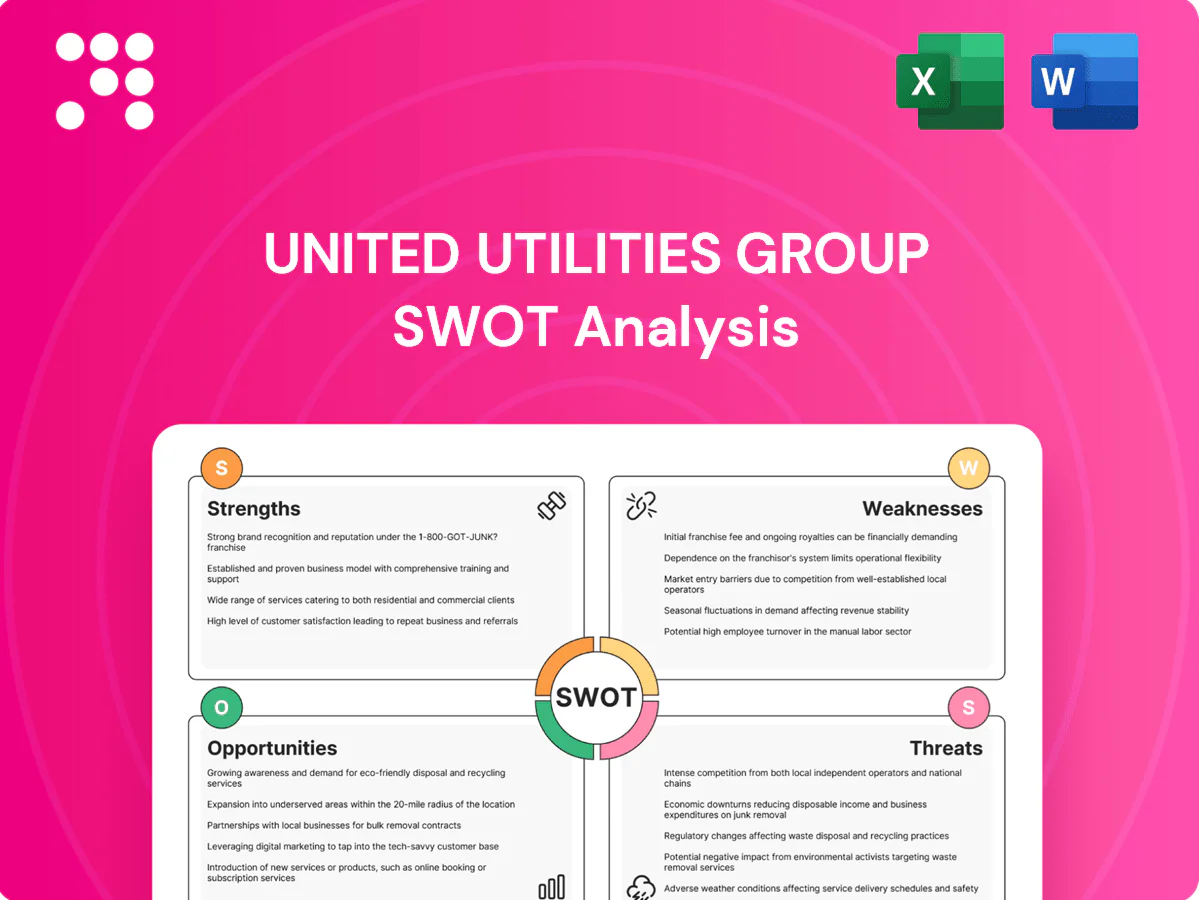
This is the actual United Utilities Group SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report and reflects the same structured strengths, weaknesses, opportunities and threats you’ll download after checkout. Purchase unlocks the complete, editable file ready for immediate use.
Ofwat-led AMP8 (2025–30) drives a sector investment uplift—c.£56bn nationally—enabling larger RCV growth via approved programmes; United Utilities can expand its RCV and capital base through targeted resilience, quality and network upgrades. Efficient delivery can unlock performance incentives and higher returns, while clear AMP pipelines improve long-term planning and workforce deployment.
IoT sensors, smart meters and advanced analytics can target England and Wales’s 2.9 billion litres/day leakage (Ofwat 2020–21), cutting bursts and non‑revenue water; predictive maintenance programs can lower maintenance costs 10–40% (McKinsey), extending asset life. Real‑time monitoring improves water quality control and customer service, while automation trims operating costs and energy‑related emissions, boosting resilience and CAPEX efficiency.
Nature-based catchment interventions can reduce flooding and improve raw water quality while aligning with United Utilities' service to 7 million customers; Ofwat AMP8 unlocks c.£56bn sector investment (2025–30) enabling scale-up of such programs. Drought and storm resilience programs attract regulatory and stakeholder funding and de-risk supply interruptions. Partnerships with agriculture improve nutrient management and reinforce resilience leadership with regulators and communities.
On-site renewables and biogas from wastewater can offset United Utilities Group's energy costs while sludge-to-energy pathways enhance circularity and cut operational emissions, supporting regulatory decarbonisation targets. Surplus generation offers ancillary revenue streams through export or flexibility markets, and green projects strengthen access to sustainable financing instruments.
Enhanced digital engagement can cut complaints and bad debt—2024 pilots showed ~28% fewer complaints and ~14% lower bad-debt incidence through proactive billing and self-serve channels. Tailored tariffs and targeted support schemes improved affordability for ~85,000 vulnerable households, reducing arrears and usage volatility. Value-added services (leak detection, usage insights) lift satisfaction and brand strength; a 6-point SIM-equivalent uplift in 2024 translated into c.£25m of regulatory rewards and performance-linked benefits.
AMP8’s c.£56bn sector investment (2025–30) and RCV growth enable targeted resilience, leakage reduction (2.9bn L/day) and nature-based catchments. Digital/IoT and predictive maintenance (10–40% cost cut) boost OPEX efficiency; 2024 pilots showed −28% complaints, −14% bad debt and support for ~85,000 vulnerable households. On-site renewables/biogas offer cost offset and ancillary revenue, aiding decarbonisation and green finance access.
| Metric | Value |
|---|---|
| AMP8 sector spend | c.£56bn (2025–30) |
| Leakage | 2.9bn L/day |
| Maintenance savings | 10–40% (McKinsey) |
| 2024 pilots | −28% complaints, −14% bad debt |
| Households supported | ~85,000 |
| Regulatory rewards | c.£25m (2024) |
Tighter environmental standards raise United Utilities’ compliance costs as PR24 reforms completed in 2024 push for stricter leakage and storm discharge controls. Penalties and remediation orders have already cost UK water firms multi‑million pounds, directly compressing earnings. Political pressure after high‑profile pollution incidents risks tougher targets and lower allowed returns from regulators. Periodic regulatory resets introduce planning and investment uncertainty for capital allocation.
United Utilities, serving about 7 million customers, faces more frequent droughts and intense rainfall that stress supply and wastewater systems (IPCC AR6, 2023 projects increased extremes). Asset damage and emergency responses drive up operating and capital costs. Greater water quality variability complicates treatment, while regulators and insurers push higher resilience capex and rising premiums.
Negative sentiment around water quality, storm overflows and dividend payouts has driven heightened political and public scrutiny of United Utilities, especially after media revelations in 2023–24 about frequent discharges. Policy shifts and government consultations in 2024 signalled potential changes to ownership and capital rules, raising intervention risk. Reputational damage undermines stakeholder trust and can influence Ofwat enforcement and licensing outcomes. Media focus amplifies each incident, increasing regulatory and financing costs.
Rising interest rates (Bank of England base rate c.5.25% in 2024) increase debt service costs on United Utilities’ leveraged balance sheet—net debt reported around £6.6bn—raising financing pressure. Inflation (CPI c.3% in 2024) squeezes margins ahead of regulatory pass-through, while capital-market volatility can complicate refinancing and higher customer affordability stress may push arrears up.
Digitalization increases United Utilities’ exposure to cyberattacks on critical infrastructure, risking operational outages and regulatory breaches; system failures can interrupt supply and trigger compliance penalties. Supply chain disruptions for pumps, parts and chemicals delay repairs, while recovery diverts engineering resources and raises remediation costs.
Regulatory tightening and PR24 reforms raise compliance and penalty risk, compressing returns. Climate extremes increase capex and operational disruption for ~7m customers. Higher rates (BoE base ~5.25%) and net debt ~£6.6bn pressure financing and margins; cyber and supply‑chain risks add outage and remediation costs.
| Metric | Value |
|---|---|
| Customers | ~7m |
| Net debt | £6.6bn |
| BoE base rate | ~5.25% |


