
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
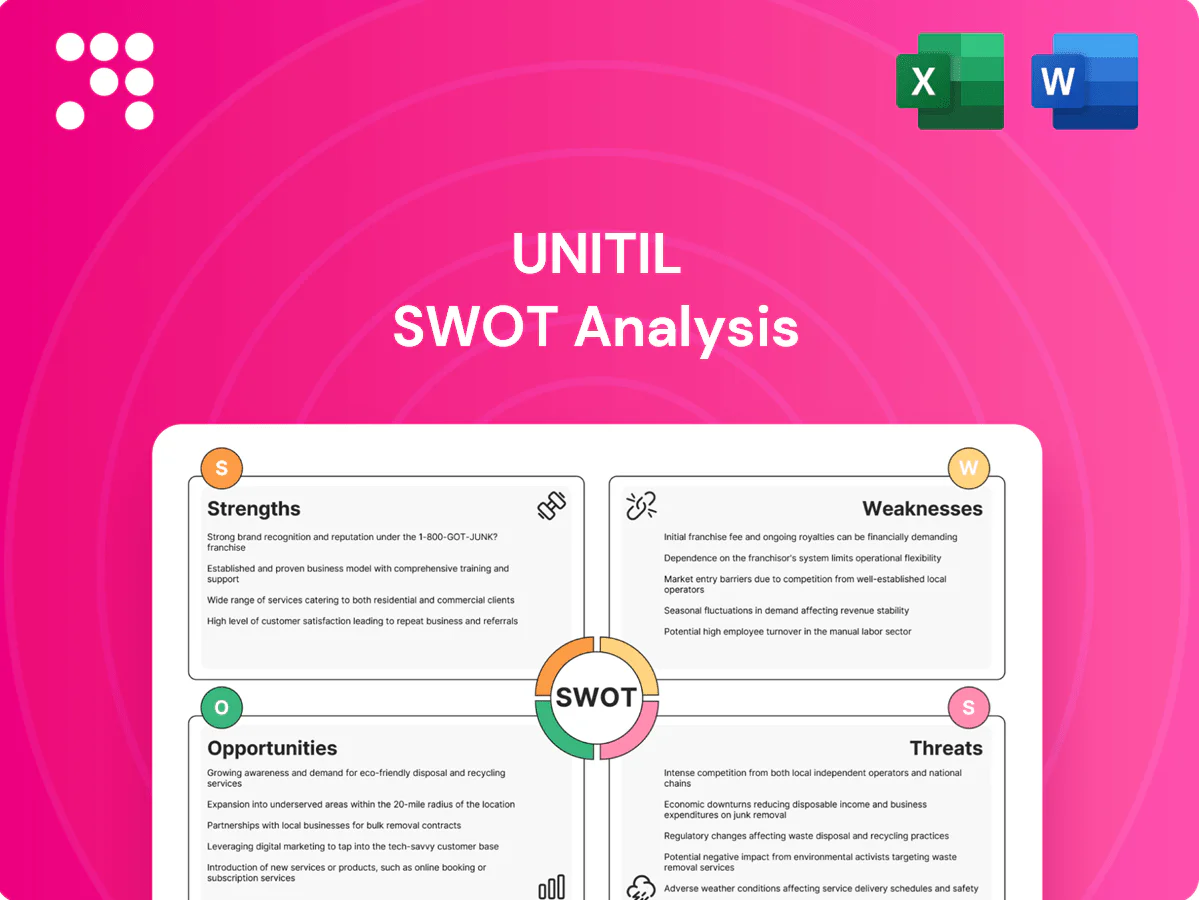
Our Unitil SWOT snapshot highlights the utility’s key strengths, regulatory risks, and growth levers across New England’s energy market. The full SWOT delivers research-backed analysis, strategic recommendations, and editable Word and Excel files for planning or pitching. Purchase the complete report to turn insights into confident decisions.
As a regulated utility, Unitil benefits from predictable cash flows and allowed returns on equity approved by state commissions, which materially reduce earnings volatility versus competitive energy businesses; rate mechanisms and recovery riders (including infrastructure and storm cost trackers) help align capital investment with cost recovery, supporting conservative leverage policies and a history of consistent dividends.
Unitil serves both electricity and natural gas customers across Maine, New Hampshire and Massachusetts, reaching roughly 110,000 electric and 86,000 gas accounts (2024). Dual-fuel exposure smooths seasonal demand and revenue volatility by offsetting summer/winter swings. Cross-utility operations enable shared overhead and field crews, lowering unit costs. It also supports coordinated planning for electrification and gas-transition investments.
Unitil operates mature distribution networks across New Hampshire, Maine and Massachusetts, serving roughly 170,000 regulated customers and supporting a consolidated utility rate base near $1.2 billion. Longstanding assets and rights-of-way create high barriers to entry, while deep local operating knowledge enhances system reliability and outage response. Embedded customer relationships have helped secure constructive regulatory outcomes and timely rate approvals.
New England regulatory frameworks support prudent investment in safety, reliability and modernization, with mechanisms such as decoupling and cost trackers that materially reduce volume and weather-driven revenue risk. Multi-year rate plans, commonly 3–5 years, improve capex visibility and smoothing of recovery, which underpins credit quality and lowers financing costs for utilities like Unitil.
Unitil's emphasis on reliability and safety drives continuous improvement through service-quality metrics used by regional regulators, reducing penalty exposure and strengthening credibility in rate cases; a strong safety culture lowers incident costs and reputational risk while reliable service supports local economic development and business retention.
Unitil's regulated status provides stable cash flows, recovery riders and multi-year rate plans that reduce volatility and support dividends. Dual-fuel service across ME, NH, MA (110,000 electric; 86,000 gas in 2024) smooths seasonality and lowers unit costs via shared ops. A ~$1.2B rate base and strong safety/reliability record aid favorable regulatory outcomes.
| Metric | Value |
|---|---|
| Electric accounts (2024) | 110,000 |
| Gas accounts (2024) | 86,000 |
| Regulated customers | ≈170,000 |
| Rate base | ≈$1.2B |
 Detailed Word Document
Provides a concise SWOT analysis of Unitil, outlining its operational strengths, regulatory and infrastructure weaknesses, growth opportunities in renewable energy and grid modernization, and external threats from market competition, regulatory shifts, and climate-related risks.

 Customizable Excel Spreadsheet
Provides a clear, high-level SWOT matrix tailored to Unitil for rapid identification of regulatory, grid resilience, and market risks, enabling executives to align strategy and communicate priorities quickly.
Unitil's operations are concentrated in New Hampshire, Maine and Massachusetts, with relatively modest service territories, increasing exposure to localized economic or regulatory shifts in those states.
This geographic concentration constrains customer growth potential compared with larger regional peers and limits diversification of rate base risk.
Scale limitations also reduce bargaining leverage with vendors and contractors, putting pressure on procurement costs and margin resilience.
Unitil faces high capital intensity with a 2024 system capital program of about $125 million, reflecting ongoing distribution replacement, hardening and modernization needs. Such large capex strains free cash flow and drives frequent rate filings (roughly every 3–5 years) to recover costs. Construction and labor inflation (recently running in the mid-single digits to low double digits) raises risk of cost overruns. Aging infrastructure elevates outage and safety risk without steady investment.
Earnings hinge on timely rate approvals and prudence determinations, and Unitil, which serves about 103,000 utility customers, can see returns compressed by the typical 12–24 month lag between investment and recovery. Adverse regulatory rulings can cut allowed ROE or disallow costs, directly reducing net income. The regulatory workload also raises administrative expense and distracts management from operations.
Unitil's service territory in New England faces frequent Nor'easters, ice storms and coastal wind events that elevate outage frequency and restoration costs; while regulatory recovery mechanisms reimburse portions of storm costs, timing and caps can compress quarterly earnings. Recurrent storm response strains line crews, worsens customer satisfaction metrics, and drives capital hardening needs that may outpace allowed rate recovery.
Unitil’s growth mix is heavily weighted to regulated operations, leaving few non-regulated businesses to drive incremental upside; earnings therefore depend primarily on rate-base expansion and approved rate cases. When capital spending plateaus, earnings growth can lag broader market peers with diversified merchant or competitive businesses. This concentration heightens exposure to regulatory timing, outcomes and single-jurisdiction risk.
Unitil concentrated in NH/ME/MA (3 states) with ~103,000 customers, limiting growth and diversification.
2024 system capex ~125,000,000 USD strains free cash flow; construction/labor inflation ~5–10% raises overrun risk; regulatory lag 12–24 months.
Frequent Nor'easters/ice storms boost outage/restoration costs, increase earnings volatility; limited unregulated revenue.
| Metric | Value |
|---|---|
| Customers | ~103,000 |
| 2024 Capex | $125M |
| Inflation | 5–10% |
| Regulatory lag | 12–24 months |
This is the actual SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full SWOT report you'll get; purchase unlocks the entire in-depth, editable version. You’re viewing a live preview of the real file; the complete document becomes available after checkout.
Advanced metering, distribution automation and resiliency upgrades can expand Unitil’s ratemaking base while 2024 U.S. smart meter penetration topping about 70% enables more granular cost allocation. Digitalization improves outage management and customer engagement, lowering SAIDI/SAIFI exposure and service costs. Cyber and physical hardening investments may qualify for trackers or incentives, and modern grids ease DER integration and flexible load management.
Rising EV adoption (US new EV sales ~7% in 2023) and accelerating heat pump installations (notable double‑digit growth in 2022–24) mean beneficial electrification can raise Unitil’s system load over time, supporting revenue growth. Managed charging programs and time‑varying rates can shift demand and lower peak costs, improving system efficiency. New interconnections and service upgrades create additional capital deployment opportunities for distribution investments. Customer programs that tie rebates, managed services and grid benefits can boost satisfaction and regulatory alignment.
Interconnecting community solar, storage, and rooftop PV increases Unitil’s planning and engineering workload as more DERs seek connection and require detailed hosting-capacity analysis. Deploying non-wires alternatives can defer costly traditional upgrades while creating new revenue streams through demand-related programs and avoided-capex solutions. Utility-owned or contracted storage improves reliability and adds capacity value, and publishing hosting capacity maps with streamlined, flexible interconnection policies accelerates DER growth.
Leak reduction, pipeline replacement and advanced leak detection support Unitil’s safety and emissions goals while aligning with EPA methane rules finalized in 2023 and state net-zero targets (Massachusetts 2050). Opportunities include RNG procurement, hydrogen blending pilots and network right‑sizing; targeted electrification plus gas optimization can lower system costs. Federal Inflation Reduction Act funding could enable regulatory recovery mechanisms for decarbonization investments.
Selective tuck-in acquisitions of adjacent distribution systems can add customers and create scale synergies for Unitil, spreading fixed costs and strengthening procurement leverage across materials and services. Asset swaps or joint ventures can optimize service territories while integration unlocks operational best practices across networks, improving reliability and margin.
Advanced grid digitalization, smart meters (US ~70% 2024) and resiliency upgrades can expand Unitil’s ratemaking base and reduce SAIDI/SAIFI. Electrification (EVs ~7% US new sales 2023) and heat‑pump growth raise load and capital opportunities; managed charging/time‑varying rates lower peaks. DERs, storage and non‑wires alternatives create interconnection and avoided‑capex revenues; IRA funding and EPA 2023 methane rules enable cost recovery.
| Metric | 2024/2025 data |
|---|---|
| Smart meter penetration | ~70% US 2024 |
| EV share (new sales) | ~7% US 2023 |
| IRA funding | $369B+ clean energy tax & grants |
| EPA methane rule | Finalized 2023 |
State climate laws aiming for economywide net-zero by 2050 and tightening building electrification codes in New England may accelerate electrification, shrinking gas throughput for Unitil. Stranded asset risk rises if regulators limit cost recovery for gas infrastructure. Political pressure could cap allowed ROE on gas investments, and transition misalignment may concentrate higher rates on remaining customers.
Rooftop solar, behind‑the‑meter storage and efficiency measures can flatten or reduce Unitil’s volumetric sales, while U.S. cumulative solar capacity surpassed 150 GW by end‑2023, accelerating behind‑the‑meter adoption. Net metering reforms risk shifting costs to non‑participating customers, pressuring regulatory and political dynamics. Lower sales compress revenue between rate cases despite decoupling variants, and bidirectional flows and hosting‑capacity limits increase planning and operating costs.
Rising U.S. rates—with the fed funds target around 5.25–5.50% and the 10-year Treasury near 4.2% (July 2025)—raises Unitil’s debt service, lowering earned returns on new projects. Equity market weakness increases dilution risk if external equity is required. Refinancing risk is elevated for maturing paper in tighter markets, and regulatory lag may not fully offset rapid spikes in financing costs.
Skilled labor shortages—NECA 2023 noting about 69% of contractors report workforce gaps—plus contractor scarcity raise Unitil project costs and timelines. Lead times for transformers, cables and meters remained elevated in 2024 at roughly 12–24 months. Cost pressures can exceed 2024 CPI (3.4%), risking higher rate-case allowances and potential recovery gaps; delays erode reliability metrics and customer satisfaction.
Utilities face rising OT and IT cyber threats; a successful intrusion could cause outages and trigger heightened regulatory scrutiny and fines. IBM reported the 2023 average data breach cost at $4.45 million, while NERC and state standards drive growing compliance spend. Insurers have tightened coverage and raised deductibles, worsening potential financial exposure.
Regulatory net‑zero and building electrification in New England threaten gas throughput and stranded‑asset risk; cost recovery limits could compress returns. Distributed solar, storage and efficiency (US solar >150 GW end‑2023) reduce volumetric sales and raise planning costs. Higher rates (fed funds 5.25–5.50%, 10y ~4.2% Jul‑2025), supply chain and labor shortages, and cyber risks (avg breach $4.45M 2023) heighten financial exposure.
| Metric | Value |
|---|---|
| US solar capacity | >150 GW (2023) |
| Fed funds | 5.25–5.50% (Jul‑2025) |
| 10y Treasury | ~4.2% (Jul‑2025) |
| Avg breach cost | $4.45M (IBM 2023) |


