
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
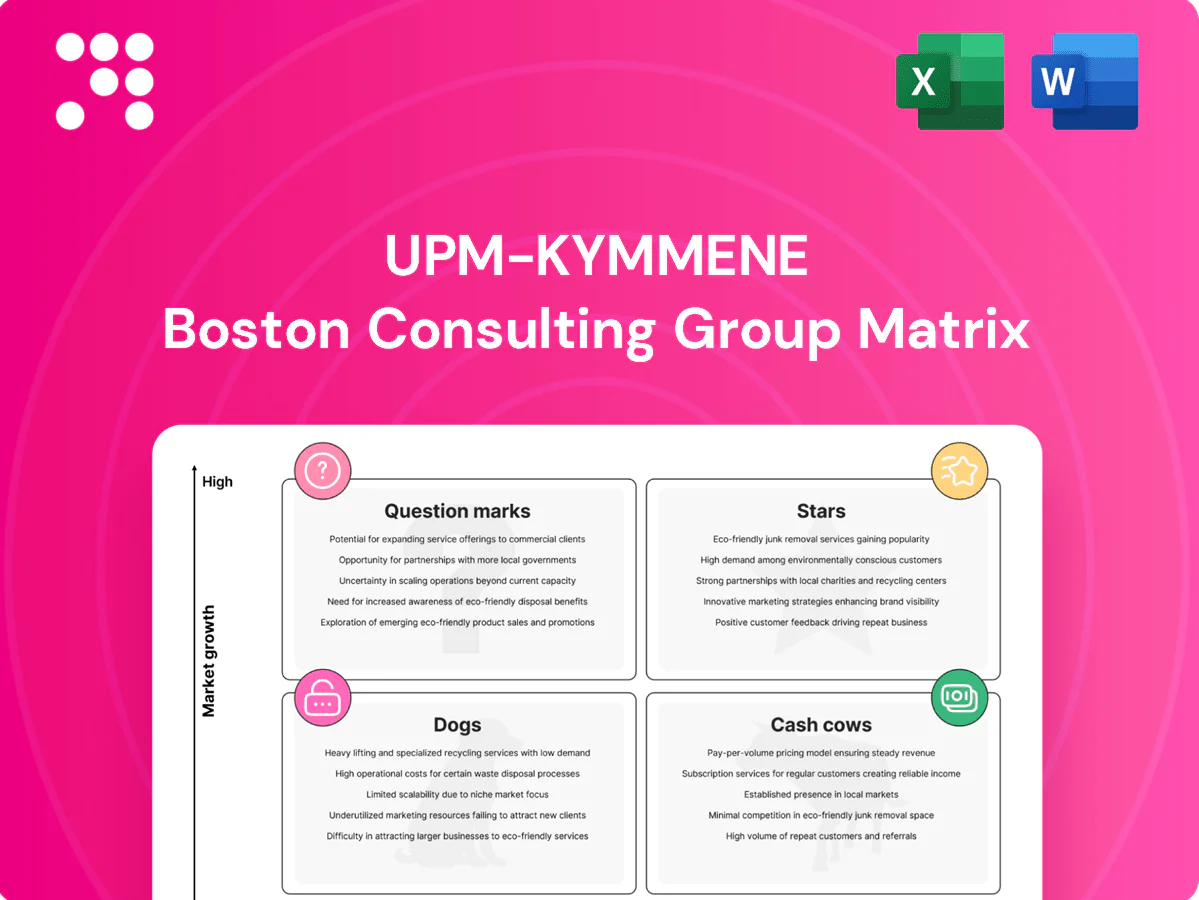
Curious where UPM‑Kymmene’s businesses sit—Stars, Cash Cows, Dogs or Question Marks? This snapshot hints at strengths and risks, but the full BCG Matrix gives quadrant-by-quadrant clarity, data-backed recommendations, and a ready-to-use roadmap for capital allocation and product strategy. Purchase the complete report for Word and Excel deliverables, visual maps, and strategic moves you can act on immediately.
UPM Raflatac label materials is a Star with strong global brand pull and growing end uses in e‑commerce and food packaging, driven by sustainability-led demand. Its leadership in recyclable and compostable labels keeps market share high as the category expands. Maintaining this position requires steady capex and sales investment to scale. Feed it consistently and it can mature into a larger cash engine.
Plastic-replacement tailwinds are real and sticky: Smithers 2024 forecasts paper-based packaging to reach about USD 398 billion by 2027, driven by regulatory bans and retailer commitments. UPM’s fiber know‑how and strong sustainability credentials secure specs and shelf space, supporting brisk segment growth. Winning requires capacity reallocation and customer education; expect continued capital intensity. Invest to hold share as the market scales.
High‑yield pulp for tissue and packaging is a star: secular demand from hygiene and containerboard keeps volumes rising and supports long‑term growth. Nordic low‑cost fiber gives UPM pricing power in upcycles and margin resilience. The business is capital intensive but generates strong free cash flow when the cycle turns. Focus: protect share, maintain reliability and scale to ride the growth.
Advanced biofuels BioVerno (launched 2014) sit in Stars: accelerating decarbonization mandates (ReFuelEU, EU Fit for 55 tightening 2024–25) boost demand for drop‑in, tall‑oil based fuels, giving UPM a credible edge with fleets and refiners; commercial scale, however, requires heavy capex and active policy navigation—backing it can compound into a flagship platform.
Green construction is climbing, with the global mass timber market valued at about USD 1.6bn in 2024, favoring certified engineered wood; UPM’s product quality and supply reliability secure large public and commercial projects across Europe and North America. Market growth keeps UPM in strong positions in key regions; maintain agile capacity and drive early spec‑in to lock share.
UPM Stars: Raflatac, high-growth label materials; paper-based packaging tailwinds (Smithers 2024 → paper packaging ~USD 398bn by 2027); pulp for tissue/containerboard rising with Nordic cost edge; BioVerno and mass timber (~USD 1.6bn 2024) are scaling but capex‑heavy—invest to defend share and scale capacity.
| Segment | Metric | Strength | Capex |
|---|---|---|---|
| Raflatac | Share high | Sustainability | Medium |
| Paper packaging | ~USD 398bn (by 2027) | Fiber know‑how | High |
| Pulp | Rising demand | Low‑cost fiber | High |
| BioVerno | Mandate growth 2024–25 | Drop‑in fuel | Very high |
| Mass timber | ~USD 1.6bn (2024) | Quality supply | Medium |
 Detailed Word Document
In-depth BCG review of UPM-Kymmene: identifies Stars, Cash Cows, Question Marks, Dogs with investment, hold, divest guidance.

 Customizable Excel Spreadsheet
One-page UPM‑Kymmene BCG Matrix mapping units into quadrants for fast strategic decisions and investor-ready slides.
Communication papers (graphic & office) are a mature, structurally declining market where UPM remains a scale leader with optimized mills and disciplined pricing that generate steady cash flow. Low promotional needs keep margins stable, while cost and product mix are the primary levers for profitability. Cash generated is routinely redirected to fund growth bets and cover corporate overhead. The business functions as a classic cash cow within UPM’s portfolio.
Core pulp assets — UPM’s efficient mills continue to generate strong cash when cycles cool, driven by lower unit costs and long-term contracts that secure a high share of key customers’ sourced volumes.
Incremental debottlenecking initiatives in 2024 raised pulp yields and margins without heavy capital expenditure, improving free cash flow conversion for the segment.
Strategy: maintain capacity and optimize throughput rather than overbuild, preserving cash cow economics and margin resilience.
Standard plywood product lines operate through established channels with repeat contractors and predictable order cycles, delivering solid margins when plant utilization remains high. Growth is limited, so small targeted capex that improves yield and reduces downtime keeps efficiency ticking up. Strategy is to harvest cash while maintaining sharp service levels to protect recurring revenue.
Commodity sawn timber portfolios sit in a fragmented market, yet UPM’s vertically integrated forestry and supply chain lower delivered costs, enabling steady cash generation in normal seasons with minimal marketing. Targeted infrastructure tweaks—sawmill throughput upgrades and log-sorting automation—lift volumes and margins while the business is run lean and disciplined to protect cash flow.
Mature label substrates SKUs are high-volume, entrenched products delivering steady margins and throughput for UPM; the global pressure-sensitive label market was about 35 billion USD in 2024, underscoring stable demand. Minimal innovation is needed, so focus on flawless quality control and SKU rationalization to avoid margin dilution. Preserve manufacturing scale and avoid SKU creep.
Communication papers: mature, scale-leading cash generator with optimized mills and disciplined pricing sustaining steady free cash flow.
Core pulp: efficient mills and long-term contracts provide counter-cyclical cash in cooling cycles; 2024 debottlenecking improved yields.
Labels/wood products: high-volume, low-growth segments (label market ~35B USD in 2024) harvested for cash with targeted capex.
| Segment | Role | 2024 note | Strategy |
|---|---|---|---|
| Comm. papers/pulp/labels/wood | Cash cows | Stable CF; label mkt ~35B USD | Optimize throughput; selective capex |
The UPM‑Kymmene BCG Matrix you’re previewing is the exact file you’ll receive after purchase. No watermarks, no placeholders—just a fully formatted, ready‑to‑use strategic report. It’s editable, print‑ready, and built for presentation to boards or investors. Buy once, download instantly, and plug it straight into your planning process.
Legacy printing grades sit in Dogs: low growth and tougher pricing each year, with volumes and net prices slipping through 2024, making share no longer worth the operational complexity.
Low‑differentiation timber sold into oversupplied spots behaves as a commodity to fragmented buyers with little brand pull; spot lumber prices fell roughly 25% from the 2021–22 peaks into 2024, squeezing margins and amplifying volatile cycles. With operating margins compressed and share hard to win back without price cuts, UPM must trim exposure and redirect fiber toward higher‑value uses such as pulp and specialty papers.
Dogs: Generic plywood for price-only tenders drains UPM-Kymmene margins as race-to-the-bottom contracts deliver low single-digit operating profits in 2024 and erode strategic focus. No growth and no customer loyalty; buyers switch on price alone. Cash ties up in working capital as thin margins amplify receivables and inventory impact. Discontinue or migrate SKUs to value-added, spec-differentiated plywood to protect margin.
Small legacy composites show niche volumes and scarce scale benefits, where incremental development costs rarely pay back and operations struggle to reach break-even; often margins are negative and cash drag persists. Strategic action should favor divestment or orderly wind-down to free capital for scalable growth areas.
Non-core regional paper SKUs: tiny runs, complex logistics and minimal brand value yield low growth and market share while creating high managerial distraction and profit drag across the UPM network in 2024; prune aggressively to reallocate capacity and cut unit costs.
Legacy printing grades: low growth, volumes and net prices slipped through 2024, operational complexity no longer justified.
Spot timber/lumber down ~25% from 2021–22 peaks into 2024; margins compressed to low single-digit operating profits in 2024, require fiber redeployment to pulp/specialty paper.
Generic plywood and small composites: niche volumes, negative or near-break-even margins; divest or migrate to value-added SKUs.
| Segment | 2024 trend | 2024 margin | Action |
|---|---|---|---|
| Printing grades | declining | low | divest/migrate |
| Timber/lumber | price -25% | low single-digit | redirect fiber |
| Plywood/composites | no growth | negative/near BE | wind-down/divest |
Question Marks: biochemicals (bio-based glycols, lignin valorization) target high-growth packaging, textiles and resins with an estimated market CAGR ~8% (2024–2030) and >€5bn addressable market by 2030. UPM’s integrated fiber stream gives a feedstock cost and sustainability edge though commercial market share remains low (<5%). Capital intensity and lengthy customer qualification cycles are key hurdles. Invest with tight milestones—potential Star if scale and offtakes hit.
Next‑gen fiber composites sit in Question Marks: auto and consumer OEMs demand lighter, greener materials—automotive lightweighting targets often exceed 10% per component—yet UPM’s advanced fiber share remains small versus thermoplastics. Technology shows promise; global natural fiber composites market was ~USD 6.8bn in 2024 with ~7% CAGR. Success requires partnerships and pilot‑to‑plant scaling. Back winners fast, cut slow movers quickly.
Policy tailwinds are strong: RED III set the EU 2030 renewables target at 42.5%, boosting mandates for advanced biofuels and enabling rapid offtake scaling in transport and aviation.
UPM’s wood-based credentials lend credibility, but existing advanced-biofuel capacity lags demand, requiring multi-hundred-million-euro capital outlays per large plant (roughly €400–800m) and major supply-chain builds.
Focus deployment where sustainable feedstock availability and supportive national policies align to secure anchored offtake and achieve scale economics.
Question Marks: Functional barrier papers replacing plastics — brand owners are actively testing barrier papers and if industrial-scale barriers meet food-safety and shelf-life specs, volumes could surge; early commercial specs landed in 2024 but UPM’s share remains modest (~2% of packaging segment in 2024). Success requires continued R&D, converter partnerships and line trials; invest to lock key accounts before copycats scale.
Digital mill services and data-driven offerings (smart maintenance, traceability, customer portals) are growthy but remain nascent for UPM, showing low share versus digital natives and incumbent equipment suppliers.
They require focused product integrations, a clear monetization model and commercial pilots with anchor customers before scaling across mill network.
Question Marks: biochemicals, next‑gen fiber composites, barrier papers and digital mill services show high growth potential but low 2024 shares (UPM bio <5%, barrier papers ~2%). Markets: bio glycols/lignin CAGR ~8% (2024–2030), natural fiber comps USD 6.8bn (2024). Key needs: scale, anchor offtakes, R&D and multi‑€100m capex (€400–800m per large plant).
| Tag | 2024 metric | Key need |
|---|---|---|
| Biochemicals | CAGR ~8% / >€5bn by 2030; UPM <5% | Scale & anchored offtakes |
| Composites | Market USD 6.8bn; CAGR ~7% | OEM partnerships |
| Barrier papers | UPM ~2% packaging (2024) | R&D & line trials |


