
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Varun Beverages shows strong franchise partnerships, distribution scale and revenue growth but faces commodity, regulatory and concentration risks; our concise SWOT highlights these trade-offs and growth levers. Want the full strategic picture with actionable recommendations, financial context, and editable deliverables? Purchase the complete SWOT analysis to plan, pitch, or invest with confidence.
Exclusive PepsiCo franchise rights across 27 Indian states and 13 international markets create a protected demand funnel and predictable offtake; Varun Beverages reported consolidated FY2024 revenue of around INR 79,600 million, which underpins scale-driven bargaining power with suppliers and retail channels. Alignment with PepsiCo’s marketing and innovation engine sustains brand pull, while territory consolidation enhances route-to-market efficiency and lowers distribution costs.
Extensive last-mile network across urban and rural markets—Varun Beverages, the second-largest PepsiCo bottler globally by volume, leverages a wide distributor footprint to boost product availability and storefront visibility.
Strong season execution with over 400,000 branded coolers and chillers in-market drives higher share of premium cold sales during peak months.
High route density lowers per-unit logistics cost and improves service levels, while deep retail relationships enable rapid rollouts of new SKUs and promotions.
Varun Beverages leverages a diversified CSD and NCB portfolio across 27 countries, tempering category cyclicality by mixing carbonated drinks with water, juices and sports drinks. Multiple price points and pack sizes target value and premium cohorts, boosting penetration in urban and rural channels. Broad portfolio enables cross-merchandising and larger shelf share, while steady innovation cadence strengthens defenses versus local players.
In-house preforms, crowns and syrup handling tighten quality and lower per-unit costs, while high-speed lines and network optimization boost asset turns and throughput; Varun Beverages reported continued capacity-led volume growth in FY2024, supporting margin resilience.
Clustered plants reduce freight and response time across regions, and data-led planning improved demand forecasting and inventory discipline in 2024, cutting stock-outs and working capital needs.
Geographic diversification: Varun Beverages operates across India and select international markets such as Nepal, Sri Lanka, Morocco, Zambia, Mozambique and Ethiopia, spreading operational risk and smoothing seasonal demand across differing climate and festival calendars. Currency and macro exposures from these markets diversify revenue streams while allowing cross-market learnings to raise execution standards and efficiencies.
Exclusive PepsiCo franchise across 27 Indian states and 13 international markets drives predictable offtake; FY2024 consolidated revenue INR 79,600 million and #2 global PepsiCo bottler scale support supplier and channel leverage. 400,000 branded coolers, in‑house inputs and clustered plants lower per‑unit costs and boost distribution density; data-led planning improved forecasts and working capital in 2024.
| Metric | Value |
|---|---|
| FY2024 revenue | INR 79,600 mn |
| Branded coolers | 400,000+ |
| Territories | 27 states | 13 international markets |
| PepsiCo rank | 2nd largest bottler (by volume) |
 Detailed Word Document
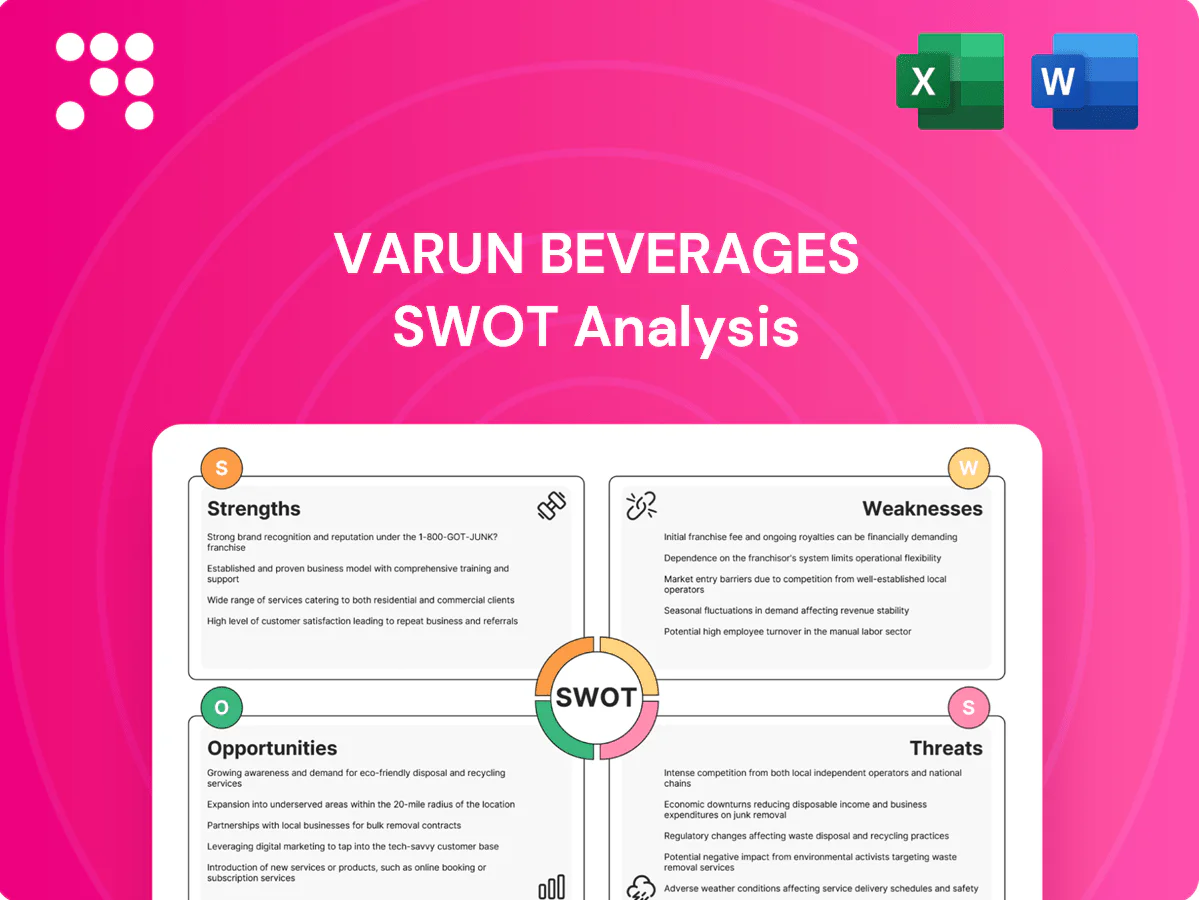
Delivers a strategic overview of Varun Beverages’s internal and external business factors, highlighting market strengths, operational gaps, growth drivers, and the key opportunities and threats shaping its competitive position.

 Customizable Excel Spreadsheet
Provides a concise SWOT matrix highlighting Varun Beverages' strengths, weaknesses, opportunities and threats for fast strategic alignment and focused risk mitigation.
High dependence on PepsiCo concentrates strategic and contractual risk for Varun Beverages, making the company vulnerable if PepsiCo alters branding, pricing, territory allocations or concentrate supply terms. Royalty and concentrate pricing directly squeeze bottler margins and any adverse change would materially affect profitability. Renewal, compliance or exclusivity disputes could disrupt continuity of operations and cash flows.
Varun Beverages remains heavily exposed to carbonated soft drinks, leaving it vulnerable to health-driven shifts toward low/no-sugar options which tend to hit urban and premium channels first. Reformulating recipes and retooling supply chains requires multi-quarter investment and R&D spend, slowing transition. Scaling margin-accretive NCBs needs sustained marketing and trade support to offset legacy CSD volumes.
Peak summer drives disproportionate sales for Varun Beverages, stressing production capacity and working capital as the company rushes to meet summer demand. Weather volatility can quickly derail forecasts and inventory plans. Off-season under-utilization reduces fixed-cost absorption, squeezing margins. Promotional intensity rises in shoulder quarters to maintain throughput and smooth factory utilization.
Beverage plants, new filling lines, coolers and expanded logistics require continuous, front-loaded capex as Varun scales territories, making cash outflows peak before routes mature. Payback timing hinges on route maturation and cooler productivity; slow uptake delays breakeven. High depreciation during expansion phases can materially compress reported returns despite underlying cash generation.
Varun Beverages' heavy reliance on groundwater creates operational and reputational risk, as local shortages or permit constraints can directly reduce bottling capacity and disrupt supply to key markets. Rising ESG expectations force ongoing capital spending on replenishment projects and efficiency upgrades, while any contamination or permit breach can trigger strong community and regulatory backlash.
High dependence on PepsiCo concentrates and royalties concentrates contractual risk and margin pressure, exposing Varun to supply/pricing shifts and renewal disputes. Heavy CSD mix slows transition to low/no-sugar NCBs, requiring multi-quarter marketing and capex. Seasonal summer skew stresses capacity, working capital and increases promotional intensity. Groundwater reliance raises operational and ESG capex risks.
| Metric | Implication |
|---|---|
| PepsiCo dependence | Strategic/contract risk |
| CSD share | Limits NCB shift |
| Seasonality | Capacity & WC strain |
| Water use | ESG & permit risk |
This is the actual Varun Beverages SWOT analysis document you’ll receive upon purchase—no surprises, just professional, structured, editable content. The preview below is taken directly from the full report and reflects strengths, weaknesses, opportunities and threats analyzed with financial and market context. Purchase unlocks the complete, downloadable file immediately.
Acquiring additional PepsiCo territories can unlock scale benefits and synergies, helping Varun Beverages leverage purchasing power and shared logistics to improve margins. White-space states and cross-border adjacencies in South Asia and Africa remain attractive for expansion given rising beverage demand. Faster integration playbooks — proven in recent inorganic moves — shorten ramp-up periods and accelerate payback. Higher route density drives margin expansion through lower per-unit distribution costs.
Sleek cans and energy/functional-hydration SKUs support premiumization, lifting mix and margins across Varun Beverages diverse portfolio. Affordable small packs deepen rural and impulse reach while protecting entry price points. Occasion-led multipacks drive at-home consumption growth. Data-led revenue management optimizes price-pack across channels; Varun operates in 47 countries, aiding scale.
Health-aware consumers drive demand for low/no-sugar and functional SKUs; India bottled-water market was ~$6.3bn in 2023 and ready for premium/isotonic uptrends. Tropicana and Gatorade extensions offer scale—Gatorade ~$5.1bn and Tropicana ~$3.3bn in recent global sales—enabling Varun to capture share. Innovation in low-cal, vitamin-fortified and isotonic SKUs widens the funnel and supports higher ASPs. Vending and modern trade expansion lift trial and repeat rates.
Expanding chillers and last-mile partners lets Varun Beverages tap semi-urban and rural demand where around 64% of India’s population resides (World Bank 2023). Festival and micro-market activations build repeat purchase habits, while better cooler productivity raises throughput per outlet and digital ordering cuts stock-outs and improves availability.
Operational excellence and sustainability initiatives—water reuse and replenishment, energy-efficiency measures, PET light-weighting and increased recycled content—can materially lower variable and material costs while reducing regulatory and licensing risks for Varun Beverages.
Improved route-to-market through network-optimization algorithms raises load factors and service levels, cutting logistics cost per case and carbon intensity across the supply chain.
Stronger ESG metrics from these actions can broaden appeal to institutional investors focused on sustainability-linked mandates and lower the companys cost of capital.
Acquisition of PepsiCo territories and white-space expansion in South Asia/Africa can scale margins; Varun operates in 47 countries. Premium cans, energy/functional SKUs and low/no-sugar extensions (Tropicana/Gatorade scale) support mix uplift. Rural/chiller push targets ~64% of India population. ESG and network-optimization cut costs and attract capital.
| Opportunity | Metric | Value |
|---|---|---|
| Geography | Countries | 47 |
| Rural reach | India rural pop | 64% (World Bank 2023) |
| Bottled water | India market | $6.3bn (2023) |
Sugar taxes can cut demand—WHO estimates a 20% SSB tax reduces consumption by about 20%—while India's 18% GST on aerated beverages raises consumer prices and can squeeze lower affordability tiers. The 2022 central single-use plastic phase‑out (19 items) and state plastic rules add packaging costs and supply changes. Groundwater extraction curbs in water‑stressed states may limit capacity, and compliance lapses risk fines and reputational damage.
Rival Coca-Cola bottlers and nimble local brands squeeze Varun Beverages on pricing and shelf space, with Coca-Cola and PepsiCo together holding roughly 60% of the global CSD market in 2023–24. Heavy above-the-line spends by incumbents push up customer-acquisition costs and require matching marketing outlays. Rising private-label water and juice offerings are compressing margins, while channel conflicts surface increasingly in modern trade.
PET resin (~$1,100–1,300/t in 2024), raw sugar (~$0.20/lb), diesel (~$80–90/bbl crude-driven fuel) and LME aluminium (~$2,300/t) volatility materially raises Varun Beverages input costs. Limited pass-through on value packs compresses margins, particularly in price-sensitive Indian markets. Cross-border revenues expose the firm to INR, PKR and AFR currency swings, and hedging programs blunt but do not eliminate this risk.
Heatwaves raise short-term beverage demand but increase cooler failures and supply-chain stress; IPCC AR6 (2023) links rising extreme heat to more frequent operational disruptions. Unseasonal rains can wipe out peak-season volumes and promotional plans, while water-stressed regions (WRI flagged India among high-risk areas) elevate production risk. Infrastructure disruptions push logistics costs higher, squeezing margins.
PepsiCo’s shifts in concentrate pricing, portfolio priorities or route-to-market can materially alter Varun Beverages’ margins and working capital dynamics, while contract renewals introduce terms risk that may compress profitability; portfolio rationalization at PepsiCo could cut SKU breadth and reduce distribution leverage, and any global brand issue can quickly cascade into weaker local volumes and pricing power.
Varun faces demand hits from sugar taxes (WHO: 20% tax → ~20% cut) and India's 18% GST, rising packaging and water-compliance costs. Strong incumbents (Coca‑Cola + PepsiCo ≈60% global CSD share) and private labels pressure pricing and shelf space. Input volatility (PET $1,100–1,300/t; aluminium $2,300/t) and FX swings compress margins.
| Threat | Key metric |
|---|---|
| Sugar tax | 20%→20% vol |
| Market share | ~60% incumbents |
| PET | $1,100–1,300/t (2024) |


