
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Victory Capital’s SWOT reveals a firm with diversified asset capabilities and strong distribution, counterbalanced by fee pressures and sector concentration risks; our concise preview highlights key opportunities in product expansion and integration. Purchase the full SWOT to access a research-backed, editable report and Excel matrix for strategic planning and investment decisions.
Victory Capital’s multi-boutique model (16 boutiques, NASDAQ: VCTR) empowers autonomous investment teams to generate differentiated alpha and lower strategy correlation through independent decision-making. Governance combines boutique autonomy with centralized risk, compliance and distribution oversight to limit operational drift. The structure enables rapid launch and bolt-on of niche strategies, while clients gain specialist boutique expertise backed by parent-scale resources.
Victory Capital's diverse lineup spans active equity, fixed income and alternatives, supporting varied risk/return needs and contributing to more resilient fee streams across cycles; the firm reported AUM of $163.1 billion as of 6/30/2024. Its multi-asset solutions and model portfolios enable platform integration and turnkey advice, while the breadth lets management shift distribution emphasis rapidly as investor demand rotates between equities, bonds and alternatives.
Victory Capital leverages scaled distribution across institutions, intermediaries and retirement platforms, supporting over $150 billion in AUM and broad market access. Wholesaling, consultant relationships and platform placements expand the addressable market and drive flow. Cross-selling into existing advisor and institutional relationships increases product penetration. Robust compliance, operations and client-service infrastructure support scalable growth.
Victory Capital aligns incentives for autonomous boutiques around long-term performance, reinforcing repeatable investment processes and centralized risk controls that support steady outcomes and portability of boutique track records; the firm reported approximately $175 billion in AUM in 2024, underpinning strong brand equity across its franchises.
Consistent multi-year performance has driven superior retention and pricing power versus peers, allowing boutiques to command higher fees and retain talent through performance-linked compensation and clear governance.
Victory Capital leverages a centralized tech, data, trading and compliance platform that lowers unit costs and – with reported AUM near $166B (mid‑2024) – delivers margin leverage as shared services scale across boutiques; the unified infrastructure eases integration of acquisitions and enhances client reporting and transparency through consolidated data feeds and standardized performance attribution.
Victory Capital’s 16-boutique model (NASDAQ: VCTR) drives differentiated alpha, centralized risk/compliance and rapid strategy launch; reported AUM $166B as of 6/30/2024. Diversified product mix (equity, fixed income, alternatives) and scaled distribution underpin resilient fee streams and pricing power. Centralized tech and shared services yield margin leverage and faster integration of acquisitions.
| Metric | Value |
|---|---|
| Boutiques | 16 |
| AUM (6/30/2024) | $166B |
| Channels | Institutions, Intermediaries, Retirement |
| Key strengths | Alpha, Margin leverage, Pricing power |
 Detailed Word Document
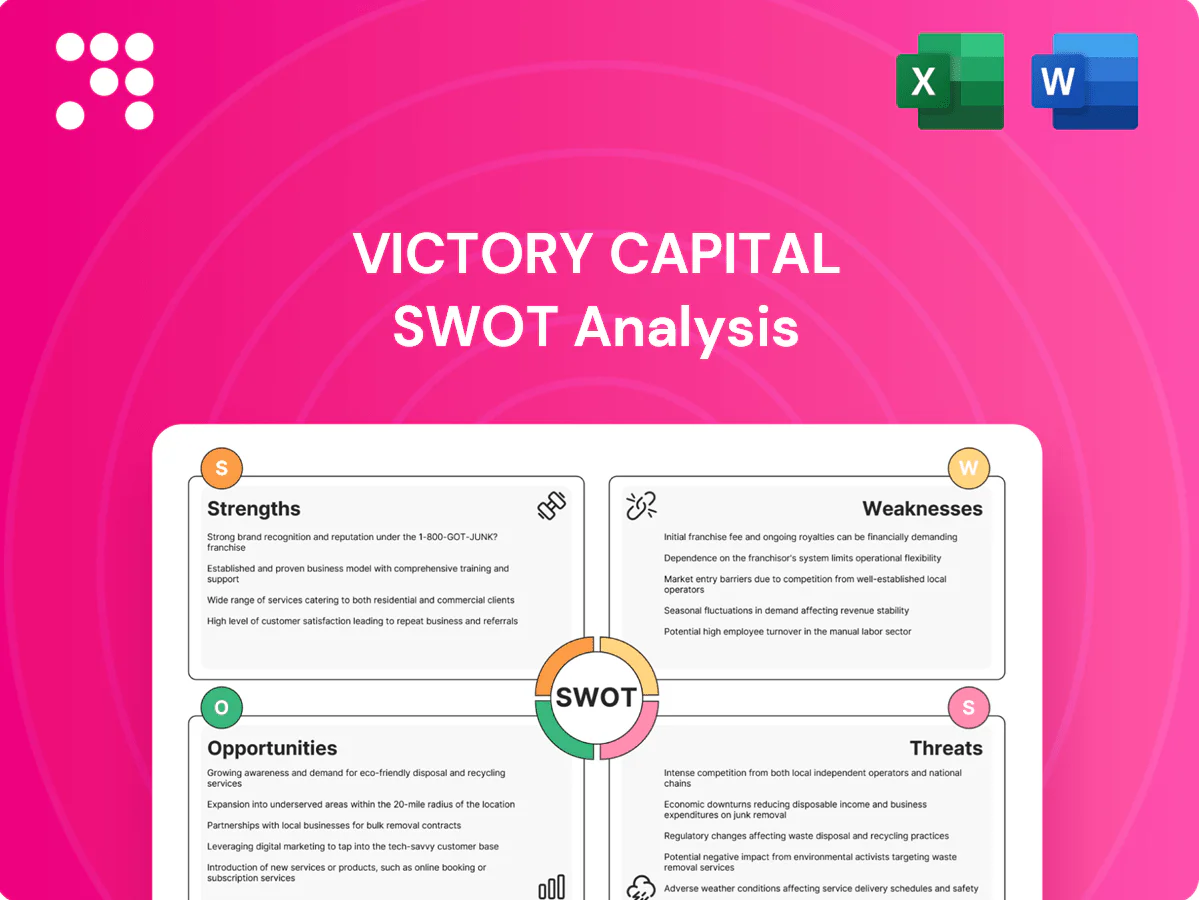
Provides a concise SWOT analysis of Victory Capital, outlining its core strengths and weaknesses while mapping market opportunities and external threats to assess strategic positioning and growth prospects.

 Customizable Excel Spreadsheet
Provides a concise, high-level SWOT of Victory Capital for fast strategic alignment and stakeholder updates; editable format enables quick edits to reflect market shifts and streamline decision-making.
Victory Capital's reliance on active management amid industry fee compression is acute: passive funds surpassed 50% of U.S. fund assets in 2023, forcing fee pressure versus low-cost peers. With AUM of roughly $165bn in 2024, management has limited room to cut fees without squeezing margins. The firm must justify fees via sustained outperformance, or risk distribution loss on large platforms that favor cheaper products.
Boutique autonomy can produce performance dispersion across Victory Capital’s teams, where underperformance in a few strategies has historically triggered client outflows and weakened brand perception. Capacity constraints in high-alpha sleeves limit scalability and can force capacity closures that crystallize track-record gaps. This structure raises the monitoring burden on central risk and compliance to enforce consistency and risk discipline across disparate boutique units.
Reliance on lead portfolio managers and tightly knit boutique teams creates material key-person risk for Victory Capital, where departures can trigger client redemptions and performance drift. Talent attrition or poaching by larger firms can rapidly shrink revenue-generating AUM and disrupt track records that drive flows. Retention requires elevated economics and equity awards that compress margins, while several specialist strategies exhibit succession-planning gaps that heighten operational vulnerability.
Growth at Victory Capital is frequently driven by M&A and team lift-outs, with the firm managing over $150 billion in AUM as of 2024, making inorganic deals central to revenue expansion. Integration poses complexity across IT systems, culture, and compliance, while earn-outs and contingent compensation can trigger future expense spikes and distract management bandwidth.
Victory Capital's brand and marketing scale lag global mega-managers (BlackRock ~10 trillion AUM and Vanguard ~8.6 trillion AUM in 2024), constraining visibility in consultant-led, large institutional RFPs where scale and brand parity matter. This limits share-of-wallet with wirehouses and retirement recordkeepers and raises client-concentration risk in certain channels where a few relationships drive disproportionate revenue.
Victory Capital faces acute fee pressure as passive funds exceeded 50% of U.S. fund assets in 2023, limiting margin flexibility with ~165bn AUM in 2024. Boutique structure causes performance dispersion and key-person risk that has driven episodic outflows. Acquisition-driven growth adds integration, earn-out expense and management bandwidth strain.
| Metric | Value |
|---|---|
| AUM (2024) | $165bn |
| Passive market share (2023) | >50% |
| Top mega-manager AUM (2024) | BlackRock $10tn, Vanguard $8.6tn |
This is the actual Victory Capital SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report you'll get; purchase unlocks the entire in-depth, editable version. You’re viewing a live excerpt of the real file, structured and ready to use immediately after checkout.
Expanding into private credit, real assets and hedge-like strategies taps markets where private credit exceeded $1 trillion globally in 2024 (Preqin) and hedge AUM was roughly $4.5 trillion, offering yield and diversification for Victory Capital.
Semi-liquid and interval fund formats enable retail/intermediary access while preserving liquidity controls, matching demand for higher-yield alternatives.
Victory can seed teams or acquire niche managers to scale offerings, capturing higher-fee, stickier AUM and improving fee margin profiles.
Launching active ETFs and tax-efficient SMAs/direct indexing lets Victory Capital convert its active strategies into wrapper-friendly formats, tapping a global ETF market that topped about $12.6 trillion in assets in 2024.
Portability of existing mutual fund and model strategies into ETFs/SMAs accelerates product rollout and leverages operational scale, with model portfolio adoption on major RIA/wealth platforms driving measurable flows into managed-wrapper solutions.
Cross-selling to advisors seeking low-friction implementation—via turnkey SMAs, model marketplaces and ETF share classes—can boost advisory penetration and recurring fee income while improving retention.
Victory Capital can scale target-date funds, managed accounts and model delivery into 401(k)/IRA channels, leveraging its $147.8 billion AUM (6/30/2024) to capture steady DC flows and recurring contributions that underpin long-term fee revenue. White-label and subadvisory deals with recordkeepers expand distribution and margins, while regulatory nudges toward fiduciary advice favor model-based, scalable solutions favored by plan sponsors and advisors.
Extending UCITS and institutional mandates across EMEA and APAC lets Victory Capital scale US credit, equity income, and quality-factor strategies for global allocators, leveraging consultant relationships and local distributor partnerships to win mandates and feeder vehicles.
Applying AI/NLP, alternative data and systematic overlays can augment Victory Capital’s discretionary teams by accelerating idea generation, enhancing risk signals and automating client reporting, enabling material efficiency gains in research, risk management and RFP responses. This setup can scale capacity without proportional headcount and provide a clear differentiation in marketing and consultant due diligence.
Expand into private credit, real assets, hedge-like strategies and active ETF/SMAs to capture higher-fee, sticky flows as private credit topped $1T (2024) and global ETFs reached $12.6T (2024). Use semi-liquid funds, white-label/subadvisory and UCITS rails to scale EMEA/APAC institutional distribution. Leverage AI/alt-data to boost research efficiency and advisor cross-sell, converting $147.8B AUM (6/30/2024) into recurring fee growth.
| Opportunity | 2024/2025 Data |
|---|---|
| Private credit | >$1T (2024, Preqin) |
| Global ETFs | $12.6T (2024) |
| Hedge AUM | ~$4.5T (2024) |
| Victory AUM | $147.8B (6/30/2024) |
Equity drawdowns (S&P 500 peak-to-trough ~24% in 2022) and rate shocks (policy rate ~5.25–5.50% in 2024) can cut AUM, depress performance and fees, while rapid style rotations whipsaw boutique strategies. Liquidity stress in credit and alts — visible in widened corporate spreads and episodic CLO dislocation — hampers execution. Procyclical client flows amplify revenue swings via concentrated outflows during downturns.
Index and smart‑beta strategies continue gaining share versus active managers, with global ETF AUM topping roughly $11.4 trillion in 2024 and sustained strong inflows into passive products that undercut active fees.
Major platform gatekeepers increasingly favor lower‑cost ETFs and model portfolios, pressuring distribution for higher‑fee active strategies and risking fee wars that compress management margins.
Rising operating costs and IT/security investments make it difficult for Victory Capital to pass costs through without further margin dilution or product repricing.
Evolving SEC rules—notably the marketing rule adopted Dec 13, 2023—alongside tighter guidance on liquidity, derivatives and fiduciary standards increase compliance complexity for Victory Capital. Higher reporting and surveillance requirements raise fixed costs and operational headcount. Distribution constraints and intensified share-class scrutiny limit product placement and fee structures. Lapses expose the firm to regulatory fines and material reputational damage.
Data breaches, vendor failures and trade errors can trigger direct losses and client attrition; the average cost of a data breach was about $4.45 million (IBM, 2023), and remediation often strains limits of cyber insurance. Third-party dependencies across administrators, custodians and data providers amplify exposure as attacks on financial firms grow more sophisticated.
Victory Capital faces an intense market for portfolio managers, analysts and quant/data talent, with asset-manager compensation budgets rising about 10% in 2024 and senior PM packages frequently exceeding $500k total pay; upward pressure on base pay and retention bonuses erodes margins and raises client fee sensitivity. Competitors regularly pursue team lift-outs, driving turnover risk, while hiring shortfalls or poor integration can strain culture and impair performance continuity.
Active managers face margin squeeze from passive flows, cyber risk, and rising compensation
Market shocks (S&P -24% in 2022; fed funds ~5.25–5.50% in 2024) and rapid style rotations can cut AUM and fees; passive share growth (global ETF AUM ~$11.4T in 2024) pressures active revenue. Cyber/third‑party failures risk ~ $4.45M breach costs (IBM 2023) and reputational loss. Talent costs (+~10% budget in 2024; senior pay often >$500k) raise margins risk.
| Risk | Metric |
|---|---|
| Passive share | $11.4T ETF AUM (2024) |
| Interest rate | 5.25–5.50% (2024) |
| Cyber cost | $4.45M avg breach (2023) |
| Comp | +10% budget (2024); senior >$500k |


