
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Vecima's SWOT snapshot highlights strong niche tech capabilities and recurring revenue from cable and wireless solutions, offset by supply-chain pressures and competitive market dynamics; strategic partnerships and product diversification are clear growth levers. Purchase the full SWOT analysis to receive a research-backed, editable Word and Excel package for actionable planning and investor-ready presentations.
Vecima's end-to-end broadband portfolio spans access, video and content delivery, letting operators source integrated solutions and cut vendor sprawl. Cross-portfolio interoperability accelerates complex network upgrades and supports multi-technology roadmaps across cable, fiber and wireless. Vecima is listed on the Toronto Stock Exchange (VCM).
Vecima Networks Inc. (TSX: VCM), headquartered in Victoria, British Columbia, designs carrier-grade video, data and voice systems at scale, leveraging deep cable and IP video domain expertise to align with operator roadmaps; this operator-focused engineering shortens time-to-value in field deployments and upgrades and materially increases likelihood of renewals and contract expansions.
Complementing Vecima hardware with software and services creates recurring revenue potential through subscriptions and managed services, improving gross margins compared with hardware-alone sales. Analytics, control software and CDN layers typically yield higher margin mix and help stabilize revenue across hardware cycles. This platform approach increases customer lock-in and platform stickiness, raising lifetime value and reducing churn.
In-house design and manufacturing gives Vecima tighter quality control and greater product customization, enabling faster iterations as DOCSIS and video access standards evolve; this agility is critical where specs shift quickly and OEM cycles lag. Verticalization also helps mitigate supply-chain disruptions and component-cost variability, shortening time-to-market for firmware and hardware updates.
Contigo IoT extends Vecima beyond broadband operators into fleet management and asset tracking, leveraging Vecima’s 2021 Contigo acquisition to add SaaS-style recurring revenue and diversify cash flows. Cross-selling telematics into existing operator and enterprise relationships supports higher customer lifetime value, while positioning Vecima in an IoT market expected to reach about 29.4 billion connected devices by 2025.
Vecima Networks (TSX: VCM) offers end-to-end broadband access, video and CDN solutions enabling integrated operator upgrades and reduced vendor sprawl. In-house hardware, software and services drive recurring revenue and faster iterations to DOCSIS/IP standards. 2021 Contigo add-on diversifies into IoT/SaaS; IoT market ~29.4B devices by 2025.
| Strength | Evidence |
|---|---|
| Integrated portfolio | Operator-grade access, video, CDN; TSX: VCM |
| Recurring revenue | Software, managed services, Contigo SaaS |
| IoT diversification | Contigo acquisition 2021; IoT ~29.4B devices by 2025 |
 Detailed Word Document
Delivers a strategic overview of Vecima’s internal and external business factors, outlining strengths, weaknesses, opportunities, and threats to assess its competitive position and future risks.

 Customizable Excel Spreadsheet
Provides a concise Vecima SWOT matrix that relieves strategic ambiguity, enabling fast alignment on strengths in broadband and content-delivery tech while quickly surfacing competitive, regulatory, and execution risks for clear decision-making.
Spending by cable and fiber operators is cyclical and budget-driven, with Comcast and Charter together investing just over $20 billion in capex across 2023–2024, so slowdowns or deferrals can materially cut Vecima orders. Such timing shifts create marked quarterly revenue volatility for supplier firms. Forecasting becomes notably harder during macro or regulatory shifts as operator budgets swing.
Large operators often account for outsized revenue shares for equipment suppliers; mega-buyers such as Comcast and Charter together controlled roughly 60% of US broadband subscribers in 2024, concentrating demand and bargaining power.
Loss or delivery delays from one key account can disproportionately hit quarterly results, magnifying working capital and revenue volatility.
Negotiating leverage favors mega-buyers and can compress pricing and gross margins over time, pressuring supplier profitability.
Smaller scale leaves Vecima vulnerable as global competitors like Cisco, Nokia and Huawei—each investing billions in R&D (Cisco >$5B, Nokia >€3B in recent years)—can outspend on product development and sales coverage. These rivals bundle end-to-end solutions to win share, constraining Vecima’s pricing flexibility and channel reach. Limited scale also raises qualification barriers for massive nationwide programs that favor suppliers with proven global delivery and balance-sheet depth.
Access equipment faces commoditization and BOM cost swings that compress hardware margins, with differentiation increasingly shifting to software value and recurring services. Currency and component inflation continue to squeeze gross margins, forcing Vecima to rely more on software licensing and services revenue mix. Sustained pressure requires tight cost control, SKU mix management and faster software monetization to protect profitability.
Vecima serves five segments — cable, fiber, wireless, CDN and IoT — giving breadth but creating integration and support complexity that can strain engineering and field teams. Overlapping products increase risk of internal cannibalization and make roadmap prioritization across segments more challenging for management. Publicly listed as VCM on TSX, coordination costs can pressure margins.
Revenue volatility from cyclical operator capex (Comcast+Charter >$20B capex 2023–24) and ~60% US broadband share concentrates demand and bargaining power, pressuring pricing and margins. Scale gap vs Cisco (R&D >$5B) and Nokia (>€3B) limits bids for national programs. Five-segment breadth strains engineering and risks internal cannibalization.
| Risk | Metric |
|---|---|
| Buyer concentration | ~60% US subs (2024) |
| Operator capex | >$20B (Comcast+Charter 2023–24) |
| Competitor R&D | Cisco >$5B, Nokia >€3B |
| Segments | 5 (support strain) |
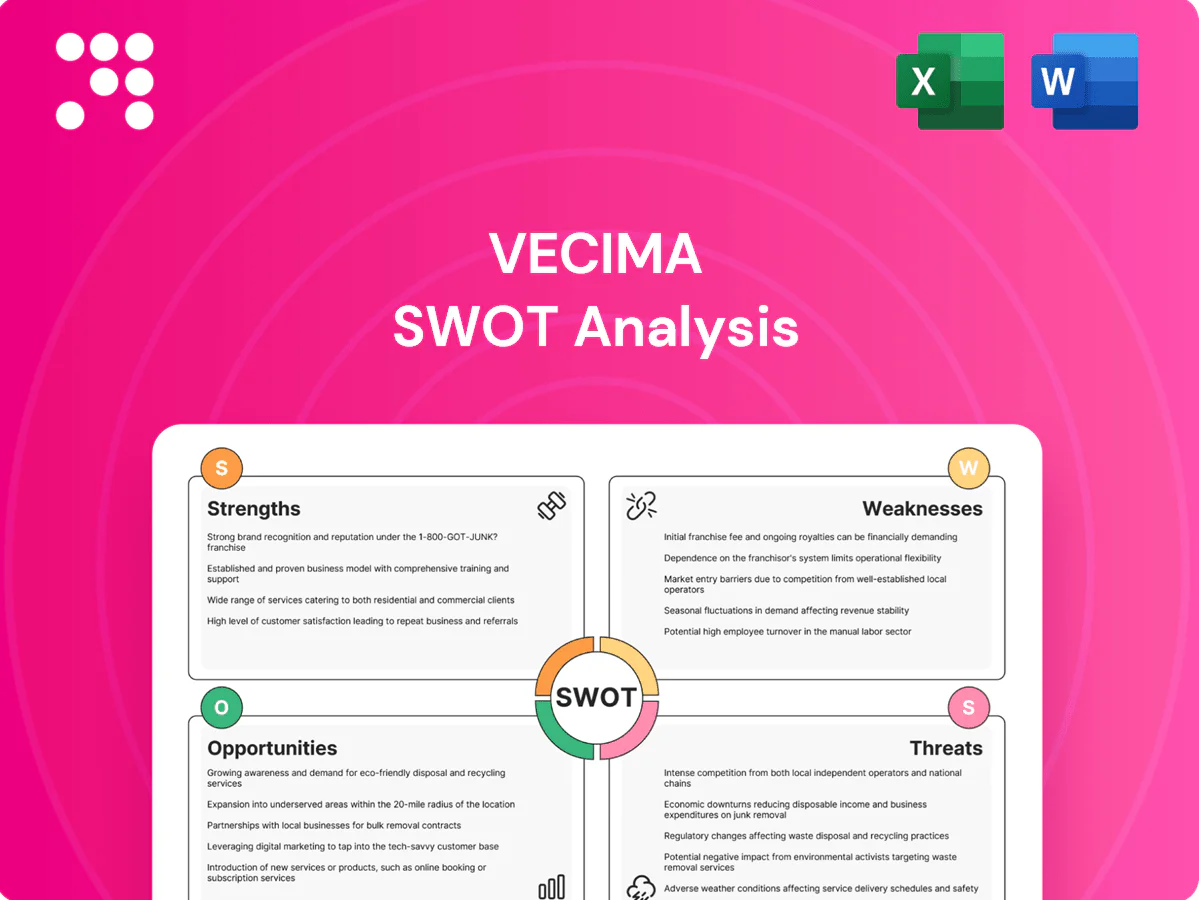
This preview of the Vecima SWOT Analysis is the actual document you’ll receive after purchase — no samples or placeholders. It presents a professional, structured assessment with strengths, weaknesses, opportunities and threats exactly as in the full file. Purchase unlocks the complete, editable report for immediate download and use. Buy now to access the entire in-depth analysis.
Major operators including Comcast and Charter are accelerating 10G rollouts via DOCSIS evolution, DAA and fiber builds, maintaining multi-year upgrade roadmaps and sustaining demand into 2026–2028. Vecima can supply edge, access and management components across DOCSIS, DAA and FTTx stacks. Multi-year upgrade waves and operator capex in the billions annually create recurring revenue opportunities. Early design wins can lock in follow-on orders and network lifecycle services.
Streaming now drives roughly 75% of downstream IP traffic in 2024, forcing operators to scale video delivery rapidly. Edge caching and CDN software can cut latency by 30–70% and lower transit costs by up to 40%, favoring vendors with integrated content-delivery stacks. For Vecima this trend supports higher-margin box-plus-software deals and recurring software licensing revenue expansion in 2024–25.
Public subsidies such as the US BEAD program with $42.45 billion and Canada’s Universal Broadband Fund (~CAD 1.75 billion) aim to close the digital divide in rural and underserved regions. Funded builds accelerate access equipment procurement timelines, reducing sales cycles and enabling larger, bundled contracts. Vecima can align product specs and pricing to program eligibility, increasing win rates. Faster rural deployments materially expand Vecima’s addressable market and recurring revenue potential.
Rising SME and enterprise adoption of fleet and asset tracking drives demand; the global fleet management market was estimated at US$35 billion in 2024 with ~14% CAGR forecast to 2030, allowing Contigo to upsell analytics, compliance and integration modules to increase customer lifetime value.
Advanced network analytics, automation, and embedded security layers can meaningfully lift Vecima's margins by shifting value from hardware to higher-margin software and services. Expanding SaaS and long-term support contracts stabilizes recurring revenue and reduces revenue cyclicality tied to hardware refreshes. Open APIs and partner ecosystems increase customer stickiness and create clear upsell paths into managed services and analytics.
Operators' multi-year 10G/DOCSIS/FTTx rollouts and BEAD/CUB funding (US$42.45B; CAD~1.75B) create recurring hardware+software demand through 2026–28. Streaming (~75% downstream IP traffic in 2024) and edge CDN needs favor higher-margin software and caching deals. Fleet market (~US$35B in 2024; ~14% CAGR) supports Contigo upsell to analytics and compliance.
| Opportunity | 2024–25 Metric |
|---|---|
| Public funding | US$42.45B (BEAD) |
| Streaming traffic | ~75% downstream IP |
| Fleet market | US$35B; ~14% CAGR |
Large incumbents and specialized challengers pressure Vecima on price and features, while bundling and aggressive discounting by tier-1 vendors can erode share. Procurement frameworks and enterprise contracts often favor scaled suppliers, limiting Vecima’s win rates. Switching costs remain moderate where open standards prevail, enabling customers to migrate if integrated solutions underperform.
Frequent shifts in DOCSIS, DAA, PON and streaming protocols create a threat where missing a standards turn risks product obsolescence; CableLabs approved DOCSIS 4.0 in 2022, highlighting ongoing change. R&D missteps can lengthen sales cycles and increase time-to-revenue, while customers often delay purchases awaiting standards clarity, compressing near-term order visibility.
Semiconductor shortages and logistics bottlenecks can delay Vecima deliveries, mirroring industry impacts such as IHS Markit’s estimate of 3.9 million fewer vehicles produced in 2021 due to chip shortages. Lead-time volatility complicates revenue recognition and cash flow planning across quarters. Currency swings and freight volatility—container spot rates peaked near 20,000 USD per FEU in 2021—compress margins. Quality failures can force remediation and recalls that cost millions in rework and lost sales.
Network and IoT solutions expand Vecima's attack surface as IoT devices are projected at 30.9 billion by 2025 (Statista), increasing breach probability; the average cost of a data breach was $4.45M in 2024 (IBM).
Prolonged outages or breaches can erode reputation and revenue, compliance costs rise under rules like EU DORA, and cyber insurers have pushed premiums roughly 30–40% (Marsh 2024), tightening coverage.
Macroeconomic slowdown: recessions lead operators to defer capex and renegotiate contracts, while higher rates (US federal funds ~5.25–5.50% in 2024–25) raise hurdle rates for network upgrades; SME customers may churn from IoT subscriptions as budgets tighten and demand softness amplifies pricing pressure.
Large incumbents, bundling and procurement bias toward scaled suppliers compress Vecima’s pricing and win rates; modular standards and moderate switching costs enable customer churn. Standards shifts (DOCSIS/DAA/PON) and semiconductor/logistics volatility lengthen sales cycles and raise costs. Rising cyber risk (30.9B IoT devices by 2025) and regulatory/insurance cost inflation further pressure margins.
| Metric | Value |
|---|---|
| IoT devices (2025) | 30.9B (Statista) |
| Avg breach cost (2024) | $4.45M (IBM) |
| Fed funds (2024–25) | 5.25–5.50% |
| Cyber premiums (2024) | +30–40% (Marsh) |


