
Digital download
Access the files immediately after checkout.
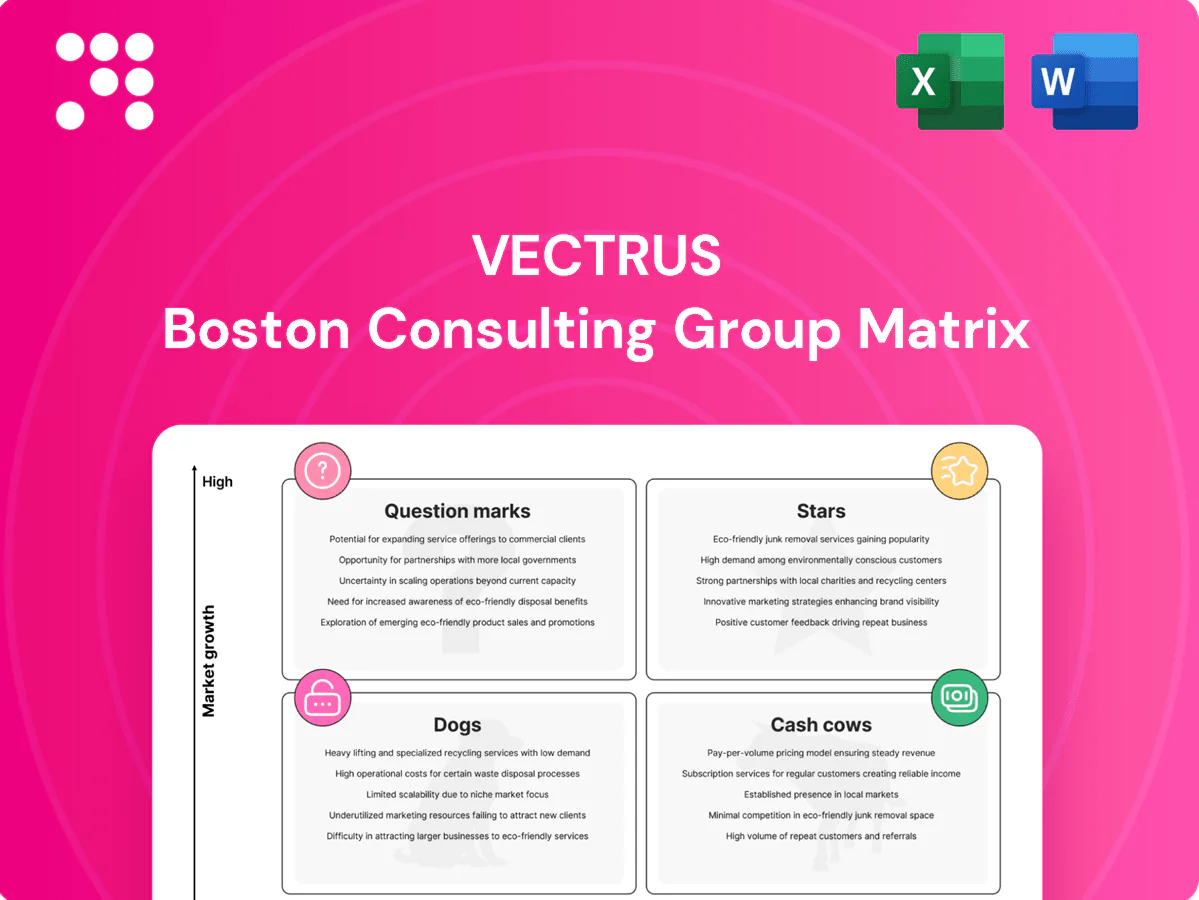
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Want to stop guessing and start allocating capital like a pro? This Vectrus BCG Matrix preview shows you the big picture—who’s winning, who’s burning cash, and which bets need rethinking. Buy the full report for quadrant-level placements, data-backed recommendations, and ready-to-present Word and Excel files that save you hours and cut straight to strategic moves. Purchase now and get the clarity you need to act fast.
High-growth mission demand in active theaters—backed by rising defense budgets (US discretionary defense ~$858B in FY2024 and global military spending $2.24T in 2023 per SIPRI)—plus Vectrus/V2X’s strong incumbency makes Integrated Base Ops a flagship, as governments favor proven end-to-end partners. Surge staffing and equipment drive heavy cash needs, but sustained share positions it to mature into a Cash Cow as tempo cools.
Cyber-hardened networks and comms upgrades are scaling fast across DoD and allies as the Pentagon’s FY2024 budget reached roughly $858B, keeping modernization spending elevated. Vectrus’s proven track record in classified, rugged environments and cleared workforce places it in the lead bucket for secure IT and network modernization. Investment remains intense—clearances, tool stacks, and talent spending—but share and contract momentum stay strong, warranting continued investment to lock in durable leadership.
Contingency Logistics & Rapid Deployment (NYSE: VEC) sees demand spike when crises hit, with government taskings often executed in hours to days, rewarding seasoned operators with increased contract share.
Integrated Facilities Sustainment for Joint Bases is consolidating into fewer large primes as multi-base, multi-service packages gain traction; Vectrus/V2X already ranks among winners on several footprints and has seen year-over-year contract renewals through 2024 driven by portfolio bundling and performance-based extensions.
Growth is propelled by high service levels that enable expansion via option periods and task-order awards; maintaining >90% quality metrics on critical SLAs secures extensions and cross-base bundling opportunities.
Operational tech meeting enterprise IT is the sweet spot—rapid growth with few true experts; DoD FY2024 budget ~$858B underpins demand. Vectrus’s field-tested integration in harsh sites creates an edge competitors struggle to copy. Big upfront engineering costs, yes, but protected share; invest to lock in standard-setter status amid ~15% CAGR in IT/OT convergence.
High-growth mission demand and FY2024 US defense ~$858B plus global $2.24T support Vectrus’s Integrated Base Ops and IT/OT convergence as Stars, driving rapid share gains. Heavy upfront costs and clearance/talent spend create cash burn but position it to become Cash Cow as tempo normalizes. Continued >90% SLA quality and multi-base wins are key triggers.
| Metric | Value |
|---|---|
| US defense FY2024 | $858B |
| Global mil spend 2023 | $2.24T |
| SLA quality | >90% |
 Detailed Word Document
BCG Matrix review of Vectrus portfolio with clear quadrant strategies - invest, hold or divest, and trend context.

 Customizable Excel Spreadsheet
One-page BCG matrix highlighting underperformers and growth bets for faster, clearer portfolio decisions.
Enduring BOS on mature installations leverages stable bases, predictable scope and repeatable SOWs to generate steady cash flow amid an $858B US defense budget in FY2024. Margin widens with process discipline and tooling; low promotional spend and tight KPIs keep costs lean. Reliable cash throws off to fund the next bets within Vectrus's services portfolio.
Supply chain and warehousing for steady theaters is a cash cow for Vectrus: throughput is consistent, lanes are known and suppliers are dialed, supporting scale that pushes unit costs down and cash flow up; Vectrus reported revenues above $1B, underpinning this steady margin profile. Modest capex (generally under 5% of revenue) keeps ops humming. Milk it while optimizing contracts and layering automation for incremental ROI.
FFP O&M contracts with tenures often spanning 3–10+ years create locked-in pricing and operational muscle memory, producing steady yield for Vectrus without frequent rebidding. Risk is largely managed through fixed scopes while negotiated change orders provide incremental, typically single-digit percentage upside. Minimal sales lift is required to maintain these contracts, so proceeds can be directed to underwrite targeted growth programs.
Network Sustainment and Helpdesk in Garrison is a low-growth, high-share cash cow for Vectrus—reliable ticket volumes and achievable SLAs make it margin-friendly at scale, with incremental tooling (automation, RPA) steadily boosting technician productivity and lowering cost per ticket.
This quiet engine room generates predictable operating cash flow and underpins free-cash-flow stability across contract cycles.
Incumbent recompetes on core footprints: incumbency advantage, proven CPARS and high transition friction favor the defender; federal incumbent win rates on recompetes averaged about 75% in 2024. High win rates require modest bidding investment, and margins are protected by existing teams, playbooks and reduced onboarding costs—keep delivering, keep cashing.
Vectrus cash cows: mature BOS and supply-chain services yield steady free cash flow from predictable SOWs amid an $858B US defense budget in FY2024, with revenues >$1B and low capex (~<5% of revenue). FFP O&M contracts (3–10+ yr) and garrison network/helpdesk deliver margin at scale; incumbency win rates ~75% in 2024 keep rebid costs low.
| Metric | Value |
|---|---|
| US defense budget FY2024 | $858B |
| Vectrus revenue 2024 | >$1B |
| Fed recompete win rate 2024 | ~75% |
| Capex | <5% rev |
| FFP O&M tenure | 3–10+ yrs |
The file you're previewing here is the exact BCG Matrix report you'll receive after purchase—no watermarks, no demo notes—just the finished, presentation-ready analysis. It’s crafted for clarity and strategic use, formatted so you can edit, print, or present immediately. After buying, the full document is sent straight to your inbox—no surprises, no revisions required.
Since the U.S. military withdrawal in August 2021 the Afghanistan market has structurally collapsed and, as of 2024, direct U.S. contracting activity in-country remains negligible. Any residual work is fragmented, low-margin and short-duration, making meaningful revenue recovery unlikely. Pursuing a turnaround would require disproportionate spend to chase a vanishing pie; best strategic option is a clean exit or orderly wind-down.
Commodity staff augmentation for Vectrus sits squarely in Dogs: low differentiation and low switching costs drive nonstop margin pressure; scale cannot cure the race-to-the-bottom pricing seen across the industry. Cash ties up in low-return headcount models while the global staffing market reached about $510 billion in 2024, reinforcing intense competition. Recommend divestment or sharp focus on niche, higher-value roles only.
Legacy on-prem data center support sits squarely in Dogs as workload migration erodes demand; according to IDC, by 2024 more than 60% of enterprise workloads were in the cloud. Maintenance-heavy work faces shrinking budgets while modernization and cloud/cyber investments cannibalize the base. Sunset services and redeploy talent into higher-growth cyber and cloud lines where 2024 global public cloud spend topped about $600 billion (Gartner).
One-off remote sites without scale are margin sinks for Vectrus: standalone geographies with tiny footprints drive fixed-overhead allocation higher, eroding unit economics despite delivering client value; with Vectrus carrying a backlog near $3.7 billion in 2024, small sites still threaten margin concentration and should be consolidated or exited unless part of larger portfolios.
Non-core design-only facilities engineering sits in Dogs: pure design gigs lack adjacency to Vectrus (NYSE: VEC) 2024 operating strengths in integrated logistics and base operations; pricing is crowded and utilization is choppy, so wins rarely convert into downstream ops revenue. Trim and refocus on bundled, integrated delivery to protect margins and bid-to-win economics.
Vectrus Dogs: commodity staff augmentation, legacy on‑prem data center support, isolated remote sites and design‑only engineering are low-growth, low-margin, high‑overhead. 2024 industry signs: global staffing ~$510B, public cloud spend ~$600B, Vectrus backlog ~$3.7B—recommend exit/consolidation.
| Segment | 2024 KPI | Action |
|---|---|---|
| Staffing | $510B market | Divest |
| On‑prem | 60% workloads cloud | Sunset |
Cyber Defense-as-a-Service for Deployed Units sits in the Question Marks quadrant: market growing rapidly (global cyber market ~200B in 2024, ~9% YoY) but Vectrus’s share is still nascent versus specialists. The offering aligns with field IT adjacencies yet faces crowded competition from niche contractors. Recommend heavy investment in talent and DoD accreditations or strategic partnerships; if customer traction fails within 12–18 months, cut losses.
Demand for C5ISR integration and sensor fusion is accelerating with JADC2 momentum, but Vectruss market share is still forming; defense tech sales cycles commonly run 18–24 months, driving high upfront costs and CAPEX. Focus on winnable expeditionary and austere niches where Vectrus has field logistics strengths and margin upside. A few scalable program wins could reclassify this business unit from Question Mark to Star.
AI-driven predictive maintenance offers huge promise for Vectrus but has limited proof at production scale in defence; industry studies (IDC/Frost & Sullivan) report up to 25% maintenance cost savings and up to 30% downtime reduction in pilots, yet DoD-style environments show few full-scale deployments. Data access and model accreditation remain major hurdles; pilot aggressively on existing bases to build trust and measure ROI. If ROI materializes, growth and market share follow rapidly.
Agencies demand digital twins of installations but budgets and procurement cycles lag, making them Question Marks in Vectrus BCG terms; Gartner estimates 50% of industrial organizations will adopt digital twins by 2025, underscoring future upside. Early wins tend to be small and integration-heavy; package twins with base operating support to accelerate adoption and favor selective investments over bespoke science projects.
Question Marks: Space/Ground Network Support — market growth is tangible but Vectrus (NYSE: VEC) has a nascent footprint; 2023 revenue ~1.26B highlights core strengths but limited space exposure. Breaking in requires cleared talent and strategic partnerships; start by expanding ground segment sustainment tied to existing DoD and allied clients. Double down only if pipeline and awarded IDIQs validate scale.
Question Marks: Cyber Defense-as-a-Service, C5ISR/JADC2, AI predictive maintenance, digital twins and Space/Ground support show fast markets but Vectrus share is nascent (Vectrus 2023 revenue 1.26B). Key barriers: accreditation, cleared workforce, 18–24 month sales cycles; strategy: selective investment, partnerships, 12–18 month win trigger.
| Metric | Value |
|---|---|
| Global cyber market 2024 | ~200B |
| Vectrus 2023 rev | 1.26B |
| Sales cycle | 18–24m |
| AI pilot ROI | ~25% cost save |
| Digital twin adoption | 50% by 2025 |


