
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
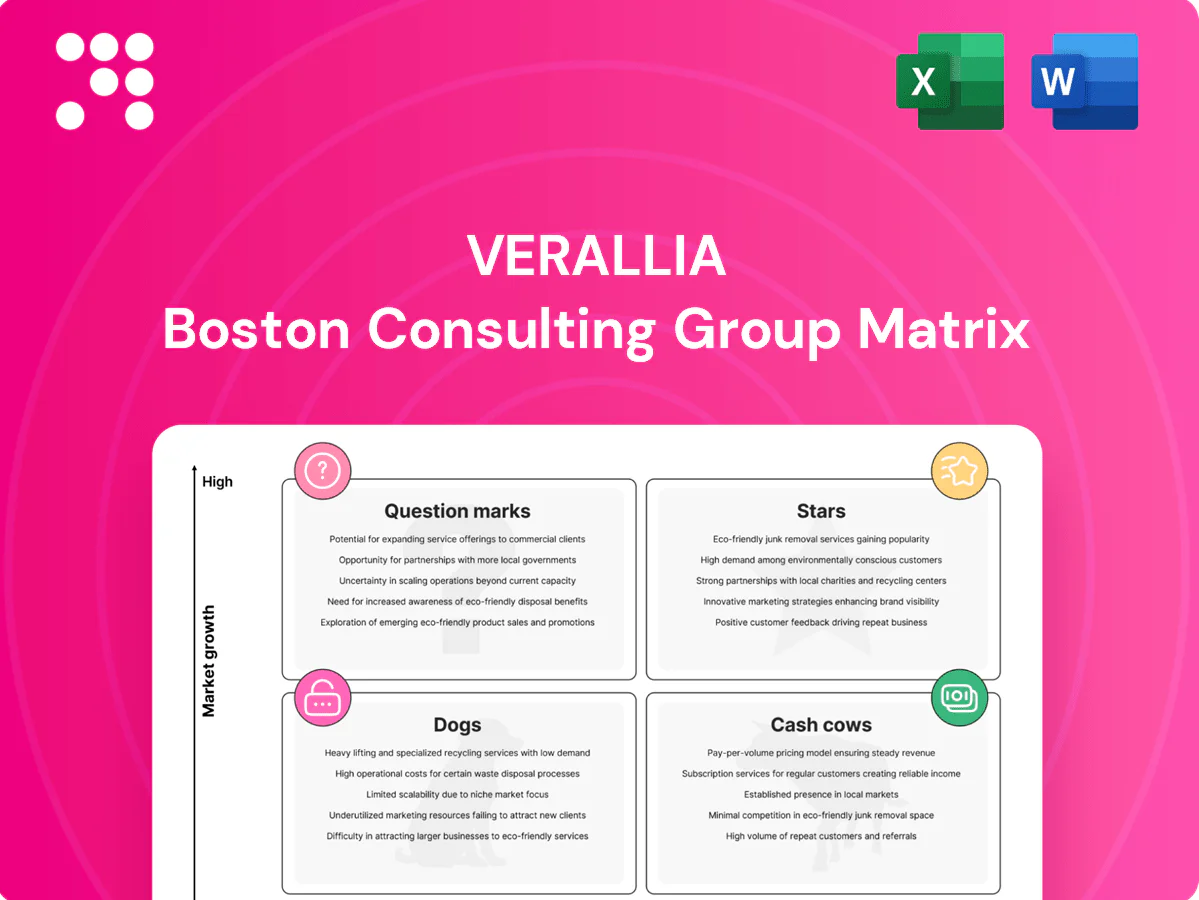
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Quick look: Verallia’s BCG Matrix teases which glass product lines are scaling fast, which cash generators are steady, and which need a rethink—critical intel if you’re steering portfolio strategy. This preview scratches the surface; buy the full BCG Matrix for quadrant-by-quadrant placements, data-backed recommendations, and clear moves to optimize capital and margins. Get instant access to a polished Word report plus an Excel summary you can present and act on—skip the legwork and make smarter, faster decisions.
In 2024 the premium wine bottles business remains a high-share, high-growth quadrant for Verallia as the category continued premiumizing across core European and American markets, driving real volume and ASP upside.
Verallia’s custom molds and design capabilities lock in top wineries, creating strong customer stickiness and pricing power.
The segment soaks capex and promotional spend but delivers payback through higher volumes and sustained price premiums, positioning it to mature into a larger cash-generating engine if share is maintained.
Premium spirits continue expanding—IWSR-type reports show premium and above segments growing around 6% value in recent years—keeping glass as the default luxury pack; the global glass packaging market was about $63.6bn in 2023. Verallia’s strength in custom shapes, embossing and rapid design cycles locks brands in, requiring upfront investment in decoration and capacity. That capex, when defended, compounds into long-term dominance.
Clients demand lower CO₂ without losing shelf appeal as regulatory pressure (EU -55% GHG target by 2030) and circularity expectations rise; EU glass packaging recycling was about 76% in 2020. Verallia’s eco‑lightweight lines deliver cost and carbon wins that create a durable moat, but ongoing R&D and customer change management burn cash today. Upside is large as adoption scales across SKUs.
Sparkling and champagne formats are premium-occasion products with resilient demand; Verallia reported group revenue of €2.35bn in 2023 and notes higher average selling prices and margin contribution from prestige formats that justify tooling and QA investments.
Design‑to‑launch custom programs are Stars for Verallia: fast concept‑to‑shelf wins drive share in markets chasing differentiation, with short runs commanding price premiums (~10–15%) and supporting Verallia’s co‑development model; Verallia reported 2024 revenue of about 4.1 billion euros, backing scale to invest up‑front. These offers need commercial support and flexible lines, so costs are front‑loaded while payoffs arrive via multi‑year contracts and portfolio expansion with the same brands.
In 2024 premium wine/spirits bottles are Stars for Verallia: high share in a ~6% value‑growing premium segment, driving ASP and volume upside. Front‑loaded capex and design spend support ~10–15% price premiums and multi‑year contracts; 2024 group revenue ~4.1bn EUR.
| Metric | Value |
|---|---|
| 2024 revenue | ~4.1bn EUR |
| Premium segment growth | ~6% value |
| Price premium | 10–15% |
 Detailed Word Document
BCG Matrix of Verallia: quadrant-by-quadrant analysis with investment recommendations, risks, and market context.

 Customizable Excel Spreadsheet
One-page Verallia BCG Matrix pinpointing portfolio pain points and quick action priorities for C-level decisions
Mature, stable demand for sauces, spreads and baby food keeps standard food jars as a Verallia cash cow; the segment underpins recurring revenue within a company reporting 2023 net sales of about €3.45bn. Verallia holds a leading European position with excellent line efficiency and low promo needs, delivering steady repeat volumes and tidy segment margins. Prioritise capex to raise throughput and accelerate cullet use (target ~70% by 2030) to sustain free cash flow.
Mainstream beer bottles are a cash cow for Verallia, driven by a large installed base and predictable reorders across core European markets. Growth in 2024 remained flat to modest while market share stayed solid and production costs were tightly controlled. Minimal selling effort and high line utilization sustain margins. The segment continued to be a dependable source of operating cash in 2024.
Private‑label and retailer molds deliver sticky volumes with reported churn near 3%, trading off price sensitivity for operational efficiency; tooling is typically amortized over 5–7 years and runs at high OEE, supporting low unit costs. Little marketing lift is required, keeping gross margins stable versus branded lines; with Verallia group revenues ~€3.2bn (2023), prioritize milking productivity and maintaining >99% service levels.
Where deposit systems are entrenched, returnable glass volumes are stable with collection rates typically above 90% and reuse cycles often exceeding 20 trips, making logistics predictable and costs largely fixed. Verallia’s formats and quality specs are standardized across mature networks, supporting high repeat demand and low growth—classic cash cow behavior. Incremental margin gains derive from durability and light‑weighting tweaks that cut transport and breakage costs.
Non-alc staples like juices and sauces are stable grocery categories with predictable turns, high market share and optimized SKUs, requiring limited innovation and enabling strong plant efficiency. These glass-packed lines generate steady margins and reliably cover overhead, freeing capital to fund higher‑growth bets.
Mature food jars, mainstream beer bottles, private‑label molds and returnable formats act as Verallia cash cows, delivering stable repeat volumes, high plant utilization and steady margins; group net sales were ~€3.45bn in 2023. Collection rates in deposit markets exceed 90% with reuse cycles >20 trips, and many plants run >80% utilization. These segments fund capex and low‑risk free cash flow.
| Metric | Value |
|---|---|
| Group sales 2023 | ≈€3.45bn |
| Glass market 2024 | ≈USD 64bn |
| Collection rates | >90% |
| Reuse cycles | >20 trips |
| Plant utilization | >80% |
The Verallia BCG Matrix you're previewing is the exact file you'll receive after purchase — no watermarks, no placeholders, just the finished report ready for use. It’s built for strategic clarity with market-backed insights tailored to Verallia’s portfolio. After buying, you’ll get the full, editable document immediately for presenting, printing, or sharing with stakeholders.
Heavy legacy SKUs at Verallia are older, 2024-era bottle designs that are roughly 20% heavier than modern lightweight formats and face growing sustainability pushback. Low market growth for these SKUs and price pressure have squeezed margins, with incremental margin erosion observed across 2024. Retooling lines is capital-intensive and ROI estimates often exceed a 10-year payback, favoring sunset or redesign rather than propping them up.
Commodity CSD take‑home glass is a low-share dog: in 2024 glass represents roughly 8% of European take‑home CSD packaging versus PET ~70% and aluminium cans ~18%, volumes flat year‑on‑year and margins compressed below industry averages. It ties up furnace capacity with low utilization and opportunity cost, making the segment a prime candidate for exit or consolidation.
Fragmented micro-runs with high changeovers destroy line efficiency: frequent swaps cut throughput and can reduce overall OEE by 15–30% in glass container plants, making tiny batches hard to scale. Pricing on these niche SKUs rarely offsets the downtime, leaving them cash neutral at best and often a margin trap. SKU bundling or rationalization in 2024 freed plants 20–35% capacity in benchmark operations, a direct lever to restore utilization.
Non‑core geographies with high energy cost: when logistics and energy spike, Verallia margins erode quickly; market share is small and hard to grow, and turnarounds become costly, so redeploying capacity to stronger hubs preserves margin and cash.
Low‑value generic molds with copycat supply show no real differentiation, are easy to undercut and lost volume: 2024 volumes ~0% YoY while average realizations fell an estimated 3% in 2024, driving steady price erosion as customers switch on cents; divest or restrict to backfill idle lines.
Dogs: heavy legacy SKUs (~20% heavier) and low‑share commodity take‑home CSD (glass ~8% vs PET ~70%, cans ~18%) face flat volumes (2024 ~0% YoY) and ~-3% price erosion, compressing margins and tying up furnace capacity; frequent micro‑runs cut OEE 15–30%. Recommend SKU rationalization or exit; redeploy capacity to stronger hubs.
| Metric | 2024 | Action |
|---|---|---|
| Glass CSD share | 8% | Exit/Consolidate |
| Price erosion | -3% | Divest/restrict |
| OEE hit | 15–30% | SKU bundling |
RTD and aperitif glass formats sit in Question Marks as the category posted double-digit growth across key markets in 2023–24 while Verallia’s share varies significantly by region. Brands are still settling on formats and volumes, keeping demand unpredictable. Invest in agile tooling and on-line decoration to win trial runs and shorten time-to-market. If traction stalls, pivot capacity back to core glass SKUs.
Question Marks: Kombucha & premium mixers are fast‑growing niches—kombucha global market ~USD 2.8B in 2024 with ~10% CAGR and premium mixers ~USD 4.1B in 2024—yet both remain highly fragmented so Verallia’s share is low (<5% typical by SKU). Target design‑led SKUs and mid‑scale runs to win anchor accounts; prioritize rapid scale to reach break‑even or cut the tail.
Home delivery demands lighter, tougher, pack‑friendly glass as online retail reached roughly $6.3 trillion globally in 2024 and ~23% retail share, creating real growth but uneven adoption and thin margins. Returns and breakage can erode profits; pilot with key retailers and 3PLs to validate real-world breakage rates and landed costs. Double down only if unit economics — CAC, return rate, and contribution margin — prove positive.
On-bottle personalization is a high-growth trend as of 2024 but remains not fully industrialized; Verallia holds key digital-decor tech pieces yet commands a limited share of large-scale deployments. Recommend funding capex only where firm volume commitments exist; if projected throughput or ink cost targets for 2024 pilots fail, pause rollout to preserve margins.
Low‑carbon furnaces and high‑cullet lines sit in Question Marks: sustainability demand is skyrocketing while commercial premia are still forming, share is emerging and capex is heavy. Secure long‑term offtakes linked to CO₂ targets to de‑risk investment; EU ETS traded around €90/t in 2024, improving future margin visibility. If pricing won’t cover the delta, stage investments and tie payments to verified CO₂ reductions—high cullet use can cut furnace CO₂ by up to ~30%.
Question Marks: fast‑growing niches (kombucha USD 2.8B, 10% CAGR; premium mixers USD 4.1B) and RTD/aperitif glass (double‑digit growth) show demand upside but Verallia share is low (<5%); invest conditional capex tied to validated pilot throughput/ink costs and secured offtakes. EU ETS ~€90/t (2024) and high‑cullet can cut furnace CO₂ ~30%, but capex is high—stage investments if premia remain volatile.
| Segment | 2024 size | CAGR | Verallia share | Capex |
|---|---|---|---|---|
| Kombucha | USD 2.8B | ~10% | <5% | Low‑mid |
| Premium mixers | USD 4.1B | — | <5% | Low‑mid |
| Low‑carbon furnaces | — | — | emerging | High |


