
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Vista Outdoor faces strong supplier and regulatory pressures, intense retail and brand competition, and evolving substitute and entrant threats that collectively shape margin dynamics and strategic options. This brief snapshot only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore Vista Outdoor’s competitive dynamics, market pressures, and strategic advantages in detail.
Concentrated critical inputs such as propellants, primers, specialty metals, optics glass and advanced polymers come from a limited pool of qualified suppliers, and certification, safety and performance standards further narrow alternatives. This supplier concentration raises switching costs and delivery risk for Vista Outdoor, which reported approximately $2.1 billion in net sales in fiscal 2024. Long-term contracts and dual-sourcing programs partially mitigate supplier leverage and help stabilize supply chains.
Steel, brass, copper and petrochemical resins face global price swings, with manufacturers seeing up to 20% y/y input volatility in recent cycles; such spikes compress ammunition and hardgoods margins materially. Hedging and value engineering moderate exposure but often trail sudden market shocks. Ability to pass costs through varies by channel power and end-market demand seasonality.
Defense-grade and sport-ammo inputs must meet strict ballistic, safety and environmental specs under ITAR and EPA rules, aligning with a U.S. defense budget of about $858 billion in 2024 that drives demand for compliant suppliers. Only vetted vendors can meet these standards, limiting substitution and granting suppliers leverage over pricing and delivery. Regular audits and approved-vendor lists (APL) constrain opportunism and protect quality.
Imports of components and finished goods face tariffs, export controls and shipping disruptions that raised input costs; tight freight markets pushed lead times up to ~30% in 2023–24, allowing suppliers to negotiate allocation and surcharges. Regionalization and inventory buffers cut but do not eliminate geopolitical/logistics exposure for Vista Outdoor.
Optics, electronics and specialty parts for Vista Outdoor often rely on branded upstream technology, and in 2024 suppliers retained significant leverage in negotiations. Unique sensor, lens and circuit features can lock Vista into specific vendors, increasing suppliers' price influence. Strategic co-development agreements with exclusivity clauses are used to rebalance power while securing differentiated products.
Concentrated, certified suppliers of propellants, primers, optics and polymers limit substitution and raise switching costs for Vista Outdoor, which reported $2.1B net sales in fiscal 2024. Global input price swings have shown ~20% y/y volatility, compressing margins. Freight and geopolitical issues raised lead times ~30% in 2023–24, letting suppliers apply surcharges. Defense demand (US budget ~$858B in 2024) further constrains vendor pools.
| Metric | Value (2023–24) |
|---|---|
| Vista Outdoor net sales | $2.1B |
| Input volatility | ~20% y/y |
| Lead time change | +~30% |
| US defense budget | $858B |
 Detailed Word Document
Tailored Porter's Five Forces analysis for Vista Outdoor uncovers competitive drivers, buyer and supplier power, threat of substitutes and new entrants, and highlights disruptive forces and strategic levers that shape the company’s pricing, profitability, and market resilience.

 Customizable Excel Spreadsheet
A clear, one-sheet Porter's Five Forces summary for Vista Outdoor—instantly highlights competitive, supplier and buyer pressures so teams can make faster, confident strategic decisions.
Large retailers and distributors such as Walmart and Bass Pro exert outsized leverage over Vista Outdoor, able to demand promotional spend, better pricing, and high fill rates; Vista Outdoor reported approximately $2.06 billion in net sales for FY2023, concentrating negotiating exposure in core categories. Concentration among key buyers elevates customer power, while diversifying channels in 2024 reduces dependence and bargaining risk.
Price-sensitive enthusiasts increasingly shop online, with 72% reporting cross-brand feature and price comparisons in 2024, forcing Vista Outdoor to match online pricing. Promotions and rebates influenced purchase timing for roughly 60% of buyers in 2024, amplifying short-term demand swings. Strong brand equity in premium segments reduces price sensitivity by about 30%, while transparent reviews compressed mid-tier SKU margins roughly 150–200 basis points in 2024.
DTC channels let Vista Outdoor capture customer data and higher margins but raise expectations on price and fast service; online marketplaces like Amazon (≈38.7% of US e-commerce in 2023) enable easy switching and price comparison. Bundles and loyalty programs can lock in repeat buyers and boost lifetime value, while poor service or fulfillment issues materially amplify churn risk.
Retailers can push house brands in accessories and softgoods, and by 2024 private-label share in U.S. apparel/accessories approached about 20%, putting price pressure on Vista Outdoor's national brands. Comparable specs at lower prices compress margins, while differentiation through measurable performance and patented design helps counter the threat. Exclusive SKUs and retailer partnerships protect shelf space and ASPs.
Ammunition and shooting categories are highly cyclical and policy-sensitive, shifting buyer urgency and reducing customer bargaining power during spikes and increasing it in downturns; NICS background checks peaked at 39.7 million in 2021 (FBI), illustrating demand-driven volatility. Backlogs during spikes limit discounting, while stable outdoor categories (recreation products) temper overall volatility for Vista Outdoor.
Large buyers like Walmart and Bass Pro exert strong leverage over Vista Outdoor, concentrated by FY2023 net sales of $2.06B. Online comparison (72% in 2024) and Amazon's ~38.7% US e-commerce share force competitive pricing; promotions sway ~60% of buyers in 2024. Private-labels (~20% share in 2024) and low-cost alternatives compress margins, while DTC, exclusive SKUs and premium branding mitigate bargaining power.
| Metric | Value |
|---|---|
| FY2023 net sales | $2.06B |
| Online comparison (2024) | 72% |
| Promotions influence (2024) | ~60% |
| Private-label share (US, 2024) | ~20% |
| Amazon US e-commerce (2023) | ~38.7% |
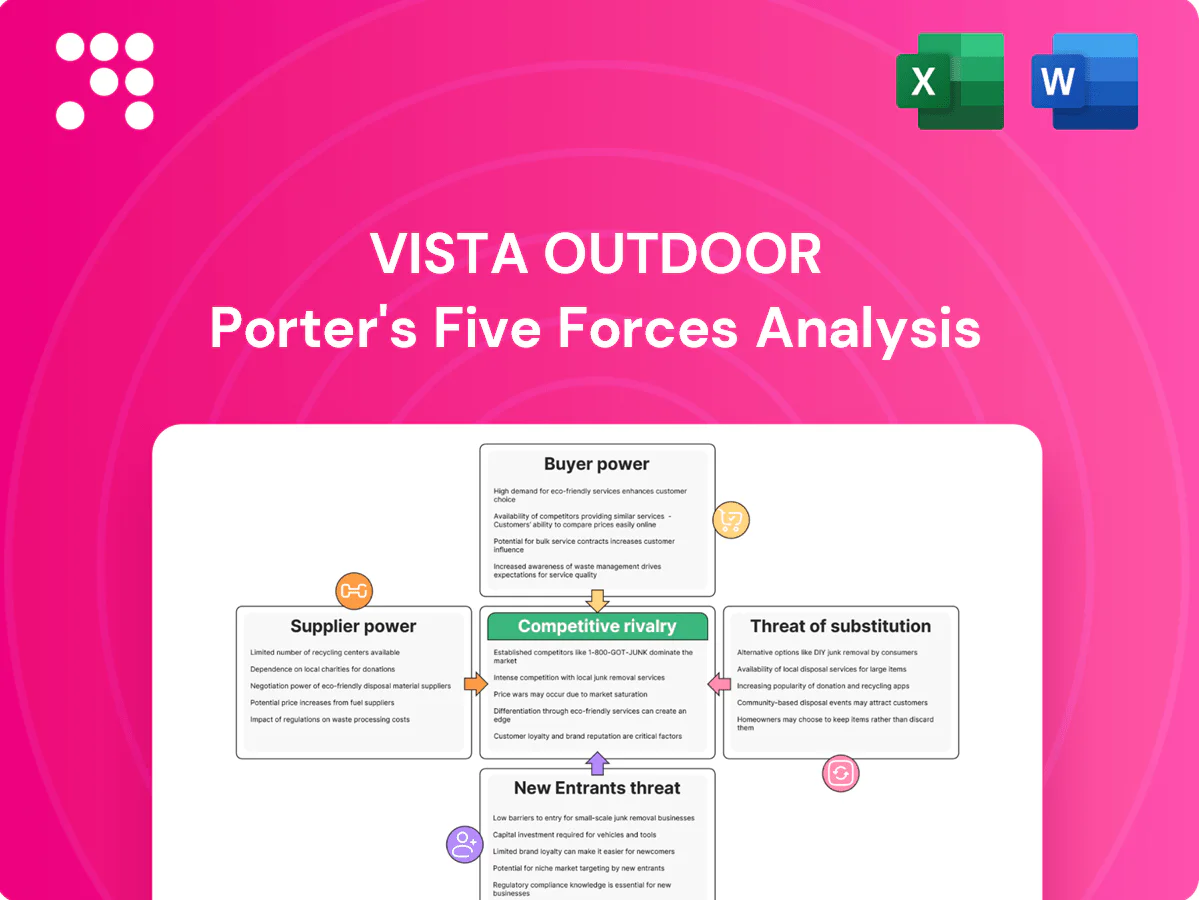
This preview shows the exact Porter's Five Forces analysis for Vista Outdoor you'll receive immediately after purchase—no surprises or placeholders. The document displayed is the full, professionally written and formatted analysis, ready for download and use the moment you buy. You’re previewing the final deliverable; instant access to this same file follows payment.
Vista Outdoor competes across ammo, optics, helmets, packs and cycling accessories via brands such as Federal, Bushnell, Bell, Giro and CamelBak, facing dozens of specialist rivals in each niche.
Rivalry intensifies where product differentiation is thin, driving price and distribution battles in commodity ammo and entry-level accessories.
In premium segments, heritage brands and proven performance sustain margin advantages and customer loyalty.
Innovation in materials, ballistics, comfort and connected tech drives 12–18 month refresh cycles in shooting sports and outdoors gear, keeping Vista Outdoor and rivals in constant R&D and SKU churn. Rapid imitation compresses average selling prices and margins, while patents provide temporary advantages but rarely exclude competitors long-term. Speed-to-market and athlete/LE endorsements remain decisive for share gains in 2024.
End-cap placement, strict minimum advertised price policies and manufacturer co-op spend drive intense promotion and channel battles, as retailers prioritize SKU turn and margin, intensifying price wars. Direct-to-consumer exclusives create a parallel battlefield that fragments assortment and promotional leverage. Superior omnichannel execution — seamless inventory, pricing and fulfillment — becomes a key differentiator in retailer and consumer choice.
Operational efficiency gaps matter: Vista Outdoor leverages scale in sourcing and manufacturing to sustain a cost edge in ammunition and hardgoods, supporting roughly $1.9B in 2024 net sales and enabling competitive pricing. Utilization swings have widened unit-cost differences across peers, while lean operations allow price flexibility without margin erosion. Consistent supply reliability drives repeat orders and channel share.
Product reliability and recalls can shift share quickly for Vista Outdoor; the company reported approximately $1.93 billion in revenue in FY2023 and manages over 40 outdoor and shooting brands, so safety incidents invite intense scrutiny and rapid switching by distributors and consumers. Robust QA, transparent communication, and third-party certifications (e.g., ISO, independent ballistic testing) defend position and preserve retailer trust.
Vista Outdoor faces intense rivalry across ammo, optics and hardgoods where thin differentiation drives price and channel battles, while premium brands retain margin resilience. Rapid 12–18 month product cycles and fast imitation compress ASPs; patents offer temporary protection. Scale, lean ops and supply reliability provide Vista cost and distribution advantages supporting roughly $1.9B 2024 net sales.
| Metric | 2024 |
|---|---|
| Net sales | $1.9B |
| Brands managed | 40+ |
| Product cycle | 12–18 months |
| Competitive pressure | High |
Consumers easily switch between shooting, fishing, hiking or cycling based on budget and time, making recreational trade-offs that can shift demand; industry surveys show multi-activity participation is common. Vista Outdoor's portfolio spans over 40 brands across shooting and outdoor segments, which mitigates company-level substitution, while single-category brands remain more exposed to activity shifts.
Secondary markets and rental programs offer lower-cost access that delays replacements and reduces demand for new units; in 2024 the growing resale/rental trend pressured OEM sell-through across outdoor categories. Brands can counter with certified-refurb and trade-in channels to recapture margin and data while boosting repeat purchases. Durable design extends product lifecycle, improving lifetime value but damping SKU velocity and near-term revenue.
Gaming (~$184B global market in 2023), streaming (≈1.5B paid subscriptions globally) and booming at‑home fitness offer strong substitutes for firearm/outdoor leisure spend, a shift amplified in downturns as consumers trade durable goods for lower‑cost entertainment; Vista Outdoor counters with immersive product communities and events, while subscription training apps and content can complement gear and boost retention.
Training simulators and dry-fire tools cut live-ammo consumption—manufacturers claim dry-fire can replace up to 90% of practice rounds—driving substitution for casual shooters and clubs, while home setups replicate many reps; Vista Outdoor can capture accessory spend by offering compatible sensors, targets and magazines, but real-world performance plateaus still necessitate periodic live-fire for recoil and terminal-ballistics validation.
Non-branded accessories and general-purpose gear can substitute Vista Outdoor's specialized products as pragmatic buyers opt for lower-cost alternatives offering adequate performance; recent 2024 market trends show rising value-seeker purchases. Differentiated features, proven performance and extended warranties help Vista resist trade-down. Targeted education campaigns expose value gaps and preserve premium pricing.
Substitution risk is moderate: multi-activity consumer switching and resale/rental trends reduced OEM sell-through in 2024.
Digital substitutes (gaming $184B in 2023; ~1.5B streaming subs globally) and dry-fire (up to 90% live‑ammo reduction) pressure spend on live ammo and gear.
Vista mitigates via 40+ brands, certified-refurb, trade-ins, accessories and training content.
| Substitute | Impact | 2023/24 stat |
|---|---|---|
| Gaming/Streaming | Spend diversion | $184B / ~1.5B subs |
| Dry‑fire | Practice replacement | Up to 90% ammo use↓ |
Ammunition and safety-equipment makers must obtain Federal Firearms Licenses and meet ATF testing and traceability rules, while exports fall under ITAR/EAR, with violations carrying fines exceeding $1 million and up to 20 years' imprisonment; such regulatory layers raised upfront compliance costs into the millions in 2024. Liability exposure and complex supply-chain controls create steep learning curves, deterring casual entrants and protecting incumbents like Vista Outdoor.
End-users in hunting, defense, and law enforcement prize proven performance, so building credibility takes years; Vista Outdoor benefits from legacy names like Federal Ammunition (founded 1922) and Bushnell (founded 1948) and from the company’s 2015 formation after the ATK spin-off. Failures or safety incidents are costly and public, eroding trust rapidly. This entrenched reputation raises the barrier for new entrants.
Ammo manufacturing and high-spec hardgoods demand heavy capex and specialized processes, and Vista Outdoor reported net sales of about $2.1 billion in FY2024, reflecting scale advantages that lower unit costs and fund R&D. Economies of scale make it hard for newcomers to match breadth and inventory depth across ammunition and accessories. Contract manufacturing eases entry only in select, lower-spec categories, not core precision ammo and hardgoods.
Retailers prioritize partners that deliver dependable fill rates, promotional support and MAP compliance, making slotting access costly for newcomers; DTC channels lower shelf-dependence but raise customer acquisition costs and logistics burdens. Established brands defend shelf space with exclusive assortments and entrenched retailer relationships, keeping the threat of new entrants moderate.
Patents, trade dress, and proprietary materials held across Vista Outdoor product lines create legal barriers that slow copycats and protect margins; sponsored teams and influencers shape consumer preferences, making brand equity a key moat. Entrants must invest heavily in product development, IP clearance, and promotion to gain visibility, while fast followers still face costly legal challenges and uphill marketing battles.
Regulatory compliance (ATF, ITAR/EAR) and potential fines >$1M plus prison risk raise upfront compliance costs into the millions in 2024, deterring new entrants. Brand legacy and FY2024 sales ~ $2.1B give Vista scale advantages; capex, IP and retailer slotting further limit threats.
| Barrier | 2024 Metric |
|---|---|
| Regulatory cost/risk | Fines >$1M; compliance costs: millions |
| Scale | Vista FY2024 sales ~$2.1B |
| Brand/IP/slotting | High marketing/R&D & entrenched retail access |


