
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
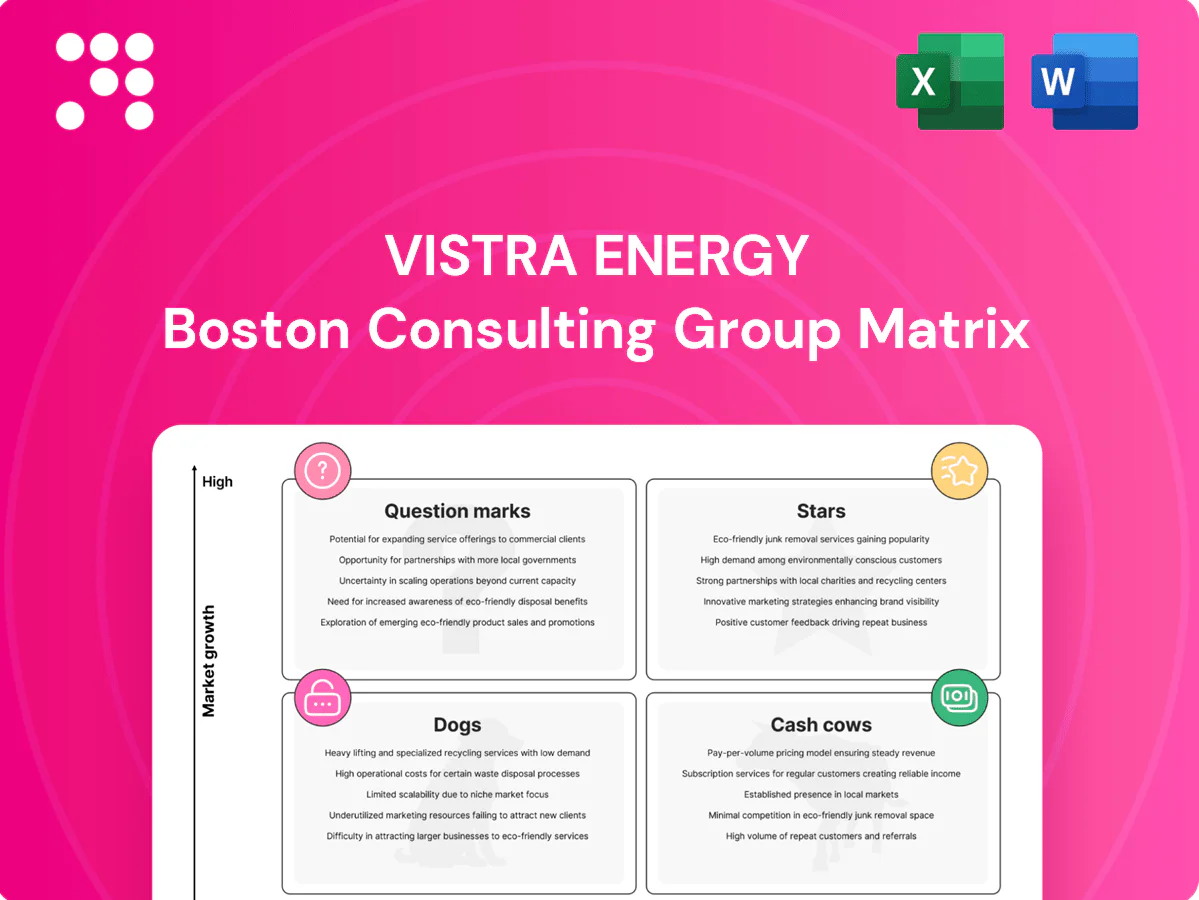
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Quick snapshot: Vistra Energy's BCG Matrix highlights where its generation assets and retail offerings sit—some are cash cows, a few look like question marks, and a couple could be underperforming. Want the full picture with quadrant-by-quadrant data, strategic moves, and where to allocate capital next? Purchase the complete BCG Matrix for a ready-to-use Word report plus an Excel summary that saves you hours and gives clear, actionable recommendations.
Vistra’s Texas retail franchise, with roughly 27% ERCOT residential/commercial share and about 2.6 million customers in 2024, is a Star: high share in a fast-growing market driven by population and business migration. The customer book scales with demand but needs steady promotion and channel muscle to retain margins. Preserve share and this engine can mature into a larger cash generator; invest to defend pricing power and customer experience.
Modern combined-cycle CCGTs win as demand rises and renewables add volatility, with natural gas supplying roughly 40% of US generation in 2023–24 (EIA), so plants clear the stack more often and respond fast. They require ongoing capex and disciplined hedging to protect margins. With dispatch advantage they can graduate into cash cows as growth normalizes; continuous heat-rate and fuel-logistics optimization is essential.
Scale plus data give Vistra an edge: its ~40 GW generation fleet and ~2.7 million retail customers in 2024 allow trading and hedging to shape margins across retail and generation, improving capture during market swings. As a growth lever, the platform boosts returns when volatility rises, though working capital and collateral needs can be heavy in stressed months. With market share and sophisticated analytics, trading throws off substantial free cash flow; continued investment in analytics and risk governance is essential.
Integrated retail-gen synergy positions Vistra to capture margin others leave: owning load and supply lets Vistra internalize savings across hedges and peaking assets; cross-hedging cuts realized volatility though coordination costs rise. In Texas, with load growth and ERCOT tightness, that synergy compounds; double down on portfolio optimization and customer mix.
Large C&I contracts and data center load are Stars for Vistra as exploding large-load demand boosts volumes and visibility; global data center electricity use remains near 200 TWh in 2024, underscoring scale. These deals require bespoke structuring and credit support, keeping sales and risk teams busy. Land and keep them and they become durable profit centers; prioritize reliability, uptime guarantees, and flexible pricing.
Vistra’s Texas retail (≈27% ERCOT; ≈2.6M customers in 2024) and modern CCGTs (≈40 GW; gas ≈40% US gen 2023–24) are Stars: high share in fast-growing, volatile markets. Integrated trading/retail (~2.7M customers) boosts capture but raises collateral needs. Invest in capex, analytics, disciplined hedging and bespoke C&I deals (data centers ≈200 TWh 2024).
| Metric | 2024 |
|---|---|
| ERCOT retail share | ≈27% |
| Retail customers | ≈2.7M |
| Fleet | ≈40 GW |
 Detailed Word Document
In-depth BCG analysis of Vistra Energy’s units, outlining Stars, Cash Cows, Question Marks and Dogs with clear invest, hold, or divest guidance.

 Customizable Excel Spreadsheet
One-page Vistra Energy BCG matrix that quickly spots weak units and focuses capital—cuts analysis time for execs.
High capacity factors drive steady cash: U.S. nuclear averaged a 92.9% capacity factor in 2023 (EIA), delivering baseload hours and premium reliability in mature markets. Fuel is a small share of operating cost, supporting stout margins while market growth remains modest. Capex is planned and predictable—NRC renewals have extended many plants to 60 years with a regulatory path to 80—so maintaining licenses, safety, and uptime keeps cash flowing.
Established Texas mass-market retail is a cash cow: a loyal residential base, proven acquisition channels and low churn produce predictable cash flow—Vistra’s retail footprint of roughly 3.8–4.2 million customers in 2024 supports material retail contribution to consolidated adjusted EBITDA. Market growth slowed to low single digits in 2024, so an entrenched share lets marketing be efficient; milk with smart pricing, improved CSAT and cheaper service costs.
Frequency response and reserves monetize plant flexibility without large growth capex, leveraging Vistra's ~39 GW fleet (2024) to capture recurring capacity payments and fast-ramping premiums. Revenues are operationally efficient and largely recurring, supporting stable cash flow even when energy margins fluctuate. Not glamorous, these ancillary streams are reliably accretive. Optimize bids and reduce outages to preserve margin.
Transmission and congestion rents exposure sits in Vistra’s cash cows quadrant, benefiting from predictable constraints and nodal spreads that produce steady carry rather than rapid growth. With mature asset positions and refined analytics, the business converts nodal price differentials into reliable revenue streams when models are maintained and hedges are applied prudently. The strategy is to maintain models, hedge systematically, and pocket the spread to sustain cash generation.
Retail value-added services—fixed-rate plans, bill protection and simple add-ons—produce steady margins for Vistra, delivering dependable contribution with low single-digit growth (≈1–3% in 2024) and high retention economics that limit acquisition spend.
Once scaled, minimal promotion is needed; streamlining operations and targeted upsell can raise customer lifetime value and preserve margin stability versus wholesale volatility.
High-capacity baseload (U.S. nuclear ~92.9% CF 2023) plus predictable retail (3.8–4.2M customers in 2024) and ~39 GW fleet (2024) create low-growth, high-margin cash cows; ancillary services and transmission congestion rents add recurring, operationally efficient revenue; focus on uptime, license renewals, hedging and targeted upsell to preserve cash flow.
| Metric | 2024 |
|---|---|
| Retail customers | 3.8–4.2M |
| Fleet capacity | ~39 GW |
| Nuclear CF (latest) | 92.9% (2023) |
| Retail growth | ≈1–3% |
The file you're previewing is the exact BCG Matrix report you'll receive after purchase. No watermarks, no demo text—just a fully formatted, ready-to-use strategic tool. It's editable, printable, and crafted by strategy pros for clarity. Buy once, download immediately, and plug it straight into your planning or pitch. No surprises, just actionable analysis.
Dogs:
Small, isolated retail footprints in Vistra’s portfolio suffer from weak brand pull and high customer acquisition costs, dragging overall retail economics; Vistra serves roughly 3 million retail customers and faces low-single-digit retail EBITDA margins in many subscale markets. Low share, little growth and limited operational leverage leave cash tied up with thin margins. These Dogs are candidates for exit or consolidation into larger retail platforms to free capital.
Inefficient simple-cycle gas peakers in Vistra’s fleet have heat rates often above 10,000 Btu/kWh versus modern combined cycles at ~6,500–7,500 Btu/kWh, so they lose to newer flexible assets. Scarcity rents are sporadic—price spikes occur in a limited number of hours per year—so revenues are unreliable. High opex and looming capex for emissions/controls crowd out returns. Mothball, sell, or repower only if project IRR and payback meet corporate thresholds.
Dogs: Low-margin default service books are highly regulated, price-capped, and administratively heavy; share gains rarely translate into profit and erode EBITDA despite Vistra’s ≈39 GW generation footprint (2024). Cash gets trapped in churn and billing complexity, raising unit costs and working capital needs. Shrink exposure or renegotiate tariffs and cost-recovery terms to stop margin leakage.
Dogs: aging coal units (U.S. coal ~18% generation 2023) and inefficient gas peakers (heat rate >10,000 Btu/kWh) deliver low returns; subscale retail (~3M customers) and regulated default service trap cash with low-single-digit retail EBITDA; legacy IT (70% maintenance) inflates costs—options: retire/divest, consolidate retail, repower/mothball peakers, modernize IT.
| Dog | Metric |
|---|---|
| Coal | U.S. coal 18% (2023) |
| Retail | ~3M customers; low-single-digit EBITDA |
| Peakers | Heat rate >10,000 Btu/kWh |
| IT | 70% maintenance (Gartner 2024) |
Grid needs are booming but Vistra’s utility-scale battery footprint is still forming in several markets, leaving it in the Question Marks quadrant; capex is high and returns depend on proprietary dispatch algorithms and evolving market rules. Upside to become a Star is material if Vistra scales projects and wins interconnection. Invest selectively where interconnection queues and revenue-stacking (capacity, frequency, energy) pencil.
New solar is a high-growth market—EIA projected roughly 38 GW of US utility-scale solar additions in 2024—but crowded supply and multi-year interconnection delays (commonly 2–5 years) constrain near-term wins. Vistra’s share varies significantly by node and state, creating pockets of advantage. If execution tightens, projects can scale quickly; prioritize best-fit sites and long-term offtake to de-risk pipelines.
EV and home electrification are rising — global EV share reached about 18% in 2024 (BNEF), yet penetration and brand attachment remain early, so Vistra sits as a Question Mark. Customer acquisition costs can exceed $1,000 per household, threatening margins. Strategic land partnerships and energy+charging bundles can tip the curve. Rapid test-learn-scale pilots to scale winners fast.
Policy tailwinds (IRA, state mandates, FERC) and falling battery/controls costs enable DER aggregation and VPPs, but Vistra’s current VPP/DER revenue is a tiny slice compared with its ~40 GW fleet (<1% share today); complexity in dispatch, telemetry and settlement slows lift-off.
Customers express strong demand for carbon-free branded retail offerings, but willingness to pay varies by region and segment; Vistra serves roughly 3 million retail customers (Vistra 2024 filings), yet branded-share outside core ERCOT/CAISO markets remains nascent. With smart sourcing and REC/contract optimization, pilots can scale into leadership where price and uptake align. Pilot, price precisely, then expand only where measured uptake justifies investment.
Vistra’s batteries, utility solar, EV/home and VPPs are Question Marks: high growth potential but low share and high capex/execution risk. Key 2024 facts: ~40 GW fleet, ~3M retail customers, US utility solar +38 GW (EIA 2024), global EV ~18% (BNEF 2024), VPP/DER <1% revenue. Prioritize selective scale, interconnection wins, software/aggregator build to convert to Stars.
| Metric | 2024 |
|---|---|
| Fleet | ~40 GW |
| Retail | ~3M customers |
| US solar additions | ~38 GW |
| Global EV | ~18% |
| VPP/DER share | <1% |


