
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
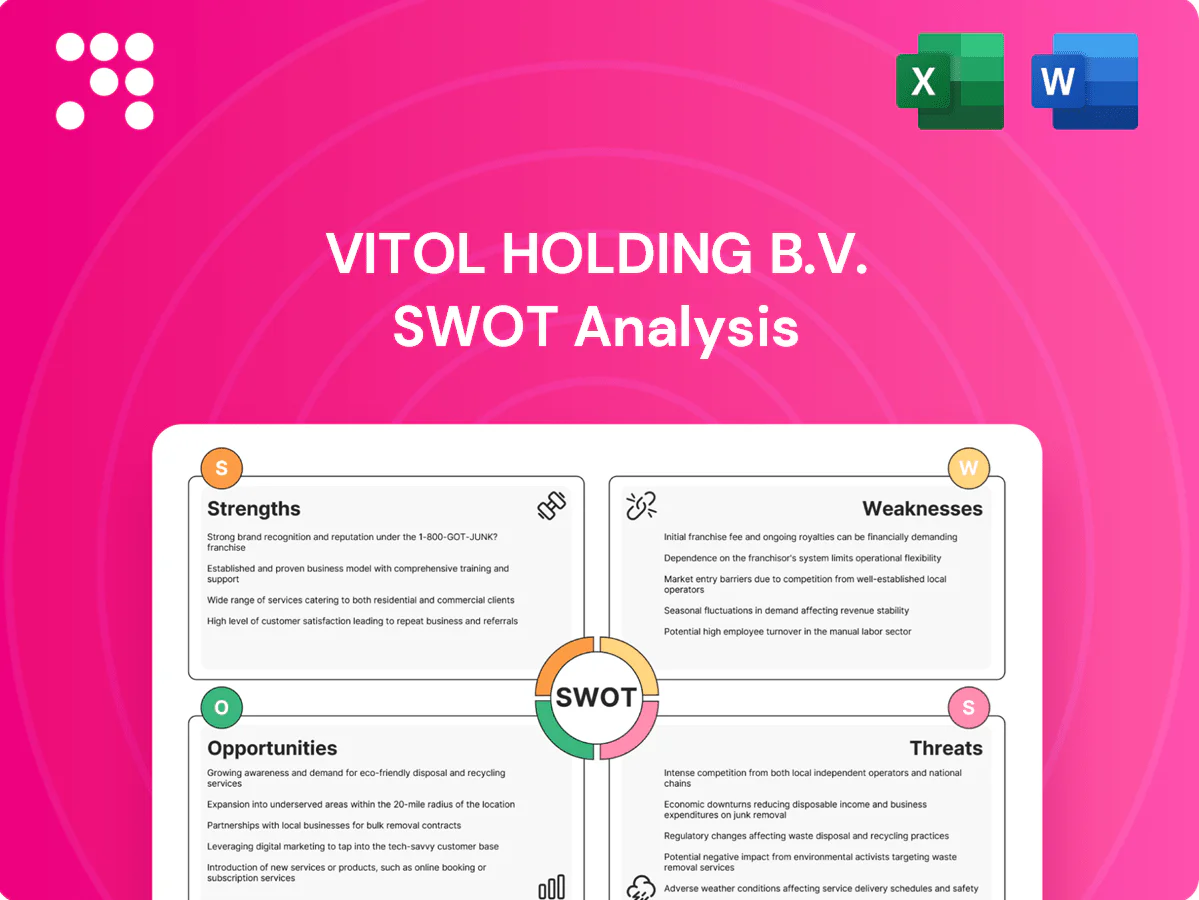
Vitol Holding B.V. combines unrivaled trading scale, deep logistics networks, and strong supplier relationships, yet it confronts commodity volatility, regulatory pressures, and energy-transition risks; our SWOT pinpoints these dynamics and strategic levers. What you’ve seen is just the beginning. Gain full access to a professionally formatted, investor-ready SWOT analysis of the company, including both Word and Excel deliverables.
Vitol operates across more than 40 countries, linking producers and consumers across continents to create a broad trading footprint. This network delivers market access, optionality and rapid arbitrage opportunities across major oil, LNG and refined-product hubs. Scale supports better pricing, tighter logistics coordination and sourcing flexibility. Geographic breadth also enhances resilience when individual markets dislocate.
Vitol trades crude, refined products, LNG, LPG, coal, metals and carbon, handling roughly 8 million barrels per day equivalent across its portfolio, which positions it as a leading integrated commodities trader. This diversification smooths earnings across cycles and reduces single‑commodity exposure, evidenced by more stable margin streams versus pure-play oil traders. Cross‑commodity insights enhance hedging and structuring capabilities, enabling tailored bundled supply solutions for large industrial and utility customers.
Vitol’s ownership stakes in terminals, refineries, power and upstream assets anchor physical flows—supporting a business that reported about $505bn revenue in 2023 and trades roughly 8–9m bpd—while physical optionality (blending, storage, timing) boosts margins, integrated assets improve reliability and customer service, and proprietary operational data refines trading decisions.
Vitol's logistics and risk management expertise—moving about 7 million barrels/day and reporting roughly $505bn turnover in 2023—cuts shipping, storage, and scheduling costs while limiting delays. Advanced hedging and structuring mitigate price, basis, and credit risks, enabling tailored supply-chain solutions and dependable delivery in volatile 2024–25 markets.
Vitol's long-standing ties with producers, refiners, utilities and end-users generate steady deal flow and continuous market intelligence; the group traded about 7 million barrels per day and reported roughly $505 billion revenue in 2023, enabling faster price discovery and execution. Relationship capital supports complex multi-year contracts and superior access to scarce cargoes and infrastructure.
Vitol's global footprint in 40+ countries and ~7–9m bpd throughput delivers market access and rapid arbitrage. Diversified trading across crude, products, LNG, LPG, coal, metals and carbon and ~$505bn revenue in 2023 smooths earnings. Ownership stakes in terminals, refineries and upstream assets provide physical optionality and margin uplift. Strong producer/refiner ties and advanced hedging enable complex multi‑year contracts and resilient supply solutions.
| Metric | Value |
|---|---|
| 2023 revenue | $505bn |
| Throughput | ~7–9m bpd |
| Countries | 40+ |
| Commodities | Crude, products, LNG, LPG, coal, metals, carbon |
 Detailed Word Document
Provides a concise SWOT assessment of Vitol Holding B.V., highlighting its market-leading trading scale and integrated supply chain strengths, operational and regulatory weaknesses, growth opportunities in energy transition and emerging markets, and threats from geopolitical volatility and commodity-price and regulatory risks.

 Customizable Excel Spreadsheet
Delivers a concise SWOT matrix highlighting Vitol Holding B.V.’s strengths in global trading and logistics, weaknesses such as regulatory and reputational exposure, opportunities from energy transition and diversification, and threats from commodity price volatility—enabling rapid strategic alignment and decision-making.
Trading revenues and asset utilization at Vitol, which trades roughly 7 million barrels per day, depend directly on commodity price moves and spreads; sharp reversals have in past cycles compressed margins despite hedging. Basis risk and liquidity gaps in specific crude and product markets can amplify losses. Prolonged low volatility reduces arbitrage and trading opportunities.
Operating across 40+ jurisdictions, Vitol's global scale (reported group turnover of $505 billion in 2023) exposes it to complex, shifting rules. Sanctions, reporting and market-conduct requirements inflate compliance costs and staffing needs. Compliance failures can trigger fines or trading restrictions, adding operational friction and material legal risk.
Terminals, refineries and upstream positions demand heavy capital and ongoing upkeep, exposing Vitol to high fixed-cost bases despite being the world’s largest independent energy trader with reported turnover of $505 billion in 2022. Operational outages or accidents can halt flows and compress returns quickly. Asset values are highly cyclical and sensitive to policy shifts, and concentrated bets in select assets can magnify downside risk.
Limited disclosure complicates stakeholder assessment, can heighten counterparty due diligence and was linked to wider credit spreads for some traders during 2022–24 market stress, raising potential funding costs.
Vitol's core role as a leading oil trader (handling roughly 7 million barrels per day) links it directly to fossil fuels, drawing sustained criticism from investors, NGOs and regulators; high-profile environmental incidents in the sector can quickly erode its brand equity and access to financing. With global passenger EV share rising to about 14% in 2024 and corporate buyers shifting to lower-carbon suppliers, demand trends and ESG-driven capital constraints can limit growth in traditional trading and refining segments.
Vitol's trading margins (≈7 million bpd) are highly cyclical and exposed to basis, liquidity and volatility collapses that compress earnings. Global scale (reported turnover $505bn in 2023; operations in 40+ jurisdictions) raises compliance, sanction and litigation risk. Large, capital‑intensive assets amplify downside when prices or policy shift; private status reduces transparency and can raise funding costs.
| Metric | Value |
|---|---|
| Throughput | ≈7,000,000 bpd |
| Turnover | $505bn (2023) |
| Jurisdictions | 40+ |
| EV global passenger share | ≈14% (2024) |
This is the actual SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full SWOT report you'll get, covering Vitol Holding B.V.'s strengths, weaknesses, opportunities, and threats. Once purchased, you'll receive the complete, editable file ready for use in presentations or further analysis.
Growth in LNG (global trade up ~10% in 2023), LPG, biofuels and renewable power (≈420 GW new capacity added in 2023) plus expanding carbon markets create new trading lanes Vitol can exploit.
Vitol can scale transitional molecules and certificates, structuring low‑carbon offtakes and guarantees of origin to capture premium spreads.
Early positioning in these markets can convert structural demand into durable market share and recurring trading margins.
IEA World Energy Outlook 2023 indicates the majority of global energy demand growth through 2030 will come from non-OECD markets, driven by urbanization and industrialization across Asia, Africa and Latin America. Building last-mile logistics and storage facilities in these regions deepens Vitol’s physical presence and reduces delivery risk. Tailored financing and integrated supply packages help win long-term offtake contracts with local refiners and traders. This expansion diversifies revenue away from mature markets and captures higher-growth margins.
Data science, AI and automation can sharpen Vitol’s pricing, routing and risk controls, supporting a company that reported roughly $505 billion turnover in 2022; McKinsey finds advanced analytics can boost upstream efficiency by about 3–5%. Real-time visibility cuts demurrage and inventory drag, while analytics tighten credit/counterparty oversight and enable product traceability and ESG reporting at scale.
Acquiring or partnering in underutilized assets can unlock optionality for Vitol, supporting turnaround and debottlenecking projects that boost yields and margins; Vitol reported roughly $505 billion turnover in 2023 and trades about 7 million barrels/day, giving scale to execute such moves. Divest-reinvest cycles and joint ventures let Vitol optimize the portfolio through cycles while sharing execution risk and capital intensity.
Structured financing solutions address producers and consumers seeking working capital and prepayment structures; Vitol, with reported turnover of about $505bn in 2022, can bundle supply, price hedging and credit support to deepen counterparty relationships and secure offtake, while generating fee income alongside trading margins.
Vitol can expand in LNG/LPG/biofuels and renewables (LNG trade +≈10% 2023; +420 GW renewables 2023) to capture new trading and carbon‑market margins. Scaling low‑carbon offtakes, GOOs and structured finance leverages Vitol scale (≈$505bn turnover 2023; ~7m b/d). AI/analytics (3–5% efficiency upside) and asset JVs deepen presence in high‑growth non‑OECD markets per IEA WEO 2023.
| Metric | Value |
|---|---|
| Turnover 2023 | $505bn |
| LNG trade 2023 | +≈10% |
| Renewables added 2023 | ≈420 GW |
| Trade volume | ~7m b/d |
| Analytics upside | 3–5% |
Conflicts, sanctions and route closures can abruptly disrupt trade flows and force Vitol, which trades roughly 330 million tonnes of crude and products annually, into costly rerouting. Sudden reshuffling of barrels increases execution risk and inventory mismatches. Compliance missteps carry severe fines and reputational loss, while freight and war-risk insurance can spike unpredictably, squeezing margins.
Stricter climate policy risks curbing long-term fossil demand as peak oil signals emerge; EU carbon allowances averaged around €100/ton in 2024 and global carbon pricing covered roughly 23% of emissions (World Bank, 2024). Rising carbon costs and GFANZ-driven lender scrutiny (global financial commitments >$150tn) can compress margins and raise capital costs for high-emission hydrocarbon assets.
Vitol faces intense competition from global traders, NOCs, IOCs and utilities all vying for volumes and assets across a market servicing roughly 100 million barrels per day (IEA, 2023); Vitol reported $505 billion in turnover in 2022. Crowded trades can compress margins, while competitors with captive production or retail networks retain structural advantages in securing feedstock and markets. Competition for trading and technical talent is elevating compensation and hiring costs.
Counterparty and liquidity risk: customer defaults rise in stressed markets, margin calls and collateral needs can surge with volatility, and liquidity squeezes can force de-risking at unfavorable levels; Vitol, trading an estimated 6–7 million bpd in industry estimates (2023–24), faces amplified exposure from concentration in key counterparties.
Extreme weather threatens Vitol terminals, shipping routes and power assets, with global insured natural catastrophe losses around $120bn in 2023, raising outage and repair costs. New IMO carbon intensity and fuel standards (effective from 2023 onward) and tighter fuel specs push operating costs higher. Insurance availability is tightening and reinsurance pricing rose about 15% in 2023–24, increasing premium risk and potential spillover into price and basis volatility.
Geopolitical shocks, sanctions and route closures can force costly rerouting of Vitol’s ~330 Mtpa crude/products, raising execution and inventory mismatch risk. Carbon policy and lender scrutiny (EU EUA ~€100/t in 2024; GFANZ >$150tn) threaten demand and capital costs. Competition, counterparty/ liquidity stress and rising insurance/reinsurance costs (reinsurance +≈15% 2023–24) compress margins.
| Metric | Value |
|---|---|
| Annual traded volume | ~330 million tonnes |
| Turnover (Vitol 2022) | $505bn |
| EU EUA avg (2024) | ~€100/ton |
| Insured catastrophe losses (2023) | ~$120bn |
| Reinsurance pricing change (2023–24) | +≈15% |


