
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Cover political, economic, social, technology, legal and environmental change.
Separate market signals from their business impact.
Create a structured view of opportunities and exposure.
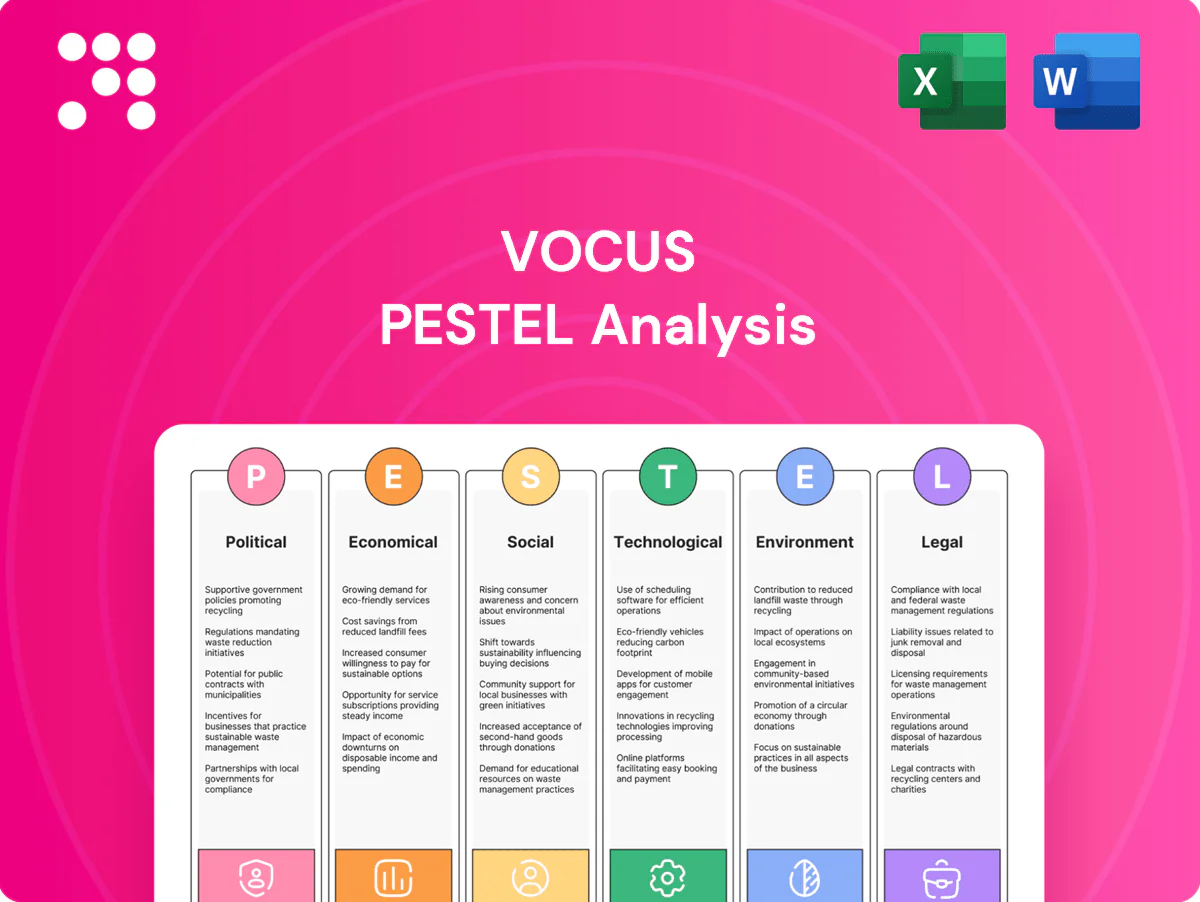
Discover how political, economic and technological forces are reshaping Vocus's strategy and market position. Our PESTLE distills complex external risks and opportunities into actionable insights for investors and strategists. Buy the full analysis to access the complete breakdown and ready-to-use recommendations.
Australia and New Zealand prioritize broadband, regional connectivity and cyber resilience; Australia’s NBN fixed-line network passes about 11.6 million premises and New Zealand’s UFB has passed roughly 1.2 million premises, while government grants and policy support accelerate fiber builds and submarine routes; alignment with national strategies unlocks public contracts and co-investment, though policy shifts or election cycles can reweight timelines and funding priorities.
Secure networks for agencies and defence shape Vocus’s product and accreditation roadmap, driven by Australia’s defence budget of about A$53.6bn in 2024–25 which elevates demand for hardened comms. Winning whole‑of‑government panels offers stable multi‑year revenue streams and predictable contract pipelines. Stringent sovereignty and security rules increase implementation costs but raise barriers to entry, while budget cycles and geopolitics accelerate or delay project pacing.
Telecom assets in Australia and New Zealand are subject to FIRB and OIO screening and oversight by critical infrastructure regulators, so ownership changes, data-routing arrangements and subsea link control commonly trigger formal approvals. Compliance with these reviews adds procedural time and substantial documentation to expansion and M&A processes. Heightened geopolitical tensions have driven regulators to apply stricter standards and closer scrutiny of cross-border deals.
Indo-Pacific tensions constrain cable landing rights, route diversity and repair permissions, with over 95% of intercontinental data reliant on subsea cables; repairs typically take 30–45 days, so diplomatic disruption can stall permits and spares logistics. Political risk raises insurance and contingency design costs and government-backed corridors (state-sponsored projects) de-risk long‑haul investments.
Public policy pushes affordable, open access to essential connectivity, increasing risk of mandated wholesale terms or structural separation that could limit Vocus’s retail pricing power and compress margins.
Programs supporting rural connectivity often require participation in uneconomic areas with government subsidies and contract obligations that affect network rollout costs.
Regulatory shifts in 2024–25 can rapidly recalibrate wholesale pricing, access obligations and EBITDA sensitivity for infrastructure players like Vocus.
Australia/NZ policy prioritises fibre and cyber resilience—NBN ~11.6m premises, NZ UFB ~1.2m—while 2024–25 defence spend A$53.6bn drives secure-network demand. FIRB/OIO and stricter geo‑politics heighten M&A scrutiny; >95% intercontinental traffic on subsea cables with 30–45 day repairs raises insurance and redundancy costs. Wholesale/open‑access mandates and 2024–25 regulatory shifts threaten margin pressure.
| Metric | Value |
|---|---|
| NBN reach | ~11.6m premises |
| NZ UFB reach | ~1.2m premises |
| Defence budget | A$53.6bn (2024–25) |
| Subsea reliance | >95% |
| Repair window | 30–45 days |
 Detailed Word Document
Explores how external macro-environmental factors uniquely affect Vocus across six dimensions—Political, Economic, Social, Technological, Environmental, and Legal—with data-backed trends and region-specific examples to identify risks and opportunities for executives and investors.

 Customizable Excel Spreadsheet
A concise, visually segmented PESTLE summary for Vocus that’s easily dropped into presentations or shared across teams, enabling quick alignment and focused discussion on external risks and market positioning.
Enterprise and government ICT budgets track GDP and confidence—IMF 2024 global growth was 3.1%, with many APAC economies around 2% implying budget sensitivity. Slowdowns can defer discretionary upgrades, yet resilient connectivity remains non‑discretionary. Ongoing digital transformation and cloud adoption (public cloud ~US$600bn market in 2024) sustain baseline demand and push wholesale, high‑capacity services as cost‑saving, counter‑cyclical options.
Network builds are capex‑intensive and sensitive to interest rates; Australia’s cash rate averaged about 4.3% through 2024, raising financing costs for Vocus’ fibre and data‑centre projects. Inflation averaged roughly 4% in 2024, lifting labour, materials, energy and maintenance costs. Price indexation in contracts can partially offset these pressures. Rate cuts or stability in 2025 could reopen windows for expansionary projects.
Cross‑Tasman operations expose Vocus revenues and costs to AUD/NZD volatility, with the AUD/NZD rate averaging near 1.08 in 2024 and remaining volatile into H1 2025, amplifying translation risk across the group. Subsea equipment and many vendor contracts are typically USD‑priced, so USD strength raises capex and OPEX in local currencies. Vocus hedging choices directly influence margin stability and the timing of network investments. FX swings can quickly shift Vocus’s pricing competitiveness versus global carriers.
Carrier consolidation reshapes backhaul and transit pricing dynamics, tightening supplier leverage and increasing negotiation on capacity contracts. Competitive pressure can compress ARPU while stimulating volume growth across enterprise and wholesale segments. Long-term IRUs and anchor tenants provide predictable revenue streams and stabilize cash flows, while scale economies in operations drive margin leverage.
Enterprise shifts to SaaS, IaaS and interconnectivity raise demand for high‑bandwidth, low‑latency links and multi-cloud networking; Flexera 2024 reports 92% of enterprises use multi‑cloud, driving SD‑WAN and upsell opportunities. Economic uncertainty can elongate sales cycles while expanding demand for managed services and Opex models. Data gravity rewards carriers with dense peering and data‑centre adjacency.
Vocus demand tracks GDP and ICT spend—IMF 2024 global growth 3.1% and public cloud ~US$600bn sustain baseline. Higher rates (AU cash rate ~4.3% in 2024) and ~4% inflation raise capex/OPEX; FX (AUD/NZD ~1.08) and USD‑priced kit amplify cost risk. Carrier consolidation compresses ARPU but boosts volume; 92% enterprises use multi‑cloud (Flexera 2024).
| Metric | 2024 |
|---|---|
| Global GDP growth | 3.1% |
| Public cloud | US$600bn |
| AU cash rate | 4.3% |
| Inflation (AU) | ~4% |
| AUD/NZD | 1.08 |
The Vocus PESTLE Analysis preview shown here is the exact document you’ll receive after purchase—fully formatted and ready to use. This is a real screenshot of the finished file, with no placeholders or teasers. The content, layout, and structure visible are exactly what you’ll download immediately after payment.
Workplace flexibility drives higher demand for reliable last‑mile connectivity and secure remote access, with a 2024 Gartner survey reporting about 69% of CIOs prioritizing hybrid connectivity solutions. Enterprises increasingly require scalable VPN, SD‑WAN and QoS to support distributed teams and maintain SLA performance. Service reliability and support responsiveness are now clear brand differentiators, affecting churn and ARPU. Network designs must absorb uneven peak patterns from dispersed users.
Public expectations for universal access pressure carriers like Vocus to extend reach, with an estimated 900,000 regional and remote Australians still under-served as of 2024. Rural and indigenous communities repeatedly highlight coverage and affordability gaps that harm social and economic participation. Partnering on government programs (A$1.5bn+ commitments to regional connectivity initiatives by 2024) can build goodwill and footprint. Tailored, low-cost plans and wholesale models at accessible price points increase adoption and ARPU potential.
High-profile breaches have raised customer sensitivity to data handling—IBM's 2024 Cost of a Data Breach report cites an average global breach cost of US$4.45m, amplifying scrutiny on providers. Buyers now demand demonstrable controls, ISO/IEC certifications and transparency in incident reporting. Managed security bundles are increasingly bundled into connectivity offers as the global managed security market (≈US$40.8bn in 2023) grows. Trust and security posture materially drive long-term enterprise retention.
Customer outage intolerance pushes enterprise customers toward redundant paths and explicit SLAs; industry benchmark expectations hover around 99.9% uptime and Vocus (ASX: VOC) promotes metro/regional fibre redundancy to meet this demand.
Proactive incident updates and <1–4 hour> restoration targets shape reputation and NPS; self-service portals with analytics increase perceived control and directly influence churn rates.
Enterprises increasingly favor providers with credible ESG practices; over 90% of S&P 500 now publish sustainability reports, shaping RFP shortlists and procurement. Reporting on emissions, workforce diversity and community impact directly influences contract awards, while energy-efficient networking addresses concerns that data centers consume roughly 1% of global electricity. Strong social license eases permits and local partnerships.
Workplace flexibility and hybrid work (69% CIOs prioritising hybrid connectivity in 2024) drive demand for SD‑WAN, VPN and resilient last‑mile. 900,000 regional Australians remain under-served, pushing A$1.5bn+ government programs and rural pricing models. Security sensitivity (US$4.45m average breach cost 2024) and ESG reporting (>90% S&P500) shape procurement and retention.
| Metric | Value |
|---|---|
| CIOs prioritising hybrid (2024) | 69% |
| Underserved Australians (2024) | 900,000 |
| Govt regional commitments | A$1.5bn+ |
| Avg breach cost (2024) | US$4.45m |
Coherent optics now support commercial 800G wavelengths and 112–120Gbaud developments, while spectrum optimization and advanced modulation lift per-fiber capacity substantially. Open line systems allow multi-vendor pluggables and faster field upgrades, reducing upgrade cycle times. ROADM platforms with automation cut provisioning from weeks to hours and materially lower OPEX per bit. Ongoing CAPEX keeps Vocus competitive on latency and scale.
Mobile densification drives scalable fiber backhaul/fronthaul demand as 5G connections approach 1.9 billion by 2025; edge compute and caching push traffic into metro rings, with the edge market forecast near US$30B by 2025. Strategic partnerships with MNOs and data centers unlock new ARPU and wholesale revenue, while sub-microsecond synchronization and timing precision become critical for service SLAs.
SD‑WAN adoption (global market ~USD 4.8B in 2023) drives agility and lowers WAN costs; integrated SASE platforms (SASE market expanding fast into 2025) meet zero‑trust mandates while reducing breach risk. Orchestration and APIs cut provisioning time substantially, enabling customer self‑service; differentiation for Vocus rests on platform breadth and depth of managed services.
AI-driven fault detection and route diversity cut mean-time-to-repair and reduce downtime, supporting Vocus (reported FY24 revenue A$1.6bn) as new APAC landings expand reach and redundancy; predictive maintenance improves repair windows and spares logistics, while consortium partnerships distribute risk and capex across networks. Global subsea investment was about US$10bn in 2023, boosting resilience.
Direct cloud interconnects to hyperscalers reduce latency and egress fees for Vocus customers, improving real-time SaaS and VoIP performance while lowering operational costs. Participation in internet exchanges boosts content delivery and SaaS responsiveness across Australia and NZ. Multi-cloud fabrics give enterprises flexibility and regulatory segmentation for data sovereignty. Proximity of Vocus data centers to core metro markets forms a durable competitive moat.
Coherent 800G optics, 112–120Gbaud and ROADM automation raise per‑fiber capacity and cut OPEX; open line systems shorten upgrade cycles. 5G connections ~1.9B by 2025 and a ~US$30B edge market (2025) drive dense metro fiber and APAC landings. Direct cloud interconnects, SD‑WAN (USD4.8B 2023) and AI fault detection lower latency, costs and MTTR while Vocus reported FY24 revenue A$1.6bn.
| Metric | Value |
|---|---|
| Coherent optics | 800G / 112–120Gbaud |
| 5G connections (2025) | ≈1.9B |
| Edge market (2025) | ≈US$30B |
| SD‑WAN (2023) | USD4.8B |
| Subsea investment (2023) | US$10B |
| Vocus FY24 revenue | A$1.6bn |
Operating certifications and carrier obligations govern Vocus services, with regulators enforcing licence conditions that can trigger fines and service restrictions for non-compliance. Periodic audits by regulators and partners require robust governance, detailed documentation and evidence trails to avoid sanctions. The scope and geography of telecom licences directly constrain product rollouts and expansion planning.
Australia’s Privacy Act and the Notifiable Data Breaches scheme (effective 2018) and New Zealand’s updated Privacy Act (2020) plus 2021 reforms to critical infrastructure law shape data handling and incident reporting; Optus’s 2022 breach exposed about 9.8 million customers, underlining risks. Mandatory breach notification drives operational readiness and disclosure timelines. Sector-specific government data rules impose residency and sovereignty controls for classified datasets. Contracts must embed security controls, audit rights and SLA penalties to meet regulatory and procurement mandates.
ACCC and NZ Commerce Commission oversight shapes Vocus pricing and interconnection, with ACCC civil penalties for corporations up to A$50 million reinforcing regulatory scrutiny. Anti-competitive conduct risks injunctions, remedial orders and heavy fines that can materially affect margins. Mergers and major contracts routinely face market-power review, constraining consolidation. Compliance drives network-sharing and peering strategies to manage regulatory and commercial risk.
Permits govern ducting, trenching, towers and cable landing stations, requiring local council, state and sometimes federal sign‑off. Cultural heritage protections and mandated community consultation add statutory steps and can trigger surveys or negotiated agreements. Non‑compliance can halt builds and inflate budgets; early engagement reduces approval risk and shortens timelines.
Operating licences, privacy laws (Aus Privacy Act, NDB 2018; NZ Privacy Act 2020) and mandatory breach reporting (eg Optus 2022 ~9.8M affected) drive compliance costs and disclosure timelines. ACCC/NZCC oversight and A$50M civil penalties constrain pricing and M&A. WHS fines up to AUD 3,000,000 increase contractor controls; permits and heritage rules delay builds.
| Risk | Metric/Stat |
|---|---|
| Optus breach | ~9.8M customers (2022) |
| ACCC max penalty | A$50,000,000 |
| WHS corporate max | AUD 3,000,000 |
Networks and data equipment are power‑intensive: data centers consume about 1% of global electricity and the ICT sector contributes roughly 2–3% of global CO2e. Investing in efficient optics and advanced cooling can cut site energy use by up to 30%, lowering OPEX and emissions. Power purchase agreements with renewables increasingly back corporate targets, and energy reporting is now commonly required in RFPs.
Floods, fires and storms increasingly threaten terrestrial and subsea assets, and IPCC 2023 confirms rising frequency of extreme weather events. Route diversity, hardening and rapid restoration plans are critical for operators like Vocus, which maintains over 30,000 km of fiber across Australia and New Zealand. Maintaining inventories of spares and mobile units shortens mean time to repair and improves uptime. Resilience now differentiates service in volatile climates.
Measuring Scope 1–3 emissions provides Vocus with the data-driven roadmap to prioritize reductions across operations, upstream suppliers and customer use; this baseline is essential for credible targets. Engaging suppliers and adopting circular procurement reduces upstream Scope 3 exposure and material costs while extending asset life. Committing to science-based targets strengthens stakeholder credibility and can lower borrowing costs. Transparent ESG reporting influences financing terms and investor demand.
Global e-waste reached 57.4 Mt in 2021 with a formal recycling rate of 17.4% (Global E-waste Monitor 2024); equipment turnover creates clear disposal obligations for Vocus. Refurbish, redeploy and recycle programs lower waste and procurement costs while vendor take-back and certified recyclers reduce legal and contamination risk. Asset-tracking strengthens compliance and ESG disclosures.
Subsea routes must avoid sensitive marine habitats and protect fishing activity, noting FAO reports 58.5 million people employed in fisheries and aquaculture (2020), making disruption economically and socially material. Land builds face biodiversity, noise and community concerns that raise permitting complexity. Robust environmental assessments increase upfront cost but materially de-risk long-term liabilities, while best-practice construction improves stakeholder acceptance.
Networks consume ~1% global electricity; ICT emits 2–3% CO2e; efficiency and renewables cut OPEX and emissions. Extreme weather (IPCC 2023) threatens Vocus's ~30,000 km fiber; resilience and spares shorten MTTR. Global e‑waste 57.4 Mt (2021), 17.4% recycled; circular procurement and SBTs lower Scope 3 and financing risk.
| Metric | Value | Relevance |
|---|---|---|
| Electricity share | ~1% | OPEX/emissions |
| ICT CO2e | 2–3% | Reg/targets |
| Fiber length | ~30,000 km | Exposure to weather |
| E‑waste | 57.4 Mt; 17.4% recycled | Disposal risk/cost |


