
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Wawa’s resilience stems from a loyal customer base, strong convenience-store footprint, and supply-chain integration, yet it faces competition, real estate constraints, and regulatory risks. Want deeper, research-backed insights and strategic recommendations? Purchase the full SWOT analysis for a professionally formatted Word report and editable Excel matrix to plan, pitch, or invest with confidence.
Wawa's iconic regional brand loyalty, supported by over 1,100 stores across the Mid-Atlantic, Florida and DC, drives repeat visits and resilient traffic in core markets. Strong brand equity delivers pricing power on signature hoagies and coffee, supporting higher margins versus generic c-stores. Community presence and word-of-mouth lower customer acquisition costs, translating into consistently stable same-store sales in recent years.
Made-to-order hoagies, breakfast and beverage programs differentiate Wawa from typical c-stores and drive repeat traffic across its network of over 1,100 stores (2024). Perceived freshness lifts basket size and margins versus packaged goods, supporting higher spend per visit. Customization enables premium pricing and upsell on add-ons, while optimized kitchen workflows sustain rapid throughput during peak dayparts.
Co-located fuel, fresh food, coffee and surcharge-free ATMs at Wawa’s network of over 1,000 stores maximize trip capture by serving multiple missions—commute, lunch and grocery top-ups—boosting basket size and visit frequency. High forecourt traffic funnels customers into the store, increasing impulse and prepared-food sales. Many locations operate 24/7, extending hours and amplifying asset utilization and revenue per site.
Wawa's mobile app, in-store kiosks and Wawa Rewards streamline ordering and enable personalized, targeted offers that increase visit frequency and attachment across its 1,100+ stores; frictionless payments speed service while transaction data sharpens merchandising and labor planning for peak periods.
Operational efficiency at Wawa is driven by standardized store formats and processes that support consistent quality across a network of over 1,100 stores (2024) and a company history since 1964. Scale in procurement lowers COGS on core categories through centralized sourcing, while fast service reduces abandonment and queuing friction. Continuous menu innovation and rotating offerings sustain customer interest and repeat visits.
Wawa's iconic regional brand and 1,100+ stores (2024) drive strong repeat visits and resilient same-store traffic in Mid-Atlantic, Florida and DC. Made-to-order hoagies, coffee and co-located fuel/ATMs lift basket size and margins versus typical c-stores. Mobile app, kiosks and Wawa Rewards increase frequency and operational efficiency across the network.
| Metric | Value |
|---|---|
| Stores (2024) | 1,100+ |
| Founded | 1964 |
| Core regions | Mid-Atlantic, FL, DC |
 Detailed Word Document
Delivers a strategic overview of Wawa’s internal and external business factors, outlining strengths, weaknesses, opportunities, and threats to assess competitive position and future growth risks.

 Customizable Excel Spreadsheet
Delivers a concise, visual SWOT matrix tailored to Wawa for rapid strategy alignment and stakeholder-ready summaries; editable format enables quick updates as market priorities shift, relieving time pressure on strategic planning.
Heavy reliance on a limited regional footprint—over 1,000 stores concentrated in the Mid‑Atlantic and Florida (eight states plus Washington, D.C.)—heightens market risk; local economic or regulatory shocks can disproportionately impact results, brand awareness remains weaker outside core states, and expansion demands substantial capital expenditure and operational bandwidth.
Made-to-order kitchens demand more staffing and training, raising labor intensity; restaurant labor costs average about 30% of sales (National Restaurant Association). Wage inflation (BLS: average hourly earnings up 4.4% in 2024) plus complex scheduling squeeze margins. High industry turnover (~70% annually, NRA 2023) risks service inconsistency and higher hiring costs. Peak-period bottlenecks can degrade customer experience.
Profitability is highly sensitive to wholesale price swings and competitive pump pricing, with fuel often representing a major traffic driver for Wawa’s ~1,200 stores (2025); industry fuel margins can swing by tenths of a dollar per gallon, compressing total store contribution. Compressed fuel margins reduce funds available for grocery/food gross margin support and create cross-subsidization pressure that can constrain promotions. Ongoing environmental compliance and cleanup costs (site-specific, often hundreds of thousands of dollars) add recurring overhead.
Wawa's drive-thru footprint lags QSR rivals in a market where drive-thru captures over 50% of quick-service transactions (QSR industry data 2023–24), limiting throughput and on-the-go convenience during peak dayparts. Retrofitting existing stores faces zoning, parcel and queuing constraints that raise capex and timelines, eroding share in breakfast and late-night occasions.
Wawa's broad customization and frequent LTOs expand SKU count and training needs, straining operations across its ~1,100 stores (2024). Greater complexity lengthens prep times and raises food waste; rotating seasonal offers increase consistency risk. Forecasting errors for perishables can cause out-of-stocks or spoilage, pressuring margins.
Wawa's regional concentration (>1,100 stores, 2024) raises market and expansion risk; brand reach is limited outside the Mid‑Atlantic/Florida. Labor intensity from made‑to‑order kitchens and high turnover (~70% NRA 2023) plus wage growth (avg hourly earnings +4.4% 2024) compress margins. Fuel margin volatility and lagging drive‑thru adoption (>50% QSR drive‑thru share) constrain traffic and profitability.
| Metric | Value | Impact |
|---|---|---|
| Stores | >1,100 (2024) | Regional risk |
| Turnover | ~70% (NRA 2023) | Training costs |
| Wage growth | +4.4% (2024) | Margin pressure |
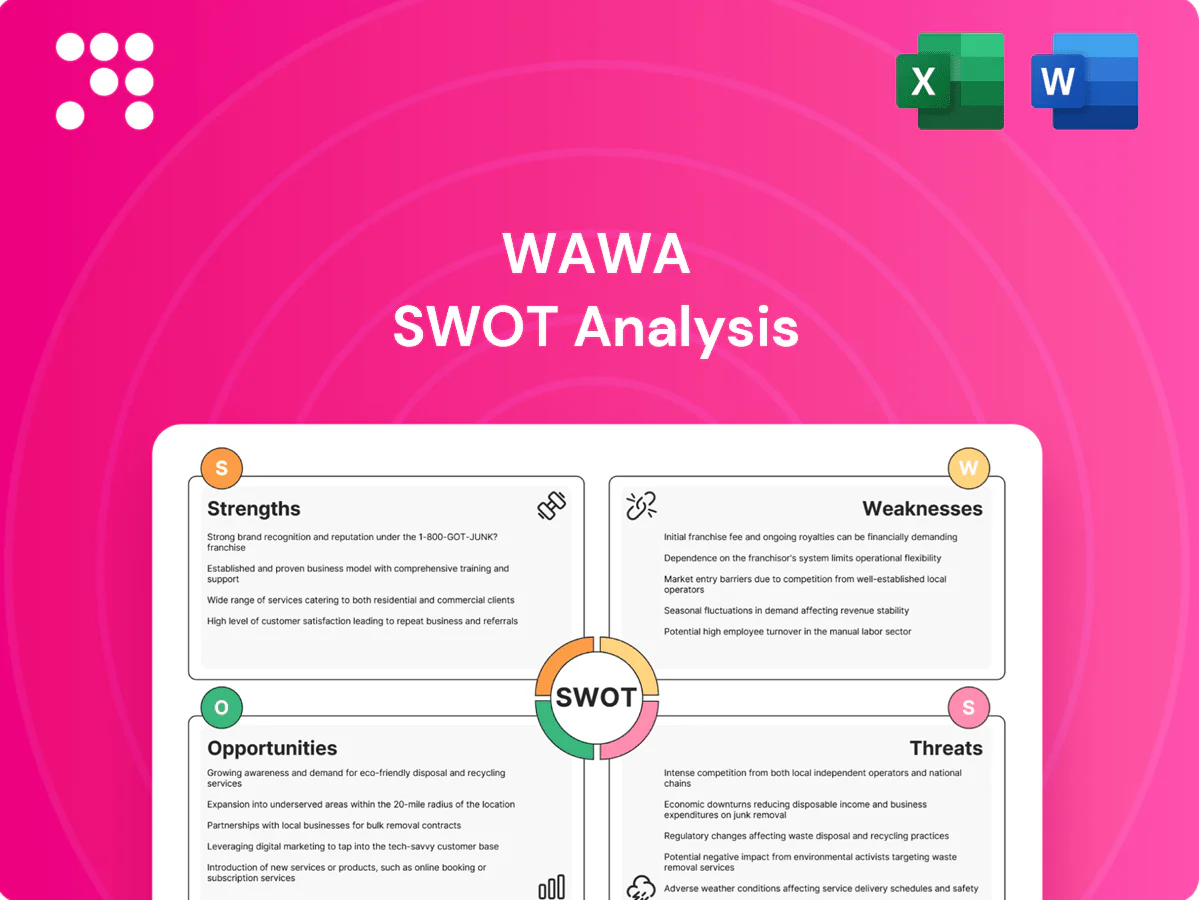
This is the actual Wawa SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full SWOT report you'll get, and purchase unlocks the entire in-depth, editable file. Buy now to download the complete, ready-to-use analysis.
Entering adjacent states can expand Wawa’s addressable market beyond its current footprint of more than 1,000 stores across seven states and Washington, D.C., diluting regional risk tied to Northeast weather and local economic cycles.
Site selection near highways and growing suburbs lets Wawa replicate its high-volume convenience model and capture commuter and family traffic patterns.
Pre-opening buzz leverages strong regional brand fandom and social media to drive opening-week traffic, while clustered store strategies cut logistics costs and improve marketing efficiency.
Scaling drive-thru can unlock QSR-like throughput and convenience, reducing in-store congestion and matching industry off-premise trends where over 50% of visits are off-premise (NPD, 2023–24). Curbside and delivery partnerships capture incremental demand and extend reach beyond peak dayparts. Dedicated makelines protect in-store speed and order accuracy. Incremental channels diversify revenue across morning, lunch, and evening dayparts.
Fast 150–350 kW charging hubs keep Wawa relevant as US EV new sales rose to ~12% in 2024; 20–40% longer dwell times drive 20–40% higher in-store spend and higher-margin purchases. Utility incentive programs can offset up to ~50% of capex, and early movers report 10–25% site traffic and loyalty gains.
Expanding Wawa-branded beverages, snacks and meal kits can lift gross margins through higher private-label pricing and cost control, leveraging Wawa’s scale across over 1,100 stores (2024).
Offering catering for offices, events and tailgates increases average ticket sizes and repeat revenue, while bundled offers boost attachment rates for sides and beverages.
Strong brand trust and Wawa Rewards drive trial and faster SKU adoption, shortening payback on new product investment.
Loyalty data from Wawa Rewards can drive targeted offers and menu-mix optimization across Wawa’s network of over 1,000 East Coast stores; dynamic pricing and daypart promotions can lift utilization; predictive labor and inventory tools cut waste and wait times; geo-targeting enables localized assortments and faster new-store ramps.
Expanding into adjacent states and highway/suburb corridors leverages Wawa’s 1,100+ stores (2024) to reduce regional concentration risk and capture commuter/family traffic. Scaling drive-thru, curbside and delivery taps a market where >50% of visits are off-premise (NPD 2023–24) and lifts daypart revenue. Fast 150–350 kW EV hubs (US EV share ~12% in 2024) and private-label expansion can raise spend and margins.
| Opportunity | Metric/Impact |
|---|---|
| Store footprint | 1,100+ stores (2024) |
| Off-premise demand | >50% visits (NPD 2023–24) |
| EV traction | US EV new sales ~12% (2024); +20–40% dwell/spend |
| Incentives | Utility programs can offset ~50% capex |
Regional rivals Sheetz (~650 stores), QuikTrip (~1,100 stores) and expanding Buc-ee’s (50+ locations) plus national 7-Eleven (14,000+ US stores) aggressively contest Wawa’s share. QSRs and grocers increasingly take prepared-food and coffee spend, pressuring in-store margins. Fuel price wars compress pump margins and can erode overall profitability. New entrants and specialty chains fragment consumer attention and loyalty.
Rising labor mandates raise costs for Wawa’s roughly 1,100 stores: the federal minimum remains $7.25 but dozens of state and local increases and stricter scheduling and overtime rules have pushed payroll expenses materially higher. Food safety (FSMA), labeling and state environmental standards increase compliance complexity and capex. Fuel and emerging EV pump regulations and charging mandates can force costly site retrofits. Regulatory fines or safety incidents risk significant brand damage and revenue loss.
Persistent inflation — US CPI averaged roughly 3% in 2024 (BLS) — can compress spending on Wawa's premium coffee and prepared foods, while recessionary pressure cuts discretionary trips and basket size. Food-at-home prices rose about 2.6% YoY in 2024, and volatile commodity costs (dairy, meat, fuel) squeeze food margins. Higher financing costs from a fed funds rate near 5.25–5.50% in mid‑2025 raise development and expansion expenses.
Supply chain disruptions can restrict menu availability when shortages of key ingredients or packaging occur, undermining Wawa's ability to serve its ~1,100+ stores. Logistics delays erode freshness and service levels for grab-and-go items. Vendor concentration raises single-point-of-failure risk and cost spikes can force price hikes that suppress customer traffic.
EV adoption (IEA: 14% of new car sales in 2023) and steady efficiency gains cut fuel trips, lowering forecourt footfall and weakening in-store conversion; transition capex for DC fast chargers (~$100k–$350k per site) competes with new-store growth, while Tesla and other rivals expanded fast-charger networks (Tesla >40,000 chargers by 2024) — risk of competitors outpacing Wawa.
Regional and national rivals (Sheetz ~650, QuikTrip ~1,100, 7‑Eleven 14,000+) plus QSRs/grocers erode share and margins. Rising labor mandates, FSMA and fuel/EV regulations boost capex and operating costs. Inflation (US CPI ~3% in 2024) and EV adoption (IEA: 14% of new car sales 2023) reduce forecourt trips and prepared-food spend.
| Metric | Value |
|---|---|
| Wawa stores | ~1,100 |
| Sheetz | ~650 |
| QuikTrip | ~1,100 |
| 7‑Eleven US | 14,000+ |
| US CPI 2024 | ~3% |
| EV new sales 2023 | 14% |
| DCFC cost/site | $100k–$350k |
| Tesla chargers 2024 | >40,000 |


