
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Welspun Living faces moderate supplier power, evolving buyer preferences, rising substitute threats from organized retail and digital-first brands, and variable entry barriers that shape its margin outlook. Our snapshot highlights strategic pressure points and short-term risks to growth. For investors and strategists, deeper force-by-force ratings clarify where value is at risk or can be captured. Unlock the full Porter's Five Forces Analysis for a complete, actionable roadmap.
Welspun’s fiber-to-finish model—spinning, weaving, processing and made-ups—significantly reduces dependency on external suppliers by internalizing critical inputs. Backward integration into cotton yarn and in-house processing curtails vendor pricing power and allows the company to hedge via internal capacity balancing. Supplier influence is also moderated through multi-sourcing strategies and standardized inputs across product lines. This integrated setup strengthens negotiation leverage over raw material vendors.
Cotton, polyester, dyes and chemicals trade globally with cyclical swings—cotton futures moved roughly 15–25% across 2022–24 and polyester feedstock swings were similar—forcing uneven pass‑through into Welspun Living’s contracts; large retail programs allow partial repricing but timing lags compress margins by an estimated 100–200 bps. Futures/hedging provide partial relief but not full protection, and suppliers gain temporary leverage in tight cycles or for premium quality grades.
Requirements for BCI/organic/Egyptian cotton, OEKO-TEX and traceable ESG inputs shrink the qualified supplier pool—organic cotton was only about 1% of global cotton supply in 2024—raising switching costs for specialty fibers and finishes. Compliance audits and traceability systems favor established vendors, while niche inputs like performance finishes further strengthen specialist supplier power.
India (≈36m bales 2023/24), Pakistan (≈6m), Turkey (≈2m) and the U.S. (≈14m) provide diversified cotton and yarn sources, enabling Welspun to switch vendors and limit supplier price leverage. Cross-border alternatives reduce unilateral pricing control, though logistics reliability and lead-time constraints remain critical for on-time retail programs. Dual-vendor strategies are used to balance cost savings with supply assurance.
Energy, water and effluent-treatment dependencies create cost stickiness in processing, constraining margin flexibility; capex-heavy looms, finishing lines and flooring machinery tie buyers to OEMs for spares and proprietary upgrades. Lifecycle service contracts elevate vendor influence episodically, though multi-site procurement and long-term sourcing reduce this over time.
Welspun’s fiber‑to‑finish vertical integration and multi‑sourcing (India 36m bales, US 14m, Pakistan 6m, Turkey 2m in 2023/24) limits supplier pricing power, though tight cycles can compress margins ~100–200 bps. Specialty inputs (BCI/organic ≈1% of cotton supply in 2024) raise switching costs. OEM spares and utility intensity cause episodic vendor leverage.
| Metric | Value |
|---|---|
| Vertical integration | High |
| Cotton supply (2023/24) | India 36m, US 14m, PK 6m, TR 2m bales |
| Organic cotton (2024) | ≈1% global |
| Margin impact in tight cycles | ~100–200 bps |
| OEM lock‑in | Moderate–episodic |
 Detailed Word Document
Uncovers key drivers of competition, customer influence, and market entry risks tailored to Welspun Living, with detailed evaluation of supplier and buyer power. Identifies disruptive substitutes and barriers protecting incumbents to inform strategic decisions.

 Customizable Excel Spreadsheet
A clear, one-sheet Porter’s Five Forces snapshot for Welspun Living—perfect for quick strategic decisions and investor briefings, with customizable pressure levels to reflect new data or market shifts.
Large global retailers and hotel chains such as Walmart (FY2024 net sales $611B) and Target (FY2024 net sales ~$106B) command volume and dictate product specifications, squeezing suppliers on design, pricing and lead times.
Their growing private-label programs intensify vendor compliance and cost-down expectations, pressuring margins as private label captured sizeable retail assortment shares in 2024.
Program renewal risk and strict OTIF/quality regimes—with penalties commonly 1–3% of PO value—heighten buyer leverage and raise supplier switching costs.
Home textiles are highly price-sensitive with visible shelf competition; the global home textiles market was about USD 110 billion in 2024, intensifying cost benchmarking across suppliers. Buyers routinely compare landed cost across India, Turkey and China, and small design differences rarely justify premiums unless backed by IP or verifiable sustainability claims. Aggressive annual rebids sustain downward price pressure on manufacturers like Welspun.
In 2024 complex SKUs, cartonization rules, traceability and in-house testing embed Welspun Living supplier know-how, materially raising operational switching costs. Buyers nonetheless frequently dual-source to mitigate dependency, keeping bargaining power in check. Social and environmental audit compliance is mandatory and resource-intensive for both suppliers and retailers. When switching happens it is staged via planned transitions and small trial orders to validate quality and logistics.
Welspun sells through retail, hospitality, institutional and D2C channels, reducing single-channel dependence, yet top accounts still account for roughly 35% of revenue in 2024, concentrating bargaining power.
Channel diversification improves negotiation stance and price flexibility; direct brands capture higher gross margins and first-party consumer data, supporting better targeting and margin recovery.
Patented moisture-management and quick-dry technologies, distinct design and verified ESG credentials let Welspun shift bargaining leverage toward suppliers by commanding premiums in branded and premium tiers, while co-developed collections with large retailers deepen partnerships and lock in demand; commoditized SKUs, however, remain highly buyer-driven.
Large global retailers (Walmart FY2024 net sales $611B; Target FY2024 ~$106B) and a $110B global home-textiles market (2024) concentrate buyer leverage—top accounts ≈35% of Welspun revenue (2024)—driving price pressure, 1–3% PO penalties and routine dual-sourcing; patented tech, ESG and D2C lift margins but commoditized SKUs remain buyer-driven.
| Metric | 2024 |
|---|---|
| Top-account concentration | ~35% |
| Global market size | USD 110B |
| Retailer scale | Walmart $611B; Target $106B |
| Penalty range | 1–3% PO value |
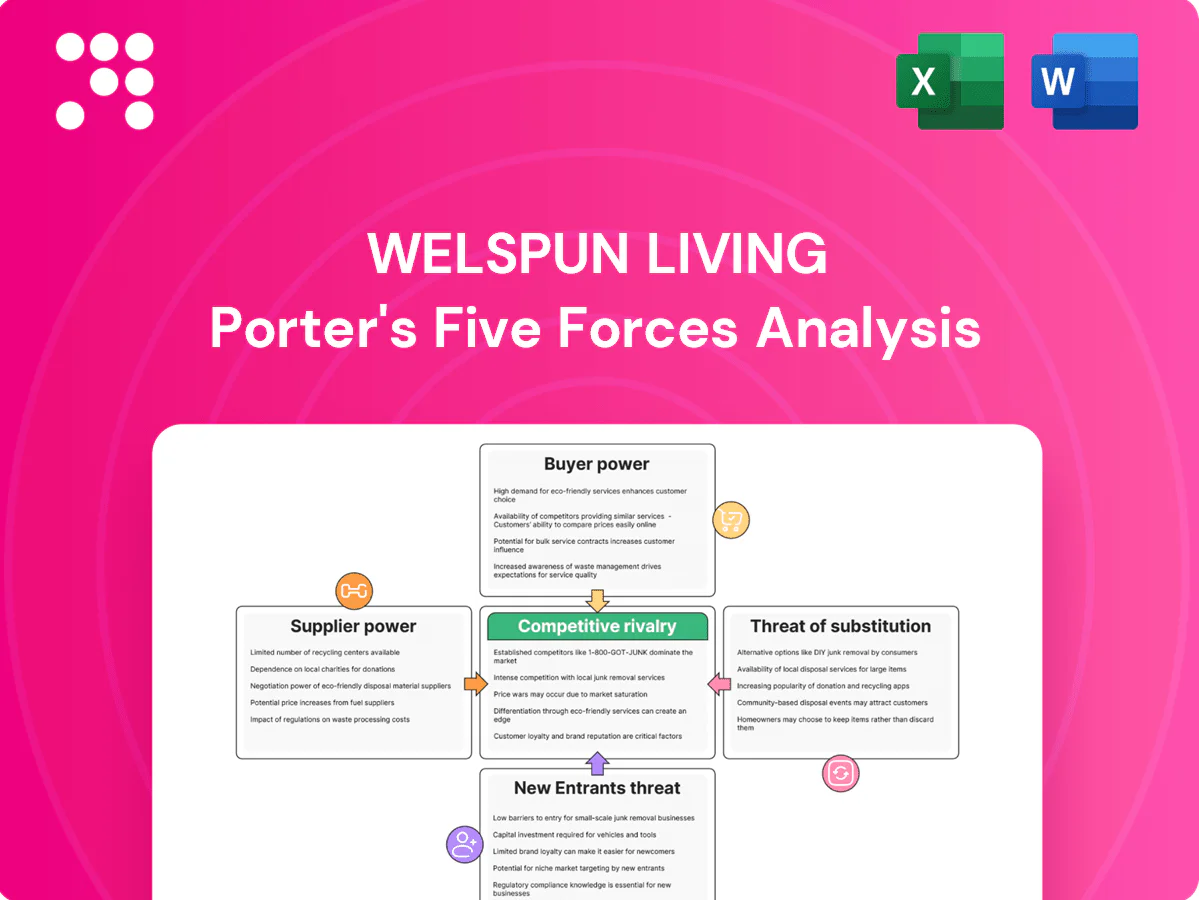
This preview shows the exact Porter’s Five Forces analysis for Welspun Living you’ll receive after purchase—no placeholders or samples. It outlines competitive rivalry, supplier and buyer power, threats of substitutes and new entrants, and actionable strategic implications in a professionally formatted, ready-to-use file. You’ll get instant access to this same document upon payment. Use it immediately for strategy or investment decisions.
Crowded field across India, Pakistan, Turkey and China forces scaled exporters to compete on cost, capacity and reliability, with Indian peers Trident, Indo Count and Himatsingka driving intense price pressure. India’s home-textile exports reached about $3.1bn in FY2024, amplifying competition. Currency swings (rupee ~8% vs USD in 2023) shift share episodically, while shorter lead times and compliance certifications act as tie-breakers.
Bed and bath basics face frequent discounting—promotions can reach up to 50% during demand slowdowns—driving capacity-led price wars in commoditized SKUs. Overcapacity in retail resets amplifies promotional intensity, especially in peak clearance seasons. Annual vendor negotiations commonly see margin pressure of 200–400 basis points. Efficient asset utilization and SKU mix management are critical to protect EBITDA.
Proprietary yarn constructions, performance finishes, and branded programs make Welspun Living products less directly comparable, supporting higher margins and channel exclusives. In 2024 leading retailers tightened sustainable sourcing, so traceable cotton and circularity initiatives secure premium listings. Strong ESG credentials help win preferred-supplier status with major buyers. This differentiation dampens head-to-head price rivalry.
Rugs, carpets and hard flooring pit Welspun Living against specialist global players as the global flooring market reached about $392 billion in 2024, forcing intensified product and price competition; channel dynamics and installation ecosystems differ materially from soft home textiles, raising distribution and service costs. Design cadence and broader collection breadth now drive share gains, while cross-selling into existing retail relationships leverages distribution and average order value.
Buyers can reallocate orders across qualified mills within a season, so on-time delivery, defect rates and responsiveness directly determine allocation; by 2024 retailers commonly enforce OTIF targets around 95% and defect tolerances near 1%, making service levels critical. Digital integration via EDI and vendor portals raises stickiness, while failures rapidly translate into lost shelf space and revenue.
Crowded export market (India exports ~$3.1bn FY2024) forces cost, capacity and reliability battles, with promo discounts up to 50% and annual vendor margin pressure of 200–400 bps. OTIF targets ~95% and defect tolerance ~1% make service levels decisive; EDI integration raises stickiness. Differentiation via proprietary finishes, traceable cotton and ESG reduces pure price rivalry, while flooring (~$392B 2024) invites specialist competition.
| Metric | 2024 |
|---|---|
| Home-textile exports | $3.1bn |
| Global flooring market | $392bn |
| Promo depth | Up to 50% |
| Vendor margin pressure | 200–400 bps |
| OTIF target | ~95% |
| Defect tolerance | ~1% |
Microfiber, rayon/viscose and recycled polyester are replacing cotton in towels and active SKUs as polyester accounted for >60% of global fiber production in 2024 while cotton was ~22%; quick-dry and stain resistance attract price-conscious buyers. Cotton price spikes (roughly +40% in 2021–22) accelerated substitution and margin pressure; premium buyers, however, still favor natural cotton for touch and brand positioning.
Consumers increasingly reallocate home budgets toward furniture, decor or mattresses rather than linens, with the global home furnishings market reaching about $1.1 trillion in 2024, pressuring standalone sheet sales. Mattress-in-a-box brands bundle bedding, cutting separate sheet purchases and capturing a growing share of online mattress buyers. Fashion cycle-driven refresh rates and 2024 macro pressures have elevated trade-downs and purchase deferment.
Hospitality linen rental and outsourcing can reduce hotels' direct linen procurement by 30–40%, shifting capex to opex and lowering inventory needs in 2024. Extended lifecycle management from providers lengthens product life and reduces replenishment frequency, cutting replacement rates by roughly a quarter. Service-level contracts function as functional substitutes to direct purchases, embedding maintenance and replacement costs. Regional penetration varies widely, from low in parts of APAC to high in Western Europe driven by logistics economics.
Functionally adjacent products—quick-dry towels vs plush cotton, blankets vs duvets, and performance throws—pose real substitution risk as consumers balance feel, performance, and care requirements; global home textiles market ~USD 120 billion in 2024, with performance/technical segments growing faster than traditional cotton. Marketing narratives shift perceived value while retailers curate assortments to steer choices and margin outcomes.
Sustainability-led substitutes lengthen replacement cycles as reusable, durable and circular home textiles reduce buy frequency; 2024 surveys show roughly 60% of consumers factor sustainability into home-goods choices. Higher-quality items shift volume toward longevity, while paper/disposable options remain niche and situational. Verified eco-claims materially alter basket composition and premium willingness.
Polyester/technical fibers (polyester >60% of global fiber output vs cotton ~22% in 2024) and quick-dry/performance lines erode cotton margins; price spikes (+~40% cotton 2021–22) accelerated switching. Home-furnishings reprioritisation (global market ~USD 1.1T in 2024) and mattress bundles cut standalone sheet demand. Hospitality linen outsourcing trims hotel procurement 30–40% while ~60% of consumers factor sustainability, lengthening replacement cycles.
| Substitute | 2024 stat | Impact |
|---|---|---|
| Polyester/technical | >60% global fiber | Margin pressure |
| Home bundles | Market USD 1.1T | Lower standalone sales |
| Hospitality outsourcing | 30–40% procurement cut | Reduced replenishment |
| Sustainability | ~60% consumers | Longer lifecycles |
Spinning, weaving, processing and cut-sew demand heavy capex and specialist know-how — integrated mills often operate with ~100,000 spindles and multi-line looms to achieve scale economics. Effluent treatment and compliance create sizable fixed costs (large ETP/CETP links) that raise break-even thresholds. New entrants struggle to match Welspun-level unit costs and face steep learning curves in quality and yield over several years.
Large retailers require rigorous social, quality and sustainability audits—retailers typically expect OTIF performance of 95% or higher and detailed vendor scorecards; laboratory testing protocols add $1–5 per SKU in validation costs. New entrants often endure probationary volumes and earn multi-season trust over 2–3 years, while retail chargebacks and penalties can reach 3–5% of invoice value, deterring inexperienced players.
Long lead times from fibre-to-finished and cotton seasonality (India sowing June–July, harvest Oct–Dec) plus wide SKU breadth strain cash cycles; USDA 2023/24 world cotton production was about 118 million bales, keeping raw-material timing critical.
Exporters face FX volatility (INR–USD swings in 2023–24) so active hedging and working-capital lines are necessary; entrants without financing depth often face acute liquidity stress.
Established players mitigate this with vendor-managed inventory, rolling forecasts and supplier financing to compress days inventory outstanding and sustain margins.
Co-developed programs, patented constructions, and integrated retail-data platforms boost customer stickiness for Welspun Living, raising barriers by embedding product specs into retailer assortments and loyalty programs. Longstanding buyer ties and premium shelf share limit newcomer access, while high-cost marketing and rapid design cadence deter smaller entrants; customized assortments amplify switching costs for large retailers.
Asset-light D2C entrants can contract Welspun’s mills to enter premium niches, but they still face the same compliance, input and export logistics that affect mills serving 100% export-oriented players; Welspun’s global supply-chain scale (over 5,000 retail partner doors in 2024 across brands) keeps switching costs high.
Scaling beyond niche needs capital for inventory and retail acceptance—brand AOVs and CACs for D2C home textiles rose ~15% in 2023–24, making broad expansion capital-intensive, while incumbent price competition can compress margins.
High capex, ETP costs and specialist know‑how create scale thresholds; new mills take years to match Welspun unit costs. Retailers demand ~95% OTIF, testing adds $1–5/SKU and chargebacks run 3–5%, extending probationary volumes for 2–3 years. FX and working‑capital pressure hit entrants; Welspun’s 5,000 retail doors (2024) and co‑development programs raise switching costs. Global cotton supply ~118m bales (2023/24) keeps input timing critical.


