
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
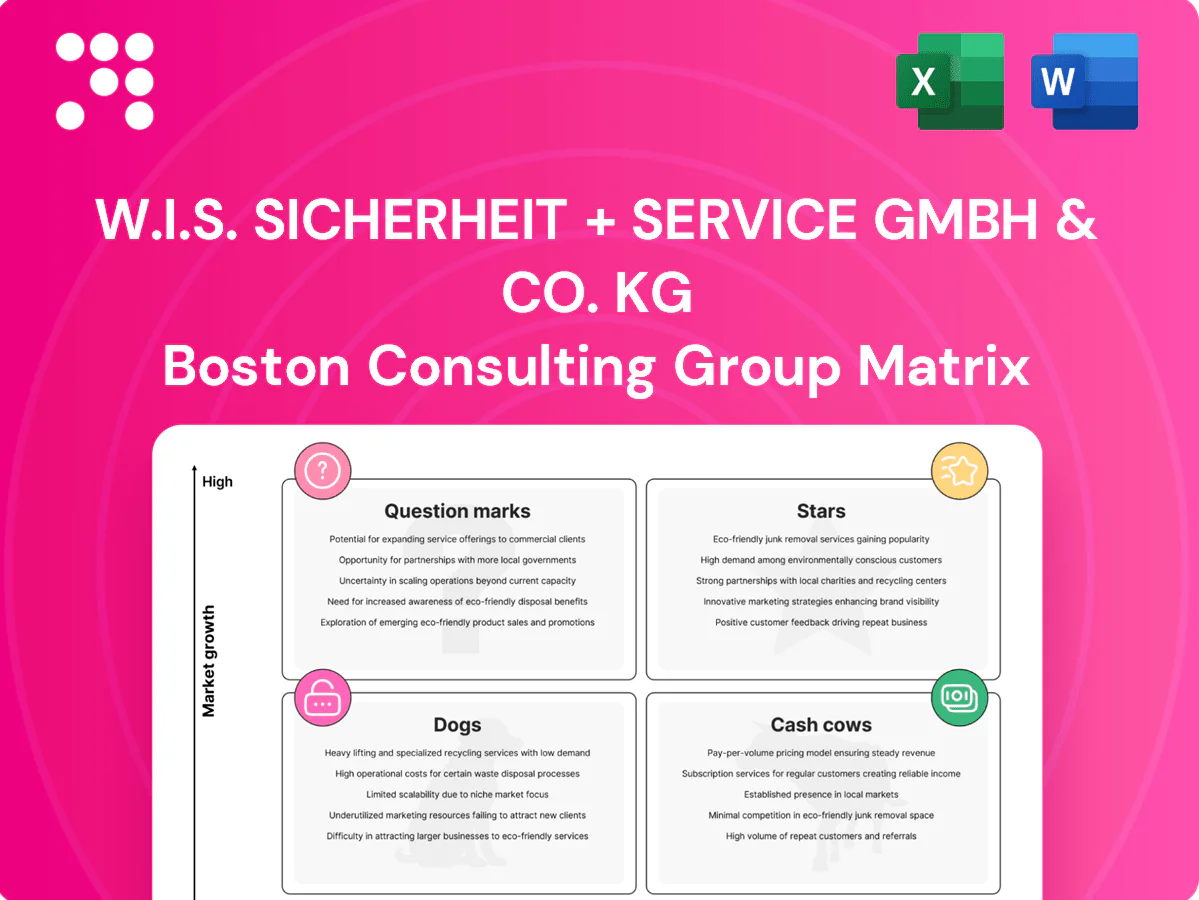
W.I.S. Sicherheit + Service GmbH & Co. KG’s BCG Matrix preview shows where key services sit—some are steady earners, others need investment, and a few may be draining resources. Want the full picture with quadrant-by-quadrant data, actionable moves, and a clear investment roadmap? Purchase the full BCG Matrix for a ready-to-use Word report plus an Excel summary and start making smarter portfolio decisions today.
Integrated guarding + tech bundles sit in the Stars quadrant: high growth, high share as manned guarding paired with installed systems meets client demand for a single provider and faster response; European private security market grew ~5% CAGR through 2021–24 supporting continued expansion.
W.I.S. already executes unified delivery; invest in cross-trained teams and unified SLAs to defend lead and replicate the bundle across major metros before rivals scale.
Urban alarm response demand has climbed as sites automate and compress on-site staffing, positioning W.I.S. cars on the road, tight dispatch and clear SOPs near the front of the pack. The model consumes cash for fleet, scheduling and tech, so continue funneling investment into routing, telemetry and crew utilization. Focused uptime improvements convert growth into repeatable revenues. Nail utilization and this service becomes a Cash Cow as market growth normalizes.
Security tech installation with lifecycle maintenance sits in Stars as retrofit demand for video, access and sensors surged about 15% in 2024 across commercial and industrial sectors, driving outsized TAM growth. W.I.S. captures premium value when it owns both install and ongoing service, converting one‑time CAPEX into recurring revenue. Double down on vendor partnerships, standardized kits and predictable SLAs to scale. Protect margin via structured upgrades and multi‑year maintenance wraps with guaranteed renewal metrics.
Heavy-regulated, high-risk sites increasingly contract comprehensive providers rather than piecemeal vendors; W.I.S. has established credibility in KRITIS sectors (energy, water, health, telecom) and benefits from demand growth after EU NIS2 transposition in 2024. Continue allocating resources to compliance expertise, vetted staffing, and regular incident drills; deeper specialization raises barriers to entry—characteristic of a Star.
Clients prefer single-vendor campus solutions; 2024 pilots show a 62% upsell rate within 12 months as FM security bundles reduce procurement complexity and boost retention. Cross-selling FM with security is scaling, driving double-digit segment growth; invest in integrated scheduling, shared dashboards and account-based ops leads to industrialize land-and-expand before the curve flattens.
Integrated guarding+tech bundles are Stars: high growth/high share—European private security ~5% CAGR 2021–24, retrofit installs +15% in 2024, pilots show 62% upsell in 12 months. Invest cross‑trained teams, fleet telemetry, standardized kits and multi‑year maintenance wraps to lock renewals and scale into metros.
| Metric | 2024 | Implication |
|---|---|---|
| Market CAGR | ~5% | Sustained TAM |
| Retrofit installs | +15% | High retrofit demand |
| Upsell rate | 62% | Land-and-expand |
| NIS2 impact | Transposed Oct 2024 | KRITIS demand |
 Detailed Word Document
BCG Matrix for W.I.S. Sicherheit + Service GmbH & Co. KG: quadrant insights, invest/hold/divest guidance and trend risks.

 Customizable Excel Spreadsheet
One-page BCG matrix for W.I.S. Sicherheit + Service GmbH & Co. KG — quadrant view easing portfolio decisions for C-levels.
Core manned guarding for commercial properties sits in a mature segment with low single-digit market growth (around 1–2% annually in Germany, 2024), stable contracts and industry renewal rates near 90%. It delivers reliable monthly cash flow and predictable EBITDA contribution; focus on quality to keep churn low and avoid costly gold-plating. Incremental tech—rounds tracking, e-learning—can lift margins by ~2–5 percentage points without heavy capex. Preserve service consistency to sustain cash generation.
Preventive maintenance on installed systems delivers steady cash: recurring visits with predictable parts and low capex drive field-service margins while clients prioritize uptime over bells and whistles. Industry studies show preventive programs can cut unplanned downtime by about 25–30%, so standardizing checklists and increasing route density raises billable stops per technician. Upsell small, high-margin upgrades but avoid major capital outlays to preserve return on investment.
Keyholding and scheduled patrols are classic services with a well-known playbook and limited market growth, functioning as BCG cash cows; industry EBITDA for security services hovered around 10% in 2024. Unit economics improve markedly with tight routing and night-shift utilization, cutting cost-per-stop and lifting margins. Use surplus cashflow to feed alarm response operations and technical upsells; milk and maintain rather than reinvent.
Integrated facility services (cleaning, minor FM) are not glamorous but deliver sticky, margin-positive revenue when bundled; in 2024 the German facility services sector showed modest growth near 2% YoY, underscoring contract depth over headline expansion. Maintain operational standards, keep scope clear to avoid scope creep, and use stable cash generation to fund higher-growth bets.
Control room monitoring for legacy systems remains a cash cow with steady volume in 2024 despite aging tech; staffing levels and process discipline are the primary profitability levers. Incremental tooling deployed in 2024 raised operator throughput and reduced incident-handling time, improving margins without heavy capex. Keep operations lean and reserve major investments for next-gen platform rollouts.
Core manned guarding, keyholding, preventive maintenance, integrated FM and legacy control-room monitoring are cash cows: low growth (1–2%/yr Germany, 2024), predictable churn (~10% renewal risk), and steady EBITDA (~10% industry avg, 2024). Tech lifts margins ~2–5ppt; preventive programs cut unplanned downtime 25–30% (2024). Use surplus cash to fund alarm response and next‑gen platforms.
| Service | Growth 2024 | EBITDA 2024 | Key lever |
|---|---|---|---|
| Manned guarding | 1–2% | ~10% | Quality/churn |
| Preventive maintenance | stable | ~10% | Route density |
The BCG Matrix you're previewing for W.I.S. Sicherheit + Service GmbH & Co. KG is the exact file you'll receive after purchase — no watermarks, no demo text, just the finished strategic report. It's crafted for clarity and immediate use, ready to edit, print, or present to stakeholders. Buy once and download instantly; what you see is what you get, formatted by experts for straightforward decision-making.
Standalone hardware resale is commoditized and price-shopped, with 2024 median gross margins near 8% and average price markdowns around 12%, driving little customer loyalty. Inventory carrying costs and warranty administration consume substantial operational time—often 10–15% of after-sales staff capacity—and create cash drag. Without a maintenance wrap, units become a cash trap; recommend divestment or conversion to service-attached-only sales.
Rural alarm responses show travel consuming ~20% of field hours, squeezing operating margin to roughly 3–5% and raising SLA breach risk above industry target; German private security market growth in 2024 is near 0.5%, making share defense costly. Consolidate routes or exit remote fringes and redirect ~25% of fleet hours into dense urban clusters to improve utilization and margins.
Maintenance of legacy analog systems faces a shrinking customer base and rising spare-parts scarcity; by 2024 service volumes are down materially and skilled technicians are scarce, so margins hover around break-even at best. Plan systematic sunset with staged migrations to digital platforms and avoid allocating turnaround capital to prolong analog operations.
Paper-heavy facility tasks are error-prone, slow and drive audit costs materially higher; industry studies in 2024 indicate manual workflows increase error rates and processing times by roughly 20–40% and can raise audit costs by ~30–50%, eroding margins. Clients do not pay a premium for manual processes; W.I.S. must either digitize rapidly or exit such accounts to stop the quiet bleed of labor hours and working capital. Immediate digitization reduces per-site operating cost and audit time, improving EBITDA contribution per contract.
Dogs: low-share, low-growth units with 2024 margins ~3–8%, high cancellations (~22%), travel/OD spikes (+14% labor), and break-even legacy services; together they drain cash and ops focus—recommend phased exits, divestment, or conversion to service-attached sales and redeploy capacity to contracted work (82% revenue).
| Segment | 2024 margin | Rev share | Key stat | Action |
|---|---|---|---|---|
| Ad-hoc guards | 3–4% | — | 22% cancellations | Phase down |
| Hardware resale | ≈8% | — | 12% markdowns | Divest/attach svc |
| Rural response | 3–5% | — | 20% travel hrs | Consolidate/exit |
| Analog maintenance | ≈0% | — | Shrinking volumes | Sunset/migrate |
AI-assisted video analytics sits in a high-growth market (2024 estimates point to double-digit CAGR) while W.I.S. still holds a small share; operators and vendors report up to 80–90% false-alarm reduction in 2024 pilots, implying strong margin upside if scale is achieved. Invest in targeted pilots with clear KPIs, select 1–2 core vendors for integration, and cut early if proof points (false-alarm rates, ARR uplift) are weak.
Client curiosity for drone-supported perimeter patrols rose sharply in 2024 as the global commercial drone market surpassed $20 billion, while regulatory frameworks (BVLOS, privacy) continued to evolve. Capex and training remain nontrivial—initial site buildouts often run into six-figure ranges—and operational ROI is still being proven. Target large industrials (refineries, ports) with measurable theft/safety loss reduction to build clear ROI cases. Pursue a few lighthouse sites aggressively or defer investment.
Rising demand for audits, threat modeling and compliance roadmaps is driven by regulatory expansion such as EU NIS2 covering roughly 170,000 entities and a global cybersecurity market exceeding 200 billion USD in 2024. W.I.S. is credible but not yet a default; build a compact senior team and package fixed-scope audits to shorten sales cycles. Scale only if operations attach rates remain high to preserve margin.
Converged safety/security IoT sensor ecosystems are heating up with market tailwinds: global IoT spending reached about $1.1 trillion in 2024 and the physical security market was roughly $120 billion in 2024, but W.I.S. share remains early. Bundle sensors with 24/7 monitoring and rapid response to boost stickiness and ARPU. Co-develop with tech partners to limit build risk and capex. Double down if campus deployments, up ~18% YoY in 2024, accelerate.
Green operations add-ons (energy-aware patrols, smart lighting tie-ins) sit as Question Marks for W.I.S.: sustainability budgets opened in 2024 but require measurable outcomes; current share is low and addressable space is new. Pilot with FM clients where W.I.S. already runs the floor; smart-lighting pilots often show 30-50% lighting energy savings in 2024. If verified savings land, productize; if not, shelve.
High-growth Question Marks: AI video analytics (double-digit CAGR) shows 80–90% pilot false-alarm drops; drones tie to a $20B commercial market with high capex; compliance/audit demand driven by NIS2 (~170,000 entities) and a >$200B cyber market; IoT/physical security tailwinds (IoT $1.1T, security $120B) and green ops pilots show 30–50% lighting savings—pilot, measure, scale only on clear ROI (12–24m).
| Opportunity | 2024 Data | Action | KPI | Decision |
|---|---|---|---|---|
| AI analytics | 80–90% false alarms | Targeted pilots | FAR, ARR | Scale if proven |
| Drones | $20B market | Lighthouse sites | ROI, incidents | Pilot/Defer |
| Audits | NIS2 ~170k | Fixed-scope | Attach rate | Scale if high |
| IoT/security | IoT $1.1T | Bundle+partners | ARPU, churn | Double down |
| Green ops | 30–50% lighting save | FM pilots | kWh, OPEX | Scale if 12–24m |


