
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
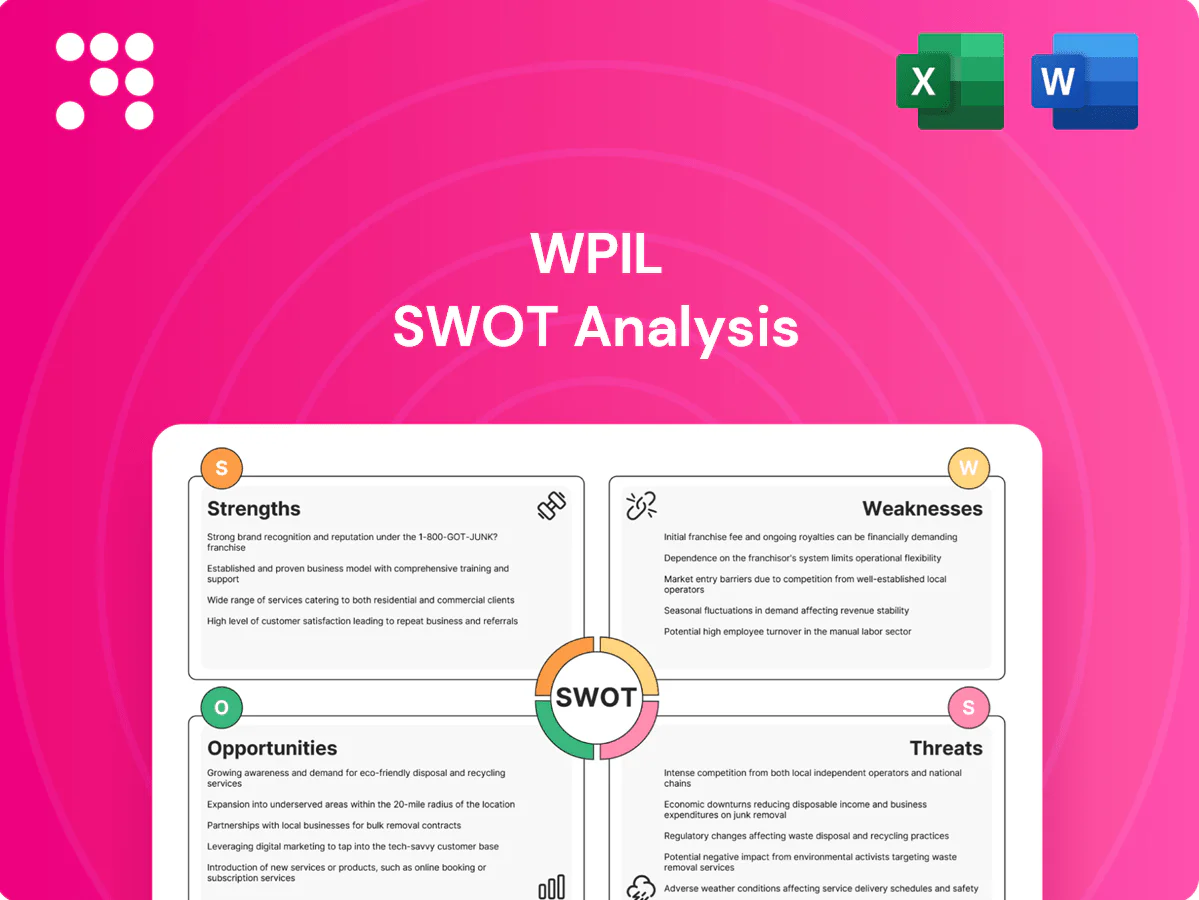
Wpil SWOT Analysis reveals practical strengths, market threats, and growth levers that shape its competitive stance; this concise preview highlights key risks and opportunities for investors and strategists. Want deeper, editable insights and financial context? Purchase the full SWOT analysis for a professional Word report and Excel workbook to plan, pitch, and act with confidence.
WPIL offers pumps across irrigation, municipal water, power and industrial segments, enabling cross-sector resilience and reducing reliance on any single demand cycle; this supports bundling and upselling across product lines. A one-stop procurement model improves customer retention and order size. The global pump market was about USD 57 billion in 2024, underpinning scale opportunity for WPIL.
Integrated EPC capabilities let WPIL design, procure and execute water projects end-to-end, reducing client coordination and schedule slippage. Owning delivery lowers interface risk for clients and supports higher switching costs through embedded O&M and spare-part contracts. This vertical control drives recurring service revenue and enhances competitiveness in complex tenders. Strong project credentials reinforce trust with institutional buyers and EPC partners.
Presence across India and select international markets diversifies revenue streams, aligning with India’s ~6.8% GDP growth in 2024 which supports domestic demand. Operating under varied regulatory regimes enhances technical credibility and compliance experience. Global sourcing and channels can shave costs and reduce lead times, while revenues in multiple currencies provide natural hedges against INR volatility.
Application engineering that tailors pump designs to site-specific hydraulic conditions differentiates Wpil from commodity suppliers, enhancing reliability and lifecycle performance; pumping systems account for about 20% of global industrial electricity use (IEA) and energy typically represents ≈80% of pump lifecycle cost, underpinning lower TCO claims and justification for premium pricing.
Core offerings map directly to water security, irrigation and urban infrastructure, tapping sustained government and multilateral financing that supports long-cycle projects. Policy tailwinds — non-revenue water reduction, smart metering rollouts and wastewater reuse targets — broaden the addressable market and help sustain order pipelines through downturns. This alignment reduces revenue cyclicality and strengthens backlog visibility.
WPIL’s diversified pump portfolio spans irrigation, municipal, power and industrial clients, leveraging a USD 57bn global pump market (2024) to cross-sell and reduce cyclicality. Integrated EPC and O&M drive higher switching costs and recurring revenue, improving tender competitiveness. Site-specific engineering and energy-efficient designs (pumping ≈20% industrial electricity; energy ≈80% LCC) justify premium pricing.
| Metric | 2024 |
|---|---|
| Global pump market | USD 57bn |
| India GDP growth | ≈6.8% |
| Pumping share of industrial electricity | ≈20% |
 Detailed Word Document
Delivers a strategic overview of Wpil’s internal capabilities and external market factors, outlining strengths, weaknesses, opportunities, and threats to inform competitive positioning and strategic decision-making.

 Customizable Excel Spreadsheet
Wpil SWOT Analysis offers a compact, visual matrix that pinpoints pain points and suggests actionable responses, enabling rapid alignment and faster decision-making across teams.
EPC and capex pumps face bid-to-cash cycles often spanning 12–36 months, driving working capital strain. Receivable days in construction average ~90–120 days, with retention money commonly 5–10% held for 6–12 months, causing spikes. Project delays trigger liquidated damages (commonly 0.05–0.2% per day) that compress margins and increase financing costs, making cash-flow planning volatile.
Wpil's BOMs and foundry costs are highly exposed to commodity swings: steel HRC averaged around $700/t and LME copper near $9,000/t in 2024, while industrial electricity in Europe hovered ≈€0.18–0.22/kWh, driving input cost volatility. Pass-through clauses often fail in aggressive tenders, forcing the company to absorb spikes that have eroded gross margins mid-project. Financial hedges reduce but do not eliminate exposure, leaving residual price risk.
Limited service and spares capture leaves lifetime value under-realized, as recurring aftermarket revenue is where margins concentrate. Third-party service and non-OEM parts increasingly displace OEMs in many regions. Weak digital monitoring reduces predictive-maintenance upsell potential; the global predictive-maintenance market nears $30bn by 2025, so this cedes high-margin recurring revenue.
Compared with large multinationals, Wpil’s brand equity and R&D budgets are smaller; leading global majors report R&D spends above $1bn and operate service networks across 100+ countries, allowing broader installed bases and faster product iterations. That scale pressures Wpil on pricing, bid qualification and restricts marketing reach versus rivals with global channel depth.
Over-reliance on a few regions or funding sources elevates risk for Wpil, making order books vulnerable if local policy or budget shifts occur and stall projects. Currency swings can inflate costs for imported components and reduce margins on overseas contracts. Diversification appears incomplete, concentrating exposure in limited markets and counterparty types.
Long bid-to-cash cycles (12–36 months) with DSO ~90–120 and 5–10% retention strain working capital; delays incur LDs 0.05–0.2%/day. Input-cost exposure (steel ~$700/t, copper ~$9,000/t, EU power €0.18–0.22/kWh) and failed pass-throughs compress margins. Limited aftermarket capture and digitalization cede recurring margins; predictive-maintenance market ≈$30bn (2025). R&D shortfall vs majors (> $1bn) and limited service network (<<100 countries) amplify pricing and geographic concentration risks.
| Metric | Exposure | 2024/25 |
|---|---|---|
| DSO/Retention | Working capital | 90–120d / 5–10% |
| Commodities | Input cost | Steel $700/t, Cu $9,000/t |
| Aftermarket | Margin loss | PM market ≈$30bn |
| Scale | Competitiveness | R&D gap >$1bn; nets <<100 countries |
This is the actual Wpil SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report you'll get; purchase unlocks the editable, complete version. You’re viewing the real file ready for download after checkout.
Urban water supply, irrigation modernization and wastewater treatment are accelerating under expanded government missions and PPP pipelines, enlarging tender volumes for players like WPIL. WPIL can pursue design-build-operate contracts and bundle its pumps with EPC services to increase wallet share and capture higher-margin lifecycle revenues. Targeting integrated DBO bids positions WPIL to benefit from rising O&M and retrofit demand across municipal and agricultural segments.
Water-stressed regions rapidly adopt desalination and reuse; MENA and GCC account for roughly half of global desal capacity, opening coastal markets for Wpil. High-spec corrosion-resistant pumps carry premiums of 20–30% versus standard units, boosting margins. Reference projects can unlock new contracts; partnerships with process OEMs shorten procurement cycles and accelerate market entry.
IoT-enabled monitoring, VFD integration and edge/cloud analytics can cut unplanned downtime by up to 30% and boost motor system energy savings 20–50%, enabling outcome offers (99.9% uptime SLAs, verified energy savings) that command premium margins. Subscription-based remote monitoring creates recurring revenue with software-like gross margins ~70–80% and reduces churn 5–10%. Data flywheels from telemetry strengthen customer lock-in and upsell ARPU over time.
High-efficiency motors and optimized hydraulics can cut pump station energy use 10–30% and boost hydraulic efficiency 5–15%, aligning with ESG targets and lowering power costs; retrofits on aging pump stations often show paybacks of 1–3 years. Utility incentive programs (rebates up to ~30% in 2024–25) accelerate adoption and improve bid scoring, enabling premium pricing in tenders where ESG can weigh ~15–25% of procurement evaluation.
Expand into DBO/PPP bids to capture lifecycle margins; municipal/irrigation tenders growing with govt pipelines. Target desalination reuse in MENA/GCC (~50% of global capacity) and Africa/SE Asia (1.4B/680M) via local JV and EXIM-backed tenders. Sell IoT/VFD outcomes (energy savings 20–50%, uptime +30%) and retrofit projects (payback 1–3 yrs) to secure recurring revenues.
| Opportunity | KPI | Metric |
|---|---|---|
| Desal/reuse | Market share | ~50% MENA/GCC |
| IoT/VFD | Energy savings | 20–50% |
| Retrofit | Payback | 1–3 yrs |
Global OEMs and regional players vie on price, delivery and specs in a market that produced about 80 million vehicles in 2024, with the top 10 OEMs accounting for roughly 60% of output, intensifying scale-driven pressure on suppliers. Aggressive discounting in recent tenders has commoditized bids and squeezed margins, while channel conflicts between direct OEM deals and distributors further erode profitability. In tender-driven segments customer loyalty is thin, raising churn risk and forcing continual reinvestment in price and service to retain share.
Changes in public budgets, elections (over 60 national votes in 2024) and evolving procurement norms routinely delay awards by several months, squeezing cashflow. Project cancellations create inventory and receivable overhangs often equivalent to 3–6 months of revenues. Stricter localization rules in markets like India and Brazil can raise costs by double-digit percentages. Multilateral funding cycles remain unpredictable, with annual commitments varying year-to-year.
Raw-material and freight shocks have pushed container spot rates up and down (Drewry: ~60% fall from 2021 highs by 2023), disrupting costs and schedules; component lead times commonly exceed 12 weeks in 2024 (IHS/S&P data). Geopolitical events since 2022 (Russia–Ukraine, US–China tensions) have imposed export controls and transit risks. Clients frequently enforce liquidated-damage clauses for delayed deliveries.
Competing technologies such as advanced variable-speed drives and magnetic-drive pumps are shifting performance benchmarks; the global VFD market was ~USD 20B in 2023 with ~7% projected CAGR to 2031, increasing replacement pressure. Digital-first entrants with cloud-native control stacks can outpace legacy offerings, while failure to upgrade controls and monitoring risks rapid obsolescence. Regulatory standards (motor/pump efficiency) are tightening across EU and US markets, raising compliance costs.
Exchange swings raise costs for imported inputs and can erode profitability of overseas projects, while rising interest rates increase working capital and project finance costs; clients may defer capex when credit tightens, and hedging raises expenses and cannot fully eliminate currency or rate exposure.
Intense OEM scale: 80M vehicles (2024), top 10 = ~60% output, commoditized tenders compress margins. Supply shocks: container rates volatile (≈60% drop from 2021 highs by 2023), component lead times >12 weeks (2024), cancellations = 3–6 months revenue. Tech/regulation: VFD market ≈USD20B (2023), ~7% CAGR, tightening EU/US efficiency rules raise compliance costs; FX and higher rates squeeze cashflow.
| Threat | Metric |
|---|---|
| OEM concentration | 80M vehicles (2024); top10 ~60% |
| Supply disruption | Container rates -60% vs 2021; lead times >12w (2024) |
| Tech/regulation | VFD market USD20B (2023), 7% CAGR; stricter EU/US standards |


