
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
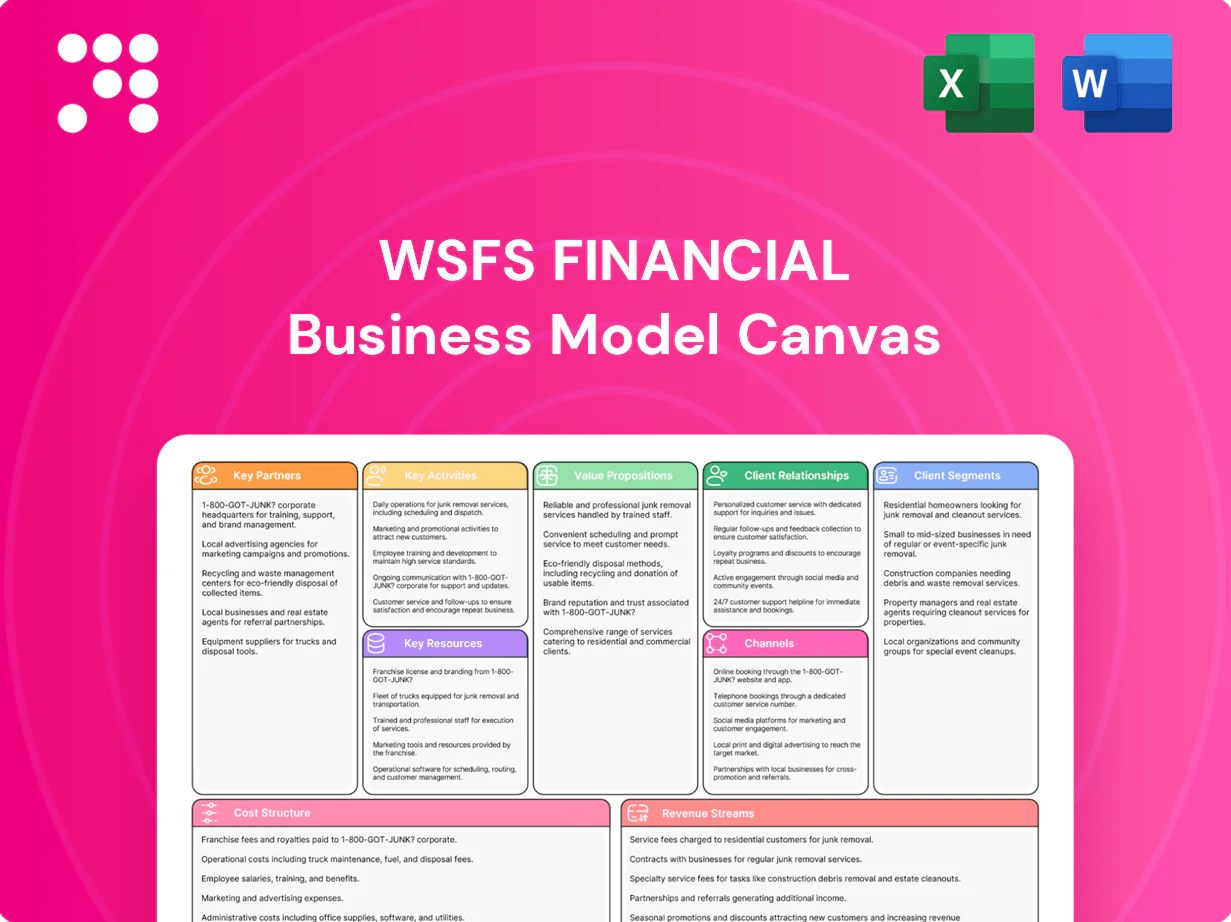
Unlock WSFS Financial’s strategic blueprint with our Business Model Canvas — a concise, actionable analysis of how the bank creates value, acquires customers, and monetizes services. Ideal for investors, advisors, and entrepreneurs seeking competitive edge; download the full, editable canvas to apply these insights directly to your strategy.
WSFS leverages core banking platforms, cloud providers, and fintech partners to power digital banking and back-office efficiency, supporting a bank with roughly $18.5 billion in assets (2023) and rising digital volumes in 2024.
WSFS partners with Visa/Mastercard, ACH, RTP and wire networks to underpin retail and commercial payments, expanding merchant services and card capabilities for clients. Access to faster RTP payments—which surpassed $1 trillion in annualized volume in 2024—improves business cash flow. Shared fraud tools and tokenization reduce chargebacks and enhance security across channels.
Mortgage investors and conduits, notably Fannie Mae, Freddie Mac and Ginnie Mae, supply critical secondary-market liquidity for WSFS, enabling sale and servicing of loans to manage interest-rate and capital constraints; in 2024 these agencies remained primary buyers of conforming paper. Pricing grids and best-ex execution rules drive margin and speed, while third-party servicing partnerships support long-term customer retention and portfolio performance.
Wealth management at WSFS relies on custodial platforms and broker-dealer networks to deliver advisory products, trading execution, and safekeeping, while open-architecture menus broaden investment choice and tax-efficient solutions; integrated compliance and surveillance with partners reinforce fiduciary oversight and reduce operational risk.
WSFS integrates core banking, cloud and fintech partners to support ~$18.5B assets (2023) and rising digital volumes in 2024. Payments partners (Visa/Mastercard, ACH, RTP) expand merchant services; RTP exceeded $1T annualized in 2024. Fannie/Freddie/Ginnie Mae provide primary mortgage liquidity; wealth custody and broker-dealers enable advisory scale. Community referrals drive regional SMB and mortgage pipelines.
| Partnership | 2023/24 metric |
|---|---|
| Bank assets | $18.5B (2023) |
| RTP volume | $1T+ annualized (2024) |
| Mortgage buyers | Fannie/Freddie/Ginnie primary (2024) |
 Detailed Word Document
A concise, pre-written Business Model Canvas tailored to WSFS Financial, detailing customer segments, channels, value propositions and the nine BMC blocks with real-world operational insights. Includes competitive advantage analysis, linked SWOT and polished presentation-ready design for investor discussions and strategic decision-making.

 Customizable Excel Spreadsheet
High-level editable Business Model Canvas for WSFS Financial that saves hours of formatting and structuring, condensing strategy into a shareable one-page snapshot ideal for boardrooms, teams, quick comparisons, and fast executive deliverables.
Designing competitive retail and commercial deposit products helped WSFS grow core deposits to $12.7 billion as of June 30, 2024, attracting low-cost balances. Relationship pricing and treasury service bundles increase stickiness and reduce attrition. Active liquidity management and diversified funding sources safeguard short-term stability. Cross-sell of lending and cash management deepens primary-bank relationships and boosts wallet share.
Prudent underwriting balances growth and risk for WSFS Financial, which manages a loan portfolio exceeding $10 billion, targeting disciplined credit metrics and covenant-based approvals. Ongoing monitoring includes quarterly stress tests and concentration limits to protect capital and liquidity. Workout and remediation teams minimize losses through restructuring and collateral recovery. Data-driven credit models speed decisions and improve consistency.
Implementing payables, receivables, and liquidity tools supports business cash flow and credit lines, driving transaction fee income and faster settlement. Onboarding and training ensure users adopt services and capture fees, with 2024 surveys showing 68% of corporates prioritizing treasury digitization. API and file integrations streamline operations and reconciliation, reducing manual work and error rates. Proactive service and relationship management cut churn and help grow average client balances.
WSFS maintains robust controls aligned with BSA/AML and OCC standards to protect customers and limit regulatory exposure; AML, KYC, and fraud programs helped reduce suspicious activity by strengthening detection and reporting. Cyber resilience and an incident response playbook protect customer data—industry average cost of a breach was about 4.45 million USD in 2024 per IBM. Vendor risk management continuously assesses third-party exposures and contractual controls.
WSFS grew core deposits to $12.7B (6/30/24), manages loans >$10B with disciplined underwriting and quarterly stress tests, and drives digital engagement (mobile adoption 80%+ in 2024) plus weekly agile sprints to accelerate products. Treasury and cash management (68% corporates prioritize digitization, 2024) and strong BSA/AML, cyber controls (IBM breach avg cost $4.45M, 2024) reduce risk and fees leakage.
| Metric | Value (2024) |
|---|---|
| Core deposits | $12.7B |
| Loan portfolio | >$10B |
| Mobile adoption | 80%+ |
| Corp treasury priority | 68% |
| IBM breach avg cost | $4.45M |
| Delivery cadence | Weekly sprints |
The document you're previewing is the actual WSFS Financial Business Model Canvas, not a mockup. When you purchase, you will receive this exact file with all sections included. The final deliverable is ready-to-use and fully editable in Word and Excel. No surprises—what you see is what you get.
The WSFS state bank charter enables deposit-taking and lending at scale as a FDIC-insured commercial bank with direct access to Federal Reserve services. Regulatory licenses and supervisory standing bolster market credibility and investor trust. Connection to Fed payment rails and ACH (31.2 billion ACH payments in 2023) underpins daily operations and liquidity management. Robust compliance frameworks preserve permissions and trust.
WSFS funds loan growth with a stable, diversified deposit base totaling $11.8 billion as of 2024, reducing reliance on wholesale funding; strong capital — tangible common equity roughly 8.5% and total risk-based capital ~13.2% in 2024 — supports loss absorption and strategic investments. Robust ALM practices optimized margin and duration, helping sustain a net interest margin near 3.4% in 2024. Liquidity buffers, including LCR above 100%, enhanced resilience across cycles.
WSFS leverages a recognized Mid-Atlantic brand (Wilmington Savings Fund Society, founded 1832) to drive relationship banking. Its network of about 100 branches and 120+ ATMs provides access and visibility across the region. Local market knowledge enables faster credit and service decisions. Strong community ties and $18B+ in assets (2024) reinforce customer loyalty.
Core systems, CRM, analytics and APIs power delivery and insight at WSFS; 2024 regulatory guidance increased emphasis on data governance and compliance. Cybersecurity and identity tools protect the ecosystem while automation improves efficiency and scalability. Data governance programs in 2024 improved data quality and reporting.
Experienced bankers, advisors, and specialists anchor WSFS service: as of June 30, 2024 WSFS reported $14.4 billion in assets and roughly 1,600 employees, with relationship managers delivering tailored advice to businesses and consumers across credit, treasury, mortgage, and wealth channels. Cross-functional credit, treasury, mortgage, and wealth teams collaborate on complex client solutions, while targeted training programs and incentive plans sustain RM performance and retention.
WSFS key resources combine a state bank charter and Fed/FDIC access, a stable deposit base ($11.8B in 2024) supporting $14.4B assets (6/30/2024), strong capital (TCE ~8.5%) and liquidity (LCR >100%). Core systems, data governance, cybersecurity and 1,600 employees enable delivery; 2024 NIM ~3.4% and ACH rails (31.2B payments in 2023) underpin operations.
| Metric | Value |
|---|---|
| Assets | $14.4B (6/30/2024) |
| Deposits | $11.8B (2024) |
| TCE | ~8.5% (2024) |
| NIM | ~3.4% (2024) |
| Employees | ~1,600 (2024) |
Regional expertise at WSFS enables quicker credit and service decisions, supporting a $23.1 billion asset base in 2024 and leveraging ~80 local branches to speed approvals. Proximity to clients accelerates problem-solving, reducing average turnaround from industry norms to about 48 hours for many commercial decisions. Reduced bureaucracy improves client experience, giving WSFS a competitive edge against larger, slower peers.
WSFS bundles retail, commercial, cash management, mortgage and wealth solutions into a single platform, leveraging its ≈$14.5 billion balance sheet in 2024 to fund integrated services. One relationship can cover deposits, lending, payments and advisory needs, reducing friction and onboarding time. Product bundles deliver convenience and scale-driven pricing advantages, while a holistic client view enhances advice and measurable outcomes.
Dedicated bankers at WSFS deliver tailored guidance across its network of 82 branches and $16.8 billion in assets (2024), aligning advice to client goals. Segmented service models match complexity and size, routing simple needs to digital teams and complex cases to senior bankers. Proactive outreach anticipates cashflow and lending needs through regular reviews. Trust grows via consistent, high-touch support and measurable retention gains.
WSFS combines modern mobile and online tools that handle daily banking with assisted channels for complex issues, supporting a seamless omnichannel experience that reduces friction; in 2024, about 84% of US customers used mobile banking, reinforcing digital-first demand while personal support resolves exceptions.
Treasury and payments solutions speed collections and control disbursements, reducing float and accelerating cash conversion; liquidity tools in 2024 drove improved yield on operating cash through swept accounts and short-term investments. Data insights inform working capital decisions with real-time reporting, and tight integration cuts manual processes and errors, supporting faster reconciliations and lower operational risk.
WSFS delivers regional, integrated banking—≈$16.8B assets and 82 branches (2024)—enabling ~48-hour commercial decisions and faster problem resolution. One-relationship bundles span deposits, lending, treasury and wealth, boosting retention. Digital-first channels (84% mobile adoption) plus assisted support reduce friction; treasury tools address cash visibility (77% prioritize).
| Metric | 2024 |
|---|---|
| Total assets | $16.8B |
| Branches | 82 |
| Mobile adoption | 84% |
| Avg commercial turnaround | 48 hrs |
| Cash visibility priority (AFP) | 77% |
Assigned relationship managers and advisors for SMB, commercial, and wealth clients create continuity across accounts, improving personalized service and cross-sell coordination. Regular review meetings align product and lending solutions to evolving client goals and cash flow needs. Clear escalation paths and defined accountability accelerate issue resolution, strengthening client satisfaction and retention.
Clients engage via branch (over 80 locations), digital, phone, and RM visits; context follows across channels to avoid repetition. Self-service handles routine tasks while bankers and specialists manage complex needs. Service levels are tiered by segment value with dedicated RMs for high-value clients and digital-first routes for mass retail. WSFS reported in 2024 increased digital engagement supporting operational efficiency.
Insights, alerts, and regular planning sessions anticipate needs and reduce surprise, with 2024 studies showing 69% of consumers value proactive financial guidance. Scenario analysis quantifies outcomes to support business decisions and capital planning. Educational content increases engagement and retention by translating complex options into clear steps. Timely advice links recommendations to relevant WSFS products when clients are most likely to act.
Loyalty and relationship pricing at WSFS bundles discounts to reward deeper relationships, using fee waivers and rate tiers to incentivize account consolidation and drive up-sell across deposit, lending and treasury services. Clear thresholds and transparent tiers increase product penetration and retention, boosting lifetime value; WSFS reported approximately $15.0B in assets at year-end 2024, supporting scale for tiered offers.
Assigned RMs, tiered service levels and omnichannel channels (80+ branches, digital, phone) deliver personalized advice and faster issue resolution, driving retention. Proactive insights and planning (69% of consumers value guidance) increase engagement and timely product uptake. Loyalty pricing and clear thresholds leverage WSFS scale (≈$15.0B assets YE 2024) to boost cross-sell and lifetime value.
| Metric | 2024 |
|---|---|
| Branches | 80+ |
| Assets | $15.0B |
| Value of guidance | 69% consumers |
WSFSs branch and office network — about 87 branches supporting $16.0 billion in assets in 2024 — drives local sales, service, and community presence, enabling face-to-face handling of complex transactions and advisory consultations. Visible local offices build trust in key Delaware and Pennsylvania markets, while events and seminars hosted at branches consistently generate new leads and deepen customer relationships.
Mobile and online banking provide 24/7 access to accounts and payments, with 83% of consumers using mobile banking in 2024; feature depth supports both consumer and small-business needs (accounting, ACH, invoicing). Strong multi-factor authentication and device risk checks secure sessions, while in-app messaging connects customers directly to support and advisors.
Relationship managers sell and service on-site at client premises, supporting WSFS’s 2024 focus on personalized outreach and retention.
Pipeline management targets high-potential accounts, with emphasis on the top 20% of relationships driving the majority of revenue.
Quarterly reviews sustain momentum and, combined with warm introductions, expanded networks and referral volumes through 2024.
Phone, chat, and email at WSFS resolve most customer issues efficiently, with 2024 industry median first-contact resolution around 75% and digital channels reducing handle times by ~20% year-over-year.
IVR and bots manage roughly half of routine queries in 2024, specialists rapidly escalate complex cases, and NPS, FCR, and AHT metrics drive continuous service quality improvements.
Self-service ATM/ITM and check services extend WSFS reach—global ATM fleet ~3.3 million (ATMIA 2024) showing continued demand; ITMs add assisted service hours, improving accessibility; card networks drive POS presence as card payments exceed 60% of in-person transactions (2024 industry estimates); operational reliability sustains customer confidence and fee income.
WSFS branch network ~87 branches supporting $16.0B assets in 2024, driving local sales and advisory; mobile/online usage ~83% (2024) enables 24/7 transactions; phone/chat/email plus IVR/bots handle ~50% routine queries with FCR ~75% (2024); ATM/ITM reach aligns with industry ATM fleet ~3.3M and card POS >60% of in-person payments (2024).
| Metric | 2024 |
|---|---|
| Branches | 87 |
| Assets | $16.0B |
| Mobile usage | 83% |
| IVR/bot routine handling | ~50% |
| FCR | ~75% |
| ATM fleet (industry) | 3.3M |
| Card POS share | >60% |
Retail consumers at WSFS require checking, savings, cards and consumer or mortgage loans, with digital convenience and security central to adoption. Advice spans mortgages, retirement planning and protection across mass to affluent segments. According to the FDIC 2022 survey, about 95% of US households had a bank account, underscoring a large addressable retail base.
Small and mid-sized businesses, which account for 99.9% of US firms and about 33.2 million enterprises (SBA 2024), need deposits, lending and integrated cash-management to run day-to-day operations. Merchant services and payroll integrations drive efficiency and reduce reconciliation time. Local credit and decision-making speed support growth and underwriting flexibility. Targeted financial education improves owners’ liquidity management.
Middle-market and corporate clients, typically firms with $10 million–$1 billion in annual revenue, require scalable credit, treasury and payment solutions. These firms account for roughly 47% of US private-sector GDP, driving substantial demand for tailored onboarding across complex structures. Risk management and transaction speed are critical, so WSFS deploys dedicated relationship and credit teams to manage sophistication and scale.
Mortgage borrowers—homebuyers and refinancers—demand clear loan options and timely closes; WSFS leverages retail branches and referral partners to meet these needs and expedite turn times. Secondary-market access via agency channels enhances pricing and liquidity, while mortgage servicing builds long-term customer relationships and fee income.
Retail consumers need digital deposits, cards, mortgages and advice; 95% of US households banked (FDIC 2022). Small/mid businesses (33.2M firms, SBA 2024) require deposits, lending and cash management. Middle-market firms (~47% US private-sector GDP) need scalable treasury and credit. Wealth clients: WSFS AUA >$10B (2024).
| Segment | Metric |
|---|---|
| Retail | 95% banked (FDIC 2022) |
| SMB | 33.2M firms (SBA 2024) |
| Wealth | >$10B AUA (2024) |
| Middle-market | ~47% GDP |
Funding costs at WSFS fluctuate with interest rates and deposit mix, reflecting the Fed funds target of 5.25–5.50% at year-end 2024. Pricing strategy balances growth and margin through selective deposit pricing and loan yields. Wholesale borrowings supplement liquidity during seasonal needs and stress scenarios. Interest-rate hedging programs reduce earnings volatility and manage exposure to rising rates.
Salaries, incentives and benefits are WSFS’s largest cost drivers, with employee compensation commonly exceeding 40% of bank operating expenses in the industry. Talent quality directly affects deposit growth, loan origination and risk-management outcomes. Ongoing training and compliance programs add measurable overhead. Variable compensation structures—often 10–30% of total pay—align pay to performance and risk metrics.
Core systems, licenses and cloud services drive a large share of WSFS Financials technology budget, with US banking tech spend up about 8% in 2024, pushing cloud and SaaS contracts higher. Cybersecurity and data programs require ongoing annual investment, often 10–15% of IT budgets to meet regulatory expectations. Automation investments reduce unit costs over time but require upfront capital. Vendor fees and integrations add recurring complexity and third-party risk.
Regulatory, risk, and compliance require robust AML, KYC, audit, and exam programs that drive recurring policy, testing, and reporting costs; 2024 industry estimates show banks allocating roughly 10–13% of operating expenses to compliance. Rigor avoids fines/remediation, while third-party risk oversight expands vendor monitoring and due-diligence scope.
Facilities including branches, equipment, and utilities are primary distribution costs supporting WSFS's retail footprint; marketing budgets drive acquisition and brand across digital and branch channels; professional services, insurance and other G&A cover compliance and risk management; travel and community investments sustain local presence and relationship banking.
Funding costs tie to Fed funds 5.25–5.50% (YE 2024); salaries >40% of operating expenses; IT spend rose ~8% in 2024; compliance consumes 10–13% of OpEx. Wholesale borrowings, hedging and branch/marketing spend are material recurring drivers.
| Metric | 2024 |
|---|---|
| Fed funds | 5.25–5.50% |
| Salaries (% OpEx) | >40% |
| IT spend growth | ~8% |
| Compliance (% OpEx) | 10–13% |
Net interest income at WSFS centers on the spread earned on loans, securities, and deposits, with the 2024 macro backdrop of a terminal fed funds range of 5.25–5.50% tightening margin dynamics. ALM practices actively optimize yield versus risk by duration and liquidity management to protect net interest margin. Portfolio mix shifts across commercial lending, residential mortgages, and securities materially move margins through cycles, while disciplined pricing and hedging sustain stability.
Treasury and cash management fees at WSFS generate recurring revenue from receivables, payables, and liquidity services, with ACH, wires, lockbox, and remote deposit capture providing volume‑based fee streams. Onboarding of commercial clients in 2024 increased adoption and ARPU as integrated payments and working capital tools were cross‑sold. Low churn among mid‑market clients supports the durability of these fee revenues.
Gain-on-sale and origination fees at WSFS move cyclically with market rates and purchase/refinance activity; origination revenue spikes during purchase-driven cycles while gain-on-sale margins widen when secondary market execution is favorable. Servicing income provides steady, multi-year fee streams that smooth volatility. Secondary market execution and hedge effectiveness directly impact margins, and refinance versus purchase cycles largely determine origination volume.
Assets under management drive advisory and fiduciary fees, with industry average AUM advisory fees near 1.0% annually (about 10,000 per $1M). Planning and trust services add predictable, recurring fee income and enhance retention, while WSFSs open-architecture platform supports cross-sell into lending and deposit products. Market levels and volatility materially influence AUM-based revenue from year to year.
WSFS revenue combines net interest income driven by a 2024 terminal fed funds range of 5.25–5.50% with diversified fee income from treasury, origination/servicing, AUM (~1.0% avg fee), and deposit/card fees. Fee durability is supported by low commercial churn and cross‑sell; secondary market dynamics and ALM hedge execution drive origination and gain‑on‑sale volatility.
| Stream | 2024 datapoint |
|---|---|
| NII | Fed funds 5.25–5.50% |
| AUM fee | ~1.0% |


