
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
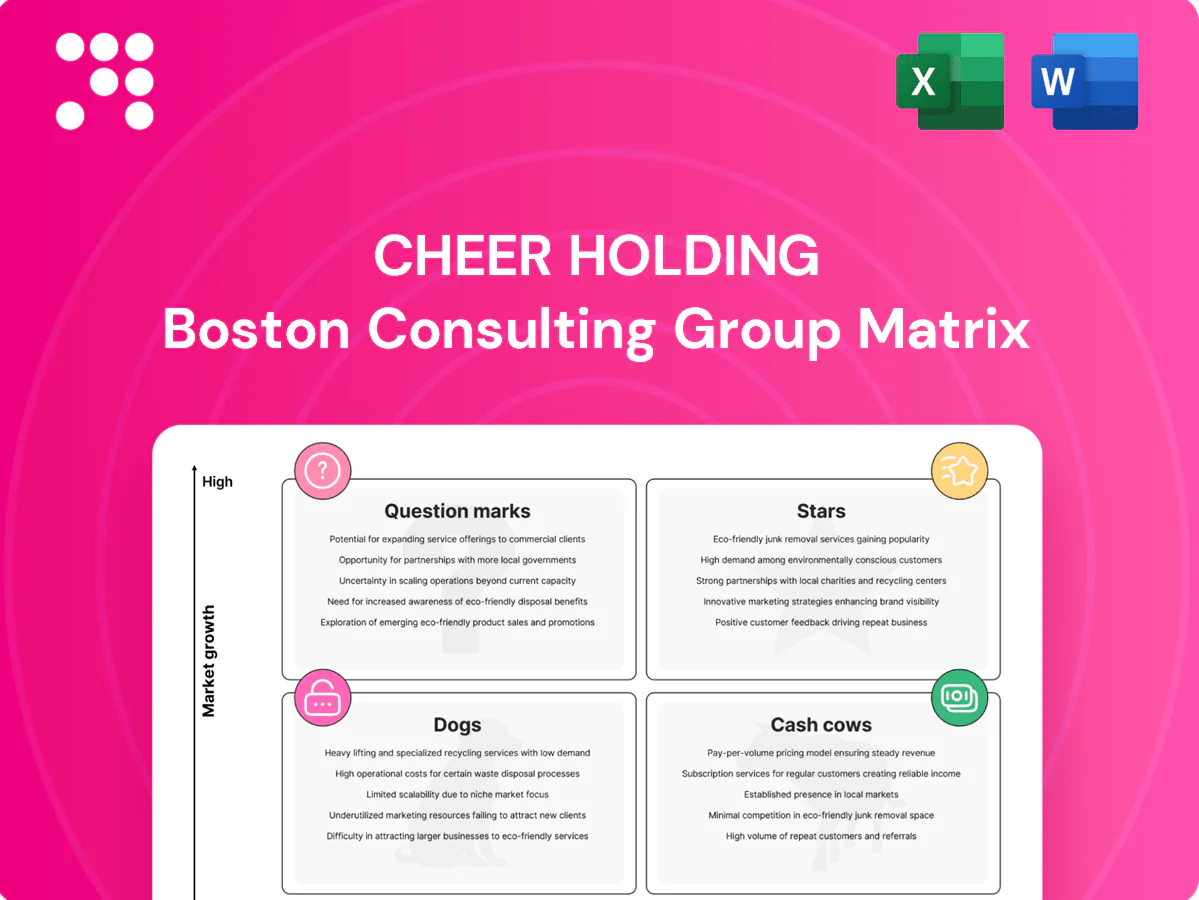
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Want the real story behind Cheer Holding’s lineup? This snapshot shows the contours, but the full BCG Matrix pins each product into Stars, Cash Cows, Question Marks or Dogs—with data, quadrant visuals and actionable moves. Buy the complete report to get a downloadable Word analysis plus a high-level Excel summary you can present or tweak right away. Skip the guesswork—get the strategic clarity that lets you allocate capital and prioritize growth, fast.
China had 989 million short‑video users by end‑2023 (CNNIC), and short‑form continues exploding — our packaged creator+placement model directly rides that wave. We’ve built repeatable plays that win briefs and secure premium inventory, converting scale into higher CPMs. Keep feeding the engine with creator partnerships and data tooling to sustain yield. Hold share now and graduate to Cash Cow as market growth cools.
Mobile performance ads sit in Stars as high‑intent app installs and conversions are surging; global mobile ad spend reached about $305 billion in 2024 and mobile accounted for roughly 70% of digital ad spend. Our campaigns regularly top client mixes and can represent ~25% of media budgets, with performance budgets scaling rapidly but needing constant optimization. Prioritize automation, measurement and exclusive supply to sustain speed so ROAS does not flatten.
KOL/influencer activations sit in Stars: brands chase credibility on social and KOL ties deliver outsized impact in growth categories; global influencer spend reached about $23.9 billion in 2024, validating scale. We’ve got the playbook and roster to lead pitches and convert attention into trial. The spend is big but so is the upkeep—creator fees, sourcing, compliance—and we should keep doubling down while the adoption curve is steep.
Premium programmatic video inventory with completion rates often in the 70–80% range is scarce and we broker it effectively; programmatic accounted for roughly 86% of US digital display spend in 2024, validating scale and premium demand. Our combined access and bid optimization keeps win rates materially above open-market averages, though the channel requires significant data and engineering spend. It consumes cash but secures the pipe before commoditization.
Content that clicks to cart is the hot lane, especially in live and shoppable feeds; 2024 live-shopping sessions report conversion rates of roughly 8–20% while shoppable-feed CTRs average 1.5–3%, driving higher AOVs and faster payback for campaigns. We sit close to platforms and conversion partners, and recent pilots show ROAS improvements of 20–40% vs. standard social ads.
China 989m short‑video users (end‑2023); mobile ad spend ~$305B (2024) and ~70% of digital; influencer spend ~$23.9B (2024); programmatic ~86% of US display (2024). Our creator+placement, programmatic access and shoppable feeds drive 20–40% ROAS uplift but need heavy data/engineering and creator investment to hold share as growth normalizes.
| Metric | 2023/24 |
|---|---|
| Short‑video users (China) | 989m |
| Mobile ad spend | $305B (2024) |
| Influencer spend | $23.9B (2024) |
| Programmatic share (US) | 86% (2024) |
| Live‑shop conv | 8–20% (2024) |
 Detailed Word Document
In-depth BCG analysis of Cheer Holding's portfolio, showing Stars, Cash Cows, Question Marks and Dogs with clear investment recommendations.

 Customizable Excel Spreadsheet
One-page Cheer Holding BCG matrix mapping units to priorities, cutting decision friction and speeding executive alignment.
Managed social media retainers deliver always-on brand ops—calendars, community, content—fitting Cheer Holding as a Cash Cow with mature demand and predictable gross margins around 55–70% and annual churn under 10%. The global social media management market was estimated at $9.2B in 2024; incremental tools can boost efficiency ~30% without heavy capex. Keep service scope tight and quietly milk renewals for steady cash flow.
Standard banners still fill plans for reach at low CPMs—median programmatic display CPM was about $2.50 in 2024. Growth is flat (0–2% YoY) but fulfillment costs remain low (~5–8% of revenue), making them reliable cash cows. Bundle with higher‑margin units (bundling uplift 15–25%) to keep yield. Optimize trafficking and cap investment; avoid scaling spend into low‑return placements.
Routing budgets across Google Ads and Meta remains routine in 2024, with both platforms the top two by ad spend. Our muscle is process, not novelty, which prints steady cash through repeatable buy-and-optimize workflows. Automations and programmatic trading (over 80% of display in 2024 per IAB) squeeze margin and lift ROI. Maintain Google Partner and Meta Business Partner certifications to keep the lights humming.
Enterprise account relationships act as cash cows: long‑standing contracts with renewal rates around 90% in 2024 and modest upsell of ~5–10% ARR, generating high-margin cash (gross margins ~70%) with minimal promotional spend and strong utilization. Use predictable receipts to smooth cash flow and fund strategic bets, while protecting revenue via senior coverage and quarterly business reviews.
Ad ops and reporting stack are cash cows: in-house trafficking, QA, and dashboards are fully depreciated capabilities delivering stable demand across campaigns in 2024; small iterative upgrades yield outsized reliability and margin uplift while avoiding costly rebuilds unless forced.
Cheer Holding cash cows: stable social retainers (55–70% gross margin, <10% churn), low‑cost display (median CPM $2.50, 0–2% growth), repeatable paid media workflows (80% programmatic), and enterprise accounts (90% renewal, 5–10% upsell). Harvest margins, limit capex, bundle for yield.
| Unit | Key metrics (2024) |
|---|---|
| Social retainers | 55–70% GM; <10% churn; market $9.2B |
| Display | CPM $2.50; 0–2% YoY |
| Paid media | 80% programmatic |
| Enterprise | 90% renewal; 5–10% upsell |
The file you're previewing here is the exact Cheer Holding BCG Matrix you'll receive after purchase—no watermarks, no demo content, just the finished report. It's crafted by strategy pros and formatted for clarity, ready to edit, print, or present. Buy once and the full, ready-to-use document is yours to download immediately.
Desktop‑only display buys sit in Dogs: with mobile reaching 58% of web traffic in 2024 (StatCounter) and desktop share falling annually, reach and impressions shrink. Engagement and conversion rates are low, share of spend under 5% of total display, and campaigns only break even after overhead. Recommend wind down desktop inventory and reallocate spend to mobile and CTV where CPMs and ROAS are stronger.
WAP/SMS push promotions are legacy formats hampered by regulatory friction and poor user experience; 2024 industry data still shows SMS open rates near 98% but conversion rates under 5% versus higher-ROI channels. Clients seldom request them and campaign results lag modern omnichannel tactics, leaving cash tied up managing remnants. Exit unless required as a low-cost add-on in rare bundled use cases.
Arbitrage on unknown supply invites fraud and refunds; global ad-fraud losses rose to an estimated $124 billion in 2024, and make-good/refund rates on low-quality traffic often erode advertised margins. Intensive monitoring and make-goods shrink net margin and consume ops time, leaving little strategic value while amplifying brand risk. Cut third-party low-quality reselling to protect brand equity and cash flow.
One-off regional offline events are high-logistics, low-repeatability plays that cap scale; industry estimates put logistics at 30–40% of event budgets while post-production margins often compress to 5–10%, pulling ops away from core digital product roadmaps and slowing releases.
Dogs:
Dogs are low-share, low-growth channels—desktop display, static rich media, WAP/SMS, low-quality arbitrage and one-off events—delivering poor ROI in 2024.
Desktop CTR ~0.05% vs video 1.2%; mobile is 58% of web traffic; viewability 45% vs 60% benchmark.
Ad-fraud hit ~$124B (2024); logistics/events eat 30–40% of budgets; SMS conversions <5% despite 98% opens.
Action: divest, reallocate to mobile/CTV/video, or partner out.
| Format | 2024 metric | Action |
|---|---|---|
| Desktop/static | CTR 0.05%/eCPM -35% | Retire |
| WAP/SMS | Open 98%/conv <5% | Exit unless bundled |
| Arbitrage/events | Fraud $124B/logistics 30–40% | Cut/partner |
SME market ~400 million firms worldwide with estimated digital ad spend ~$180 billion in 2024, yet Cheer’s self-serve SME product is nascent with estimated share under 0.5%. If onboarding and ROAS hit SME benchmarks (ROAS 4–6x, CAC down ~30%), growth could accelerate rapidly. Heavy product and support investment is required — decide fast: scale or shelve.
AI-driven creative optimization shows reported CTR lifts of ~10–30% and CPA reductions of ~15–25% in vendor case studies, but remains largely pilot-stage with only a few dozen documented deployments in 2024. Compute and cloud GPU bills plus ML talent (median US ML engineer comp ~150k/year) are material—training/inference budgets often range $5k–$50k/month. Back it if we can prove consistent lift at scale via A/B tests and cohort-level ROI.
High demand for clean attribution and actionable insights meets a crowded field—Chiefmartec counted roughly 10,000 MarTech vendors in 2024—so our low share and long B2B sales cycles persist. Our edge: proprietary vertical data and native integrations can create defensible moats and raise conversion velocity. Invest selectively in segments where vertical wins translate to higher CLTV and shorter payback.
Brands targeting outbound growth face complex compliance and channel fragmentation; early pilots show traction but no dominant position yet, so prioritize rapid partnerships and standardized playbooks to scale cross‑border campaigns.
AR/VR interactive ad formats show strong engagement potential but adoption in 2024 remains patchy as platforms and standards evolve; Snap reports AR campaigns can drive ~2.4x ad recall and ~2.7x purchase intent, yet overall AR/VR ad share of digital spend stayed below single digits in 2024. Small, measurable wins now could convert a Question Mark into a Star later; keep experiments tight, KPI-driven and time-boxed.
SME market ~400M firms, global digital ad spend ~$180B in 2024; Cheer SME share <0.5%, requires rapid scale or shelve. AI creative pilots report CTR +10–30% and CPA -15–25% but need proven A/B ROI. MarTech crowded (~10,000 vendors in 2024); prioritize vertical wins. AR ads show ~2.4x recall (Snap 2024); time-box pilots and scale proven formats.
| Metric | 2024 |
|---|---|
| SME firms | ~400M |
| Digital ad spend | $180B |
| Cheer SME share | <0.5% |
| MarTech vendors | ~10,000 |


