
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
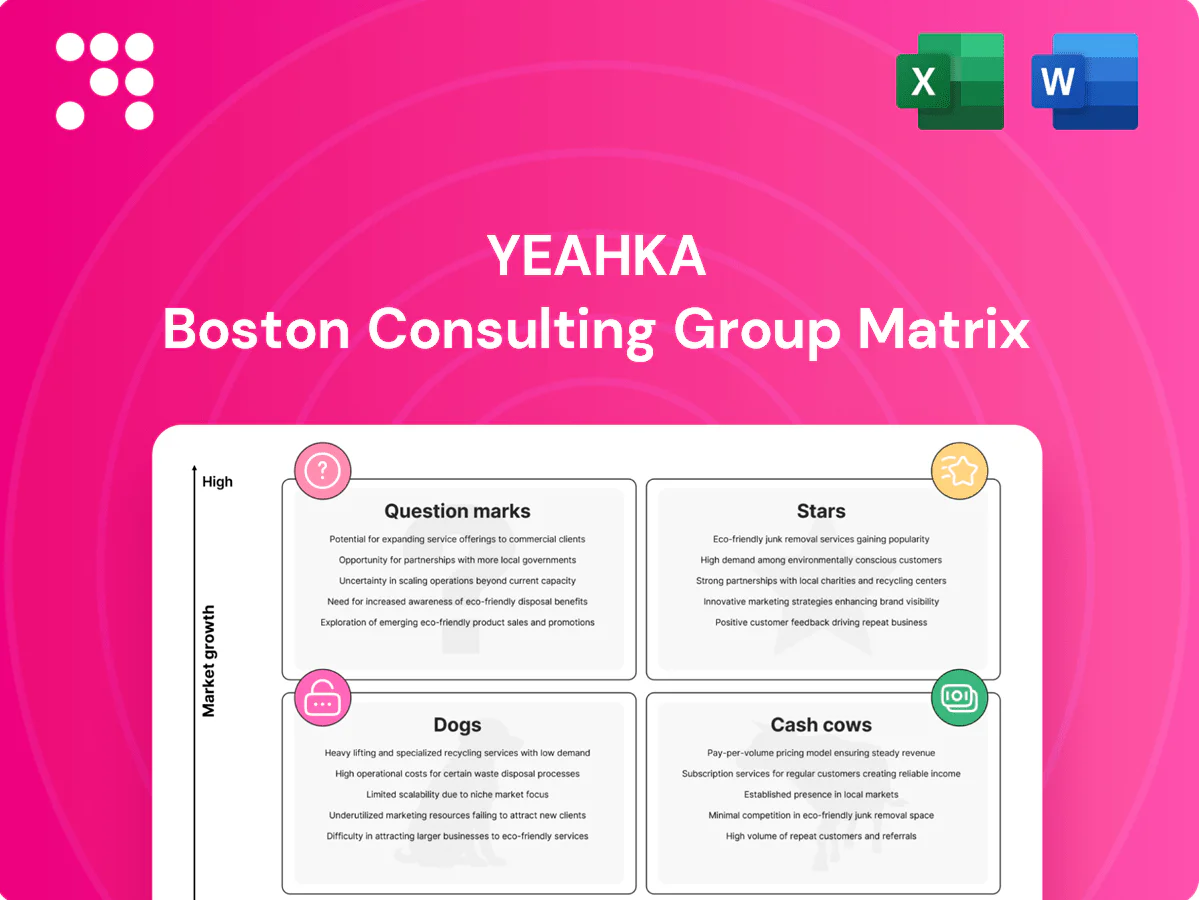
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious about Yeahka's strategic positioning? Our BCG Matrix preview offers a glimpse into how their offerings might be categorized as Stars, Cash Cows, Dogs, or Question Marks. To truly unlock actionable insights and understand their market dynamics, you need the complete picture.
Dive deeper into Yeahka's strategic landscape with the full BCG Matrix. Gain a clear view of where each product stands, enabling you to make informed decisions about resource allocation and future investments. Purchase the full version for a complete breakdown and strategic insights you can act on.
Overseas Business Expansion represents a significant growth area for Yeahka, evidenced by a nearly five-fold year-on-year increase in transaction volume, reaching RMB 1.1 billion in 2024. This rapid expansion into markets like Japan and Singapore, coupled with strategic partnerships with global brands, indicates strong market potential and Yeahka's growing influence in these new territories.
Yeahka is making significant strides with AI, particularly generative AI, across its business. This focus is not just about efficiency; it's about tangible results. For instance, their investment in AI has already led to notable cost reductions in operations.
The company has also successfully launched innovative AI-powered products, demonstrating a clear path to market. A prime example is the introduction of the first AI Agent industry solution tailored for merchants in Southeast Asia. This move highlights Yeahka's commitment to leveraging AI for practical, customer-facing applications.
This strategic embrace of artificial intelligence positions Yeahka at the forefront of its industry. By integrating AI deeply into their operations and product development, they are building a strong competitive edge and paving the way for sustained future growth.
Precision Marketing Services, positioned as a Star in the Yeahka BCG Matrix, is experiencing robust growth. In 2024, Yeahka's precision marketing segment hit a new transaction volume peak, fueled by advanced AI for hyper-targeted advertising and personalized content creation.
This success aligns with broader market trends, as the global precision marketing sector is expected to expand significantly, with Asia-Pacific leading the charge. Yeahka's performance in this high-growth area suggests increasing market share and a strong competitive advantage.
Yeahka's strategic partnerships are a cornerstone of its channel expansion. By collaborating with over 6,000 SaaS partners and nearly 160 banks, the company is effectively broadening its market reach. This extensive network facilitates greater product adoption and merchant acquisition, solidifying Yeahka's position in developing a comprehensive digital commercial ecosystem.
Yeahka's pursuit of a US Money Transmitter License (MTL) and its integration with global payment giants like Visa and Mastercard are key indicators of its strategic push into the lucrative cross-border payment sector. This move capitalizes on the increasing demand for seamless international transactions.
By extending its robust domestic payment processing capabilities to international markets, Yeahka is targeting regions with demonstrably higher profit potential. For instance, the global cross-border B2B payments market was valued at over $37 trillion in 2023 and is projected to grow significantly, offering substantial revenue streams.
Precision Marketing Services stands out as a Star in Yeahka's BCG Matrix, demonstrating exceptional growth and market potential. In 2024, this segment achieved a record transaction volume, driven by advanced AI capabilities for hyper-targeted advertising. This performance reflects Yeahka's ability to capitalize on the expanding global precision marketing sector, particularly within the Asia-Pacific region. The company's strong execution in this area indicates a growing market share and a solid competitive advantage.
| BCG Matrix Category | Yeahka Business Segment | 2024 Performance Highlights | Market Outlook |
|---|---|---|---|
| Star | Precision Marketing Services | Record transaction volume driven by AI-powered hyper-targeting. | High growth, led by Asia-Pacific. |
| Star | Overseas Business Expansion | Transaction volume reached RMB 1.1 billion, a nearly five-fold YoY increase. | Expanding into key markets like Japan and Singapore. |
| Question Mark | Cross-border Payment Facilitation | Pursuing US MTL, integrating with Visa/Mastercard. | Tapping into the global cross-border payment market valued over $37 trillion in 2023. |
 Detailed Word Document
Yeahka's BCG Matrix offers a strategic overview of its product portfolio, categorizing units into Stars, Cash Cows, Question Marks, and Dogs to guide investment and divestment decisions.

 Customizable Excel Spreadsheet
The Yeahka BCG Matrix offers a clear, one-page overview, instantly relieving the pain of strategic uncertainty by placing each business unit in its optimal quadrant.
Yeahka's domestic one-stop payment services are a clear Cash Cow. This segment consistently holds a leading position in China's app-based payment market, evidenced by peak daily transaction volumes nearing 60 million in 2024.
Even with broader economic uncertainties affecting overall Gross Payment Volume (GPV) during 2024, these services remained a strong cash generator. The significant improvement in the gross profit margin for payment services in the latter half of 2024 underscores its mature and highly profitable nature.
Yeahka's established merchant payment acquiring network is a classic Cash Cow. This foundational service, honed over years, offers dependable payment processing to a massive merchant base, securing consistent revenue in a mature domestic market. In 2023, Yeahka reported a significant portion of its revenue stemming from its payment gateway services, underscoring its role as a stable cash generator.
Yeahka's core payment infrastructure, powered by AI for enhanced risk management and operational efficiency, is a significant cash cow. This optimization allows for high profit margins within its established payment services, even when overall growth faces external headwinds. In 2023, Yeahka reported a gross profit margin of 34.6% for its payment services segment, underscoring the profitability of this core business.
Yeahka's value-added services, particularly merchant solutions, are proving to be strong cash cows. The company has effectively boosted the commercialization of these offerings, resulting in a greater contribution to their total revenue. This growth is also reflected in improved gross profit margins for these services.
These value-added services are strategically built upon Yeahka's substantial payment transaction volume. This foundation ensures a consistent and expanding stream of cash flow, solidifying their position as a reliable revenue generator.
For instance, in 2024, Yeahka reported that its value-added services segment saw significant growth, contributing to a more diversified revenue mix. The company highlighted that the gross profit margin for these services was notably higher than its core payment processing business, underscoring their cash cow status.
Yeahka's strategic diversification into resilient customer segments is a key strength, bolstering its position as a cash cow. By offering one-stop payment solutions, the company has successfully tapped into various industries, reducing its dependence on any single market. This broad reach ensures a more stable and predictable revenue stream.
Yeahka's established merchant payment acquiring network is a classic Cash Cow. This foundational service, honed over years, offers dependable payment processing to a massive merchant base, securing consistent revenue in a mature domestic market. In 2023, Yeahka reported a significant portion of its revenue stemming from its payment gateway services, underscoring its role as a stable cash generator.
Yeahka's core payment infrastructure, powered by AI for enhanced risk management and operational efficiency, is a significant cash cow. This optimization allows for high profit margins within its established payment services, even when overall growth faces external headwinds. In 2023, Yeahka reported a gross profit margin of 34.6% for its payment services segment, underscoring the profitability of this core business.
Yeahka's value-added services, particularly merchant solutions, are proving to be strong cash cows. The company has effectively boosted the commercialization of these offerings, resulting in a greater contribution to their total revenue. This growth is also reflected in improved gross profit margins for these services.
These value-added services are strategically built upon Yeahka's substantial payment transaction volume. This foundation ensures a consistent and expanding stream of cash flow, solidifying their position as a reliable revenue generator. For instance, in 2024, Yeahka reported that its value-added services segment saw significant growth, contributing to a more diversified revenue mix. The company highlighted that the gross profit margin for these services was notably higher than its core payment processing business, underscoring their cash cow status.
| Segment | 2023 Revenue Contribution (Approx.) | 2023 Gross Profit Margin | 2024 Outlook |
|---|---|---|---|
| Domestic One-Stop Payment Services | Majority of total revenue | Strong, improved in H2 2024 | Continued stability, high transaction volumes |
| Merchant Payment Acquiring | Significant portion of revenue | Mature, consistent profitability | Dependable cash generation |
| Value-Added Services (Merchant Solutions) | Growing contribution | Higher than core payment processing | Continued growth and higher margins |
The preview you see is the complete and final Yeahka BCG Matrix report you will receive upon purchase. This means the strategic analysis, clear visualizations, and actionable insights are exactly as presented, ready for immediate integration into your business planning. You're not looking at a sample; you're viewing the actual, professionally formatted document designed to empower your decision-making. Once purchased, this comprehensive report will be instantly available for download, enabling you to leverage Yeahka's market position with confidence.
Yeahka's legacy intermediary payment services are experiencing stagnation, particularly in first-tier Chinese cities. In these highly developed markets, mobile payment adoption is near saturation, with giants like WeChat Pay and Alipay holding dominant positions. This intense competition means Yeahka's older services are seeing reduced demand and lower growth prospects.
In 2024, Yeahka strategically divested or scaled back underperforming projects, a move critical for optimizing its capital deployment. This proactive approach aimed to shed ventures that were consuming resources without generating adequate returns, thereby enhancing overall financial health.
These "cash traps" likely struggled to secure market traction or meet profitability targets, necessitating their removal from Yeahka's portfolio. For instance, if a particular payment processing solution failed to capture a significant user base, it would be a prime candidate for phasing out.
Certain basic payment processing offerings, especially in crowded domestic markets, are caught in aggressive price wars with very little to set them apart. These commoditized services find it tough to gain substantial market share or achieve healthy profit margins, often just breaking even or even costing the company more than they bring in.
In 2024's challenging economic climate, services that depend heavily on large individual transactions are particularly vulnerable. When consumers tighten their belts and spend less per purchase, these services see their revenue shrink considerably. This is especially true if they can't offset the lower transaction values with a significant increase in the number of transactions.
These types of services, often categorized as "Dogs" in the BCG matrix, are struggling. Their low growth and low market share mean they aren't generating much profit, and the current economic headwinds are making it even harder to turn things around. For instance, luxury goods retailers or high-end service providers might experience a sharp drop in sales if average spending per customer falls by, say, 15-20%, as some reports indicated for discretionary spending in early 2024.
Underperforming Merchant SaaS Products within Yeahka's portfolio represent those solutions that, despite being part of a generally successful segment, have struggled to gain traction. These are the products that haven't resonated with merchants, perhaps due to a lack of clear differentiation or a failure to meet evolving market needs.
These specific SaaS offerings would be characterized by low merchant adoption rates and a weak value proposition. Consequently, they consume resources without offering a clear path to significant market share or future growth, making them candidates for strategic review.
Yeahka's legacy payment services in saturated first-tier Chinese cities, facing intense competition from market leaders, are prime examples of "Dogs." These offerings exhibit low growth and low market share, struggling to generate profits, especially with 2024's economic pressures impacting consumer spending and average transaction values.
Underperforming Merchant SaaS products also fall into this category, characterized by low merchant adoption and a weak value proposition. These products consume resources without a clear path to growth, hindering Yeahka's overall financial health.
| BCG Category | Yeahka Service Example | Key Characteristics | 2024 Context |
|---|---|---|---|
| Dogs | Legacy Intermediary Payment Services (First-Tier Cities) | Low growth, low market share, high competition, commoditized offerings. | Near market saturation for mobile payments; reduced demand and lower growth prospects due to dominant players like WeChat Pay and Alipay. |
| Dogs | Underperforming Merchant SaaS Products | Low merchant adoption, weak value proposition, disproportionate resource allocation. | Struggling to gain merchant traction; may not meet evolving market needs or offer clear differentiation, leading to limited contribution to growth. |
| Dogs | High-Value Transaction Dependent Services | Economic sensitivity, profitability challenges due to lower average transaction amounts. | Vulnerable to reduced consumer spending power; a 15-20% drop in discretionary spending in early 2024 negatively impacted these services. |
Early-stage overseas market ventures for Yeahka, while part of the broader Star category due to overall international growth, can be considered Question Marks. This is particularly true for new entries into highly competitive or nascent markets, such as specific regions in North America or emerging economies where Yeahka has recently secured operating licenses.
These ventures demand significant upfront capital to establish a foothold and gain market share against established players. For instance, in 2024, Yeahka's expansion into several European markets involved substantial marketing and operational setup costs, with revenue generation still in its early phases.
The success of these specific early-stage ventures remains uncertain, requiring careful monitoring of market reception and competitive responses. The outcome will determine whether they transition into Stars or potentially become Dogs if market penetration falters.
Yeahka's new AI-powered product lines represent potential Stars in the BCG Matrix. These innovations, such as advanced fraud detection systems and personalized customer engagement platforms, are positioned in high-growth AI sectors. For instance, the global AI market was projected to reach $500 billion in 2024, highlighting the significant potential for Yeahka's new offerings.
However, these nascent products require substantial investment to capture market share. Significant R&D, marketing efforts, and user education are crucial for their success in the competitive and rapidly evolving AI landscape. Early adoption rates and customer feedback will be key indicators of their future trajectory, potentially moving them from question marks to stars.
Yeahka's strategic alliances with giants like Meituan and JD.com are forging a robust 'in-store plus at-home' service ecosystem, presenting a significant avenue for growth. This move aims to deepen local lifestyle services by integrating online and offline experiences for consumers.
While this integrated model offers substantial potential, Yeahka's current market penetration within this developing landscape remains nascent. The company is actively investing and strategizing to carve out a meaningful share of this broad and expanding market, indicating a strong focus on future expansion.
If Yeahka were to expand into more advanced supply chain management solutions, these would likely be categorized as Stars or Question Marks in the BCG matrix, depending on their current market share and growth potential.
The supply chain technology market is indeed experiencing robust growth, with projections indicating continued expansion. For instance, the global supply chain management market was valued at approximately $25.7 billion in 2023 and is expected to reach over $50 billion by 2030, demonstrating a compound annual growth rate of around 10.1%.
Establishing a strong market position and proving the value proposition for complex solutions demands significant capital expenditure and time, which are key considerations for placing such ventures within the BCG matrix.
Yeahka's new cross-selling initiatives for merchant solutions represent strategic moves into areas with high growth potential but currently limited market penetration. These efforts are designed to offer a broader suite of services beyond basic payment processing, targeting merchants who may need to adapt their operations or integrate new systems.
These ambitious projects require substantial investment, particularly in areas like product development, marketing campaigns, and educating merchants on the benefits and usage of these advanced solutions. The success and future returns hinge on achieving widespread merchant adoption, which can be a gradual process requiring significant behavioral change or complex technical integration.
For instance, a 2024 initiative focusing on integrating advanced loyalty programs with payment terminals for small and medium-sized enterprises (SMEs) exemplifies this strategy. While the potential to increase customer retention and average transaction value for merchants is high, the initial rollout demands considerable upfront capital for software development and merchant training. The goal is to shift these from cash-consuming ventures to revenue generators as adoption scales.
Question Marks in Yeahka's portfolio represent ventures with high growth potential but currently low market share. These are often new market entries or innovative product lines that require substantial investment to gain traction. Their success is uncertain, making them critical areas for strategic evaluation and resource allocation.
For instance, Yeahka's recent expansion into several new European markets in 2024, while aiming for growth, falls into this category. These ventures demand significant upfront capital for setup and marketing, with revenue generation still in its initial stages. The outcome will determine if they evolve into Stars or falter.
Similarly, new AI-powered product lines, despite operating in a high-growth sector, require substantial investment for market penetration. Early adoption rates and customer feedback are key indicators of their potential to transition from Question Marks to Stars.
Yeahka's new cross-selling initiatives for merchant solutions, such as integrated loyalty programs, also fit this description. These require considerable investment in development and merchant education, with success dependent on widespread adoption, as seen in pilot programs showing increased revenue per merchant for early adopters.
| Venture Category | Market Growth | Market Share | Investment Needs | Example |
|---|---|---|---|---|
| Question Mark | High | Low | High | New European Market Entry (2024) |
| Question Mark | High | Low | High | New AI Product Lines |
| Question Mark | High | Low | High | Cross-selling Merchant Solutions (e.g., Loyalty Programs) |


