
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
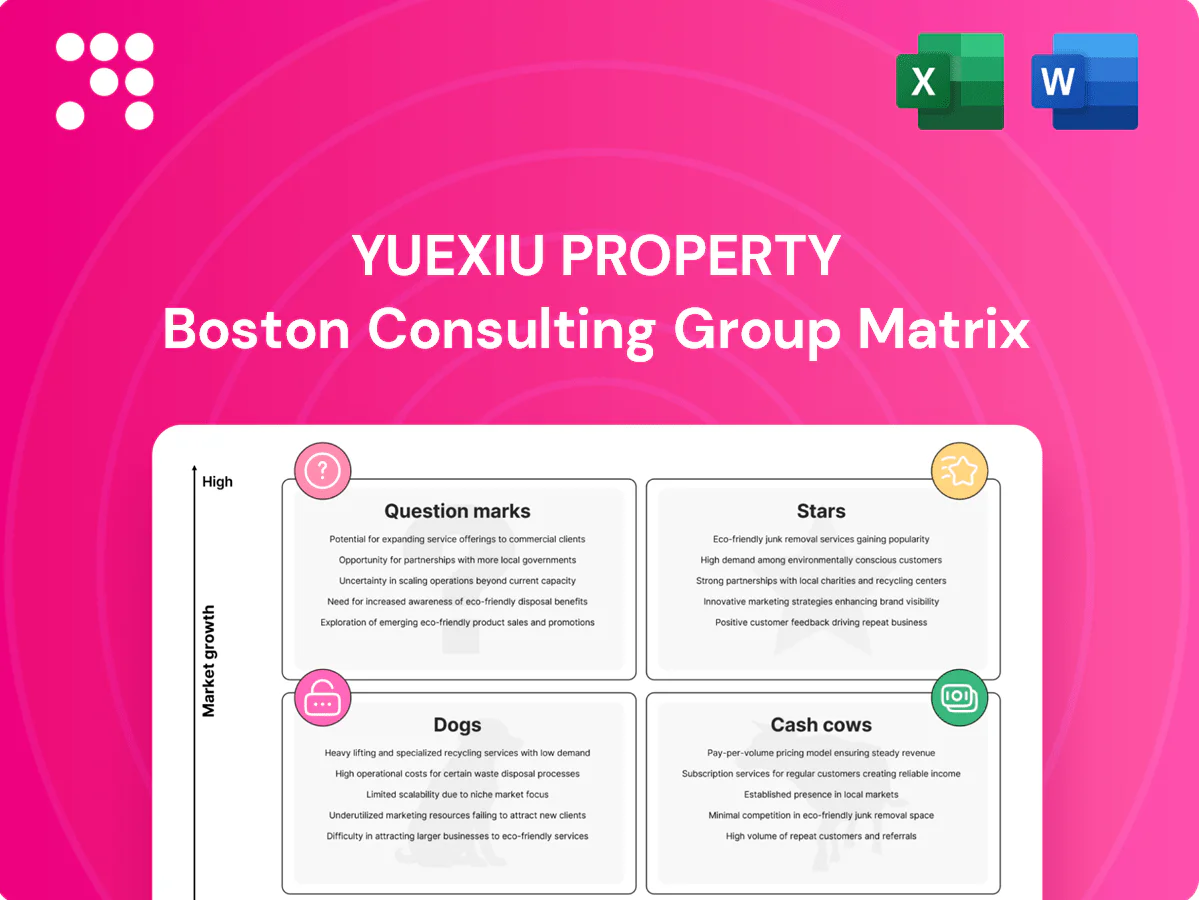
Yuexiu Property’s BCG Matrix snapshot shows which business lines are fueling growth and which are tying up cash—useful, but incomplete. Want quadrant-level clarity on residential, commercial and rental assets? Purchase the full BCG Matrix for a detailed Word report plus an editable Excel summary, actionable recommendations, and a clear capital-allocation roadmap you can use right away.
Yuexiu Property (HKEX: 0123) sees its Tier‑1 residential pipeline as Stars: high-velocity presales in core cities keep market share elevated while demand recovers. These flagship projects lead brand perception and concentrate marketing and placement spend. They retain pricing power but require continuous landbanking to stay ahead. Keep investing to defend share and push toward leadership.
Yuexiu Property (HKEx 00123) leverages flagship integrated mixed‑use hubs to anchor footfall and cross‑sell residential, office and retail, capturing dense urban demand where China’s urbanization is about 65% and Guangzhou’s metro population tops roughly 15.3 million. Market growth in urban cores supports cash‑neutral expansion and activation; being first or largest in micro‑markets sustains pricing power. Double down on tenant curation and placemaking to cement the lead.
High-occupancy, investment-grade Grade-A offices in major CBDs capture outsized share as China’s public REIT pilot (launched 2020) expanded through 2024 into commercial assets; institutional demand and typical CBD occupancy exceeding 85% drive stable cashflow. These assets yield solid operating cash yet need ongoing capex and active asset management. Listing or linking to REIT vehicles sustains the funding flywheel and building a pipeline converts current momentum into future cash cows.
In 2024 Yuexiu Property premium management posted rapid subscriber growth (up 28% y/y), strong renewal rates (~85%) and higher-value add-on services (~22% of service revenue); scale pushed unit costs down c.12% but growth required continued tech and ops spend (RMB300m capex in 2024).
Urbanization (China urbanization rate 64.7% in 2023) and concentrated talent inflows drive strong rental demand in core clusters; Yuexiu’s early-mover footprint in select nodes gives it critical mass and share-gain potential, but high growth requires heavy capex and tight operations so cash is rapidly redeployed.
Yuexiu Property Stars: flagship residential and mixed‑use projects deliver rapid presales and defend urban share, leveraging Guangzhou scale and >85% CBD office occupancy. Premium management grew subscribers 28% in 2024 with RMB300m tech/ops capex; urbanization supports demand but high capex keeps cash redeployed. Continue landbanking and REIT linkage to convert growth into future cash cows.
| Metric | 2023/2024 |
|---|---|
| China urbanization | 64.7% (2023) |
| Premium subs growth | 28% (2024) |
| Renewal rate | ~85% |
| Tech/ops capex | RMB300m (2024) |
| CBD occ. | >85% |
 Detailed Word Document
Comprehensive BCG Matrix review of Yuexiu Property: identifies Stars, Cash Cows, Question Marks and Dogs with clear investment guidance.

 Customizable Excel Spreadsheet
One-page Yuexiu Property BCG Matrix placing each business unit in a quadrant for quick C-suite decisions
Mature Guangzhou residencies form Yuexiu Property's cash cows: a large installed base with steady sell-through and limited new-supply pressure in 2024. Low-growth but high-margin assets deliver reliable cash conversion, requiring minimal promotion beyond routine launches. Surplus cash generation in 2024 funded the group's targeted expansion into higher-growth city entries.
Stabilized retail + community malls in established neighborhoods deliver predictable footfall and lease rolls that remain manageable, with portfolio occupancy typically above 90% and steady tenant retention. Growth is modest but NOI is durable, driven by resilient daily-consumption tenants and controlled operating costs. Capex is focused on maintenance and selective refresh (low single-digit percent of property revenue), with cash flow earmarked for the development pipeline and ongoing deleveraging.
Leased-up Grade-A assets house sticky blue-chip tenants, supporting recurring office income with portfolio occupancy near 92% in 2024 and rental revenue up roughly 3% YoY. Market growth is muted but rents and occupancy remain steady, enabling asset-management tweaks that lift margins without heavy capex. Strategy: harvest cash, refinance prudently, and channel surplus into selective growth bets.
Base property management contracts across Yuexiu residential estates generate steady fee income, with incremental upsell potential while core services scale efficiently; low churn follows consistent service norms and standardized SOPs. Maintaining service quality and margin expansion hinges on tech-driven workflows and optimized service routes.
Yuexiu Propertys parking and ancillary services produce steady, low-growth cash flows from an installed parking inventory with predictable operating costs and limited competitive threats. Marginal yield improvements from pricing, automation and occupancy management lift cash generation. Maintain a lean cost base and direct surplus to cover corporate overheads and reinvestment.
Mature Guangzhou residencies, stabilized retail/malls and Grade-A offices acted as Yuexiu Property cash cows in 2024, delivering high cash conversion with portfolio occupancy ~91% and rental revenue +3% YoY. Capex stayed low (2–4% of property revenue) while parking and property‑management fees provided stable, low‑growth cash flows earmarked for deleveraging and selective expansion.
| Asset | 2024 metric | Notes |
|---|---|---|
| Guangzhou residential | Occupancy ~91% | Steady sell‑through, low new supply |
| Retail/malls | Occupancy >90% | NOI durable, tenant retention high |
| Grade‑A office | Occupancy ~92%, rent +3% YoY | Sticky blue‑chip tenants |
| Capex | 2–4% rev | Maintenance/refresh only |
The file you're previewing here is the exact Yuexiu Property BCG Matrix you'll receive after purchase. No watermarks, no placeholder notes—just a polished, ready-to-use strategic report. It’s formatted for clarity and quick presentation, so you can edit, print, or share immediately. Buy once, download instantly, and plug it straight into your planning or investor decks.
Lower‑tier city land banks at Yuexiu Property face soft demand, slow absorption and weak pricing power in 2024, leaving capital idle while holding costs and interest eat margins. Turnaround plans rarely clear investment hurdles given prolonged sales softness and elevated financing spreads. Prioritize divestment or joint‑development exits to unlock value and cut carrying costs.
Legacy commercial blocks in non-prime locations struggle to attract stable tenants and show persistently high vacancy, forcing capex that outpaces rental gains and compresses cash flow.
These assets neither earn meaningful returns nor scale within Yuexiu Property’s portfolio, creating operating drag and capital inefficiency.
Dispose or repurpose quickly to stop cash traps and redeploy capital into higher-yield, core urban projects.
Small non-core hospitality stakes show volatile occupancy—STR data indicate China hotel occupancy rebounded to roughly 60% by 2023–24—while high operating leverage dilutes returns and magnifies downturn losses. Limited management focus and weak synergies with Yuexiu Property’s core residential and commercial portfolio reduce strategic value. These assets are cash-breakeven at best, often capex-hungry for renovations and compliance. Consider sale or conversion to alternate uses to unlock capital and improve ROE.
Dogs:
One-off remote projects sit outside Yuexiu Property’s core clusters and fail to capture scale advantages, driving per-unit marketing and operations costs that erode margins and push these assets into the Dogs quadrant.
Market share on these standalone sites remains low with limited growth tailwinds given urbanization patterns and channel focus on core hubs, so strategic options are limited.
Recommendation: wind down sales and development, or seek joint-venture or asset-sale partnerships to stop cash bleed and redeploy capital to high-performing clusters.
Dogs are lower‑tier land banks with idle capital and weak absorption, legacy non‑prime commercial with persistently high vacancy and heavy capex, scattered ageing industrial stock with low utilization, and small hospitality stakes (hotel occupancy ~60% in 2023–24) that are cash‑breakeven—recommend exit, bundle sales, or conversion to stop cash bleed and redeploy capital.
| Asset | Key metric (2023–24) | Action |
|---|---|---|
| Lower‑tier land banks | Slow absorption | Divest/joint dev |
| Non‑prime commercial | High vacancy | Redeploy/sell |
| Industrial remnants | Low utilisation | Bundle/sale |
| Hospitality stakes | Occupancy ~60% | Sell/convert |
Urban renewal pipeline offers multi-billion RMB upside if approvals, resettlement and design align, but market share remains unproven for Yuexiu Property given project complexity.
Timelines are long and cash-hungry, often tying up capital for 3–7 years and requiring upfront resettlement funding and infrastructure spend.
With strong execution and favourable 2024 policy tailwinds, these can flip into Stars; commit capital selectively to projects that clear a target IRR above 15% to compensate for execution and policy risk.
Logistics + cold‑chain is a Question Mark: e‑commerce and pharma are driving demand—global cold chain market reached about USD 240 billion in 2024, while China online retail kept double‑digit growth in 2024. Yuexiu’s cold‑chain share is still early‑stage, requiring specialized ops and tenant networks to win pharma clients. With the right 3PL partners and a proven unit economics pilot, it could scale fast.
Young professional demand for co-living and rental upgrades is rising but tastes shift quickly, so brand and experience moat for Yuexiu Property remains unestablished. Returns will hinge on strict occupancy discipline and tight cost control. Prioritize investment where clustering effects and operational scale can drive yield; exit non-clustered assets.
Tenant demand for certified, energy‑efficient buildings is rising and CBRE/2024 data show green assets can earn ~3–5% rent and ~5–7% value premiums, yet pricing power varies by location and quality. Upfront capex is high and payback is uncertain without REIT listing or green financing; if premiums persist this segment becomes a Star wedge for Yuexiu. Pilot, measure and standardize where spreads are proven, starting with 5–10% of portfolio.
Hong Kong redevelopment is a Question Mark for Yuexiu: market can swing fast and entitlements/timing are tricky, with entry tickets typically large (often hundreds of millions HKD) and share not secured; if cycles turn upside can be meaningful given dense urban land scarcity in 2024.
Recommend stage-gate investments and hedging via partnerships and JVs to limit capital exposure while retaining upside optionality; prioritize sites with clearer planning approvals and phased delivery.
Question marks: cold‑chain & green retrofit — target >15% IRR
Urban renewal and logistics/cold‑chain, co‑living and green retrofits are Question Marks: long, capital‑intensive (3–7 yrs), require execution to hit >15% IRR. Global cold chain ~USD 240bn (2024); green assets: +3–5% rent, +5–7% value (CBRE 2024). HK redevelopment needs hundreds-mn HKD entry; use stage‑gates, JV hedges.
| Segment | 2024 data | Action |
|---|---|---|
| Cold‑chain | USD 240bn | Pilot + 3PL partners |
| Green | Rent +3–5% Value +5–7% | Pilot 5–10% portfolio |
| HK | Entry: 100s mn HKD | Stage‑gates/JV |


